Business and Equipment Financing, Matched to Your Needs
Find financing to buy equipment, manage cash flow, or grow your business.
Let’s Get Your Business Funded
What Our Clients Say
I am really happy with the service that was provided. Communication was great and would refer anyone to get financing/leasing done from them.

I had an excellent experience with Mehmi Financial Group! The team made the process of getting qualified for an equipment loan seamless and stress-free. They were professional, responsive, and really took the time to understand my needs. Highly recommend to anyone looking for reliable and efficient equipment financing in Canada!

Super fast responses, very professional, and you can tell they genuinely care about their clients. They stay connected throughout the process and make everything smooth and stress free
Mehmi Financial Group helped us secure an equipment loan in Brampton with a lower down payment than we expected. Fast, professional, and easy to work with.
Expanding my medical practice required new equipment, and the financing solution was exactly what I needed.
One of the best financing services available, they were able to meet my needs and secure funding a timely manner. Very well connected, and supported me in my other business matters.
Mehmi Financial Group simplified our equipment financing process for our small service-based business. Jodh reviewed our financials, explained options, and negotiated terms that fit our budget. The speed, transparency, and clear communication stood out. We’ve used Mehmi for multiple equipment purchases and plan to expand with them. If you’re a Canadian business owner seeking honest, professional equipment financing, I highly recommend Mehmi Financial Group.
Our manufacturing plant needed a new CNC machine, and their financing options were perfect. They truly understand manufacturing & CNC machinery
great people great work, super smooth process. very happy with the outcome and would love to work with the team again.
Zora helped us finance our fleet of commercial trucks and trailers in Windsor and kept the process clear and organized. We got an pre-approval in about 48 hours, and the terms matched what I needed for cash flow. I’d recommend them to Canadian business owners who want straightforward truck financing.

Very happy with the service. Mehmi Financial Group is one of the best in Canada for financing.
I had an excellent experience with Mehmi Financial. They did a great job getting me approved for truck financing and made the whole process smooth and straightforward. The staff is smart, diligent, and always took the time to answer my questions. I highly recommend Mehmi Financial to anyone looking for professional and reliable financing help.
The only solution you can truly rely on when it comes to financing. Jodh was a pleasure to work with and got us financing for equipment in a short amount of time. Very professional team. Would highly recommend them!
Had a great experience with them. They were able to help me secure the funds I needed in a timely manner. Their knowledge on loan structures and find the best solution for me was greatly appreciated. thanks again!
I had an amazing experience working with Mehmi Financial Group. The team was knowledgeable, responsive, and truly went above and beyond. I highly recommend them.
The Mehmi financial group made getting a loan super quick and easy! Would definitely recommend to any fellow truckers.
Got my truck financed through Mehmi financial group . Very hardworking and Knowledgeable team. Zora has been great help throughout the process. He go’s out of his way to make things happen. Very important I would recommend them to all my circle. Thank you so very much.
I had an excellent experience with Mehmi Financial Group. Their team provided professional financial advice that made it much easier for me to manage and organize my finances. They were knowledgeable, responsive, and genuinely cared about helping me reach my financial goals. I’d highly recommend Mehmi Financial Group to anyone looking for trusted, results-driven financial guidance.
What we do
Equipment Financing

Lease equipment. Preserve cash.
Learn more
Business Loans
Capital for everyday business needs.
Learn more
Customer Financing
Offer customers another way to finance eligible purchases.
Learn more
Refinancing & Sale Leaseback
Unlock equipment equity. Keep using it.
Learn more
Invoice & Freight Factoring
Access working capital from eligible invoices.
Learn more
Our Process
Recently Closed & Approved
FUNDED · JUL
$60,967
Truck repair financing
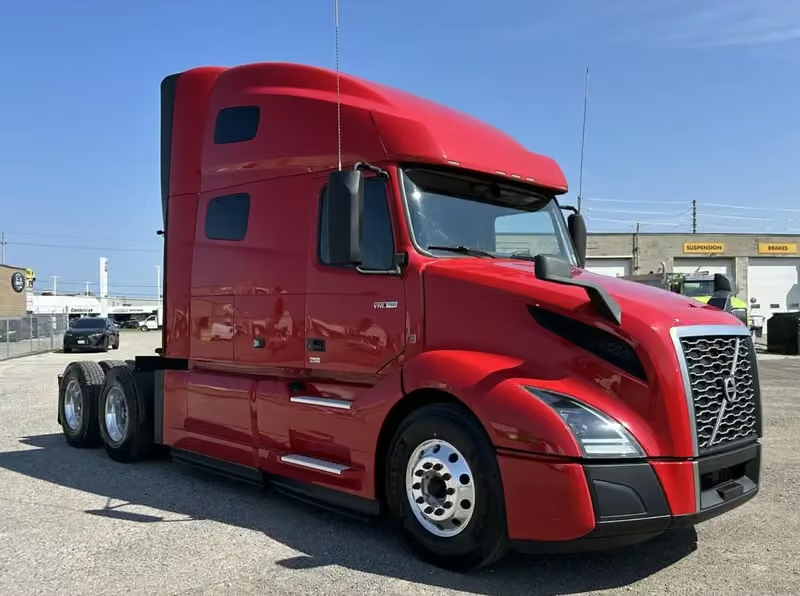
APPROVAL SECURED · FEB
$87,495
2022 Volvo VNL760 sleeper truck
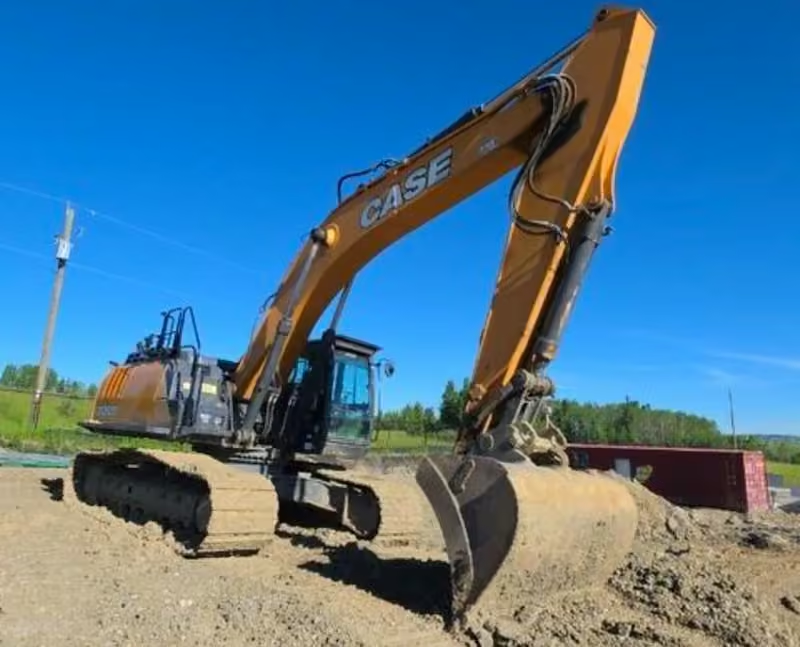
APPROVED · JUN
$218,000
2020 Case CX350 excavator with attachments
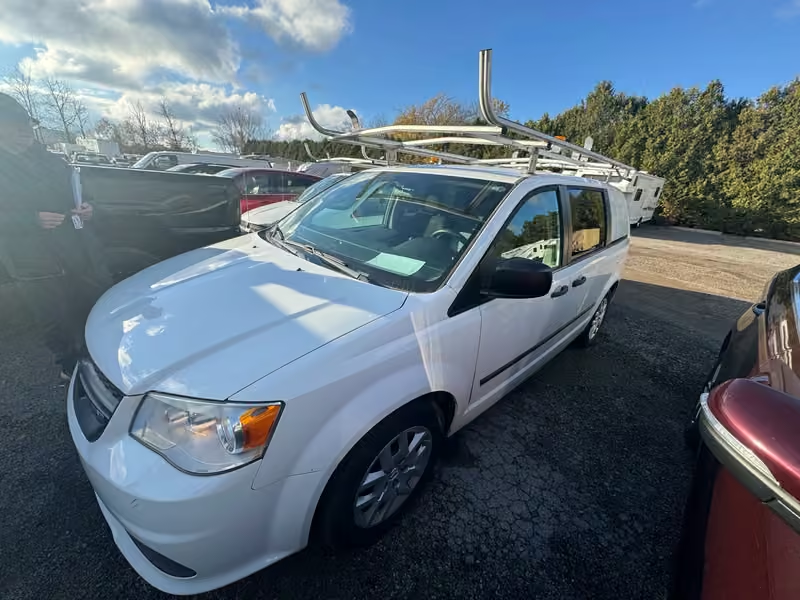
APPROVAL SECURED · OCT
$6,200
2015 Ram cargo van
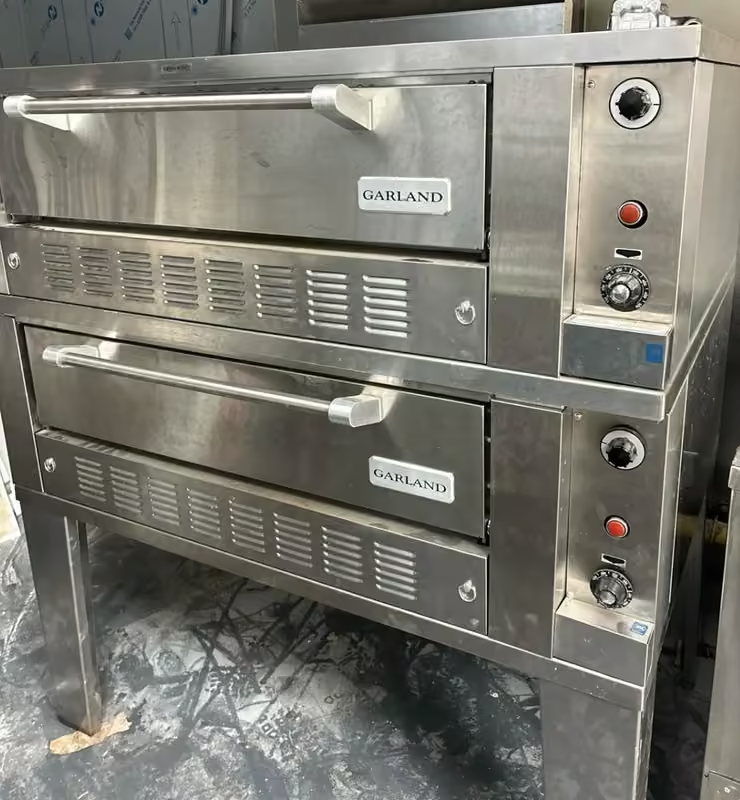
APPROVAL SECURED · OCT
$25,350
2022 Garland double-deck oven
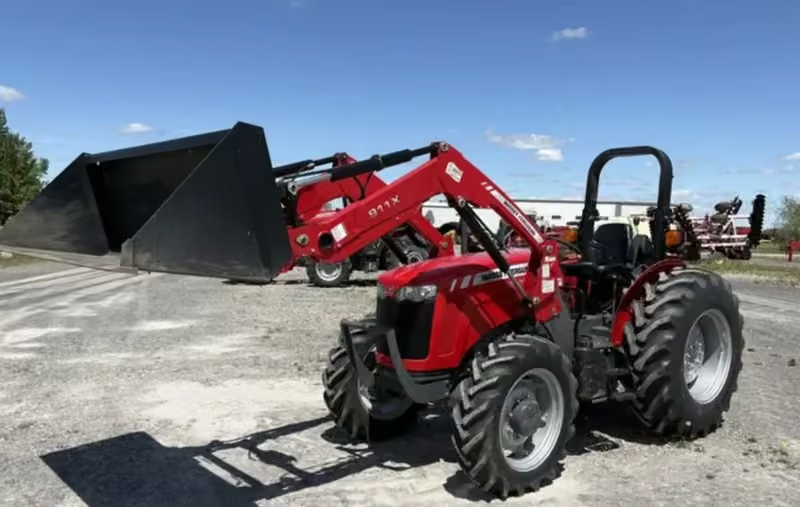
APPROVAL SECURED · FEB
$30,000
2022 Massey Ferguson 2407H tractor
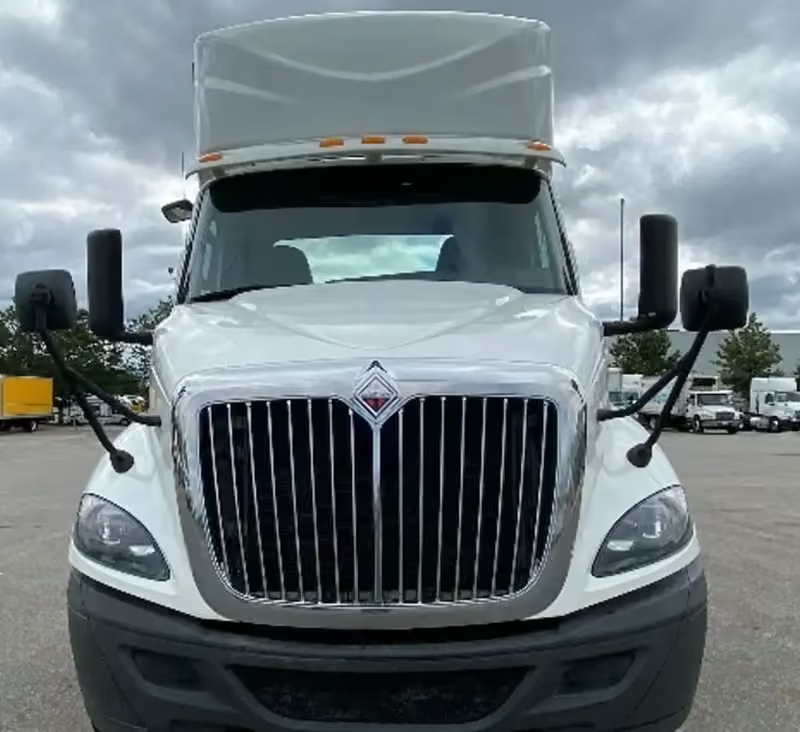
APPROVAL SECURED · MAR
$36,299
2020 International RH613 day cab
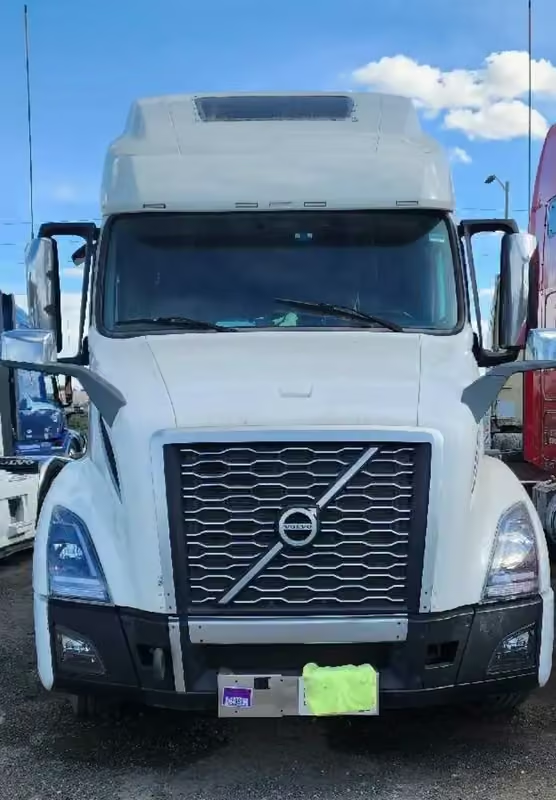
APPROVAL SECURED · NOV
$65,499
2020 Volvo VNL760 commercial truck
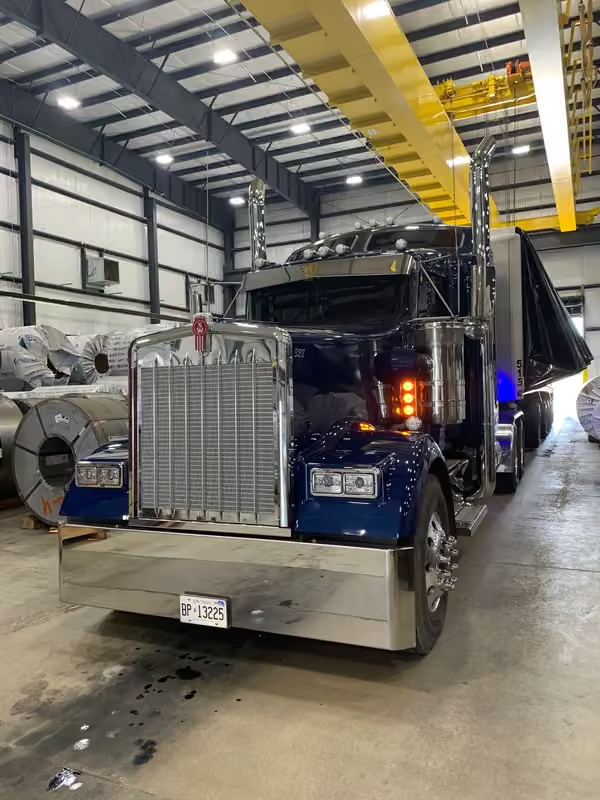
FUNDED · DEC
$150,000
2022 Kenworth W900B truck
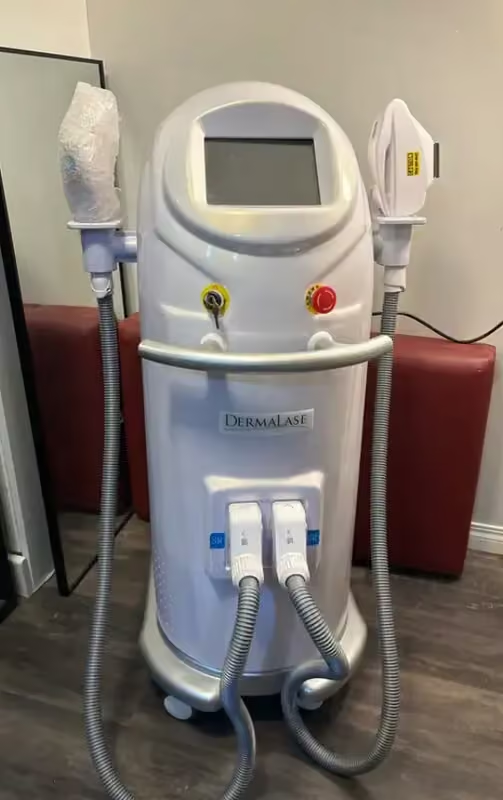
APPROVAL SECURED · FEB
$25,000
Laser hair-removal equipment
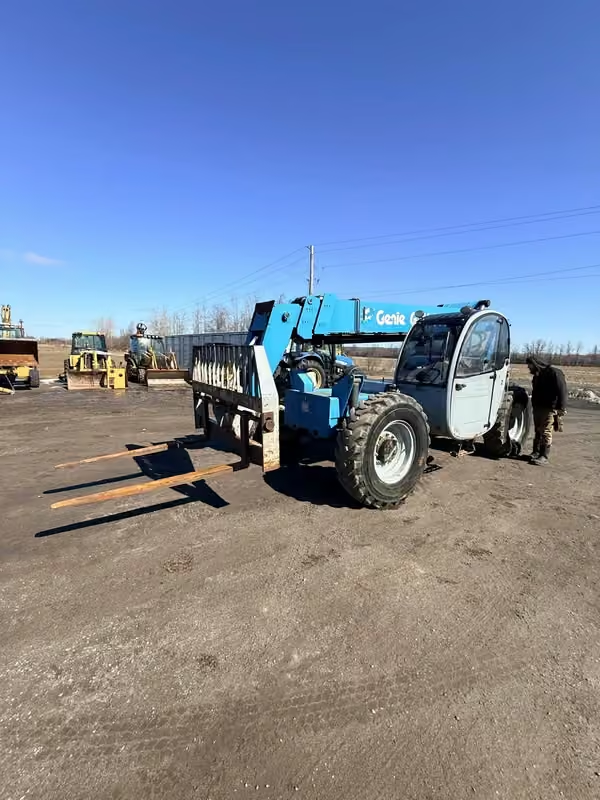
APPROVAL SECURED · MAR
$39,000
2011 Genie GTH844 telehandler
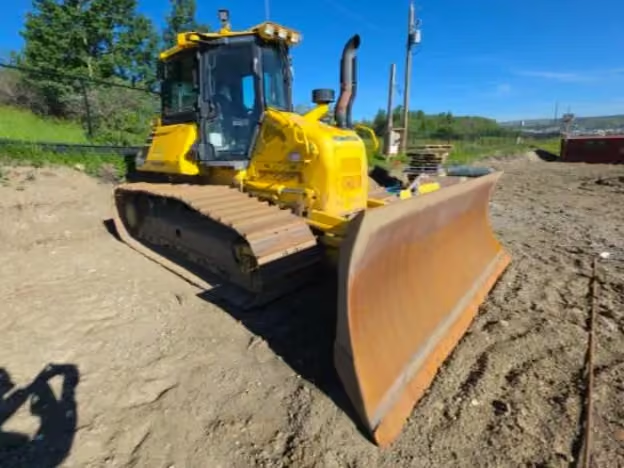
APPROVED · JUN
$104,650
2021 Komatsu D51 bulldozer
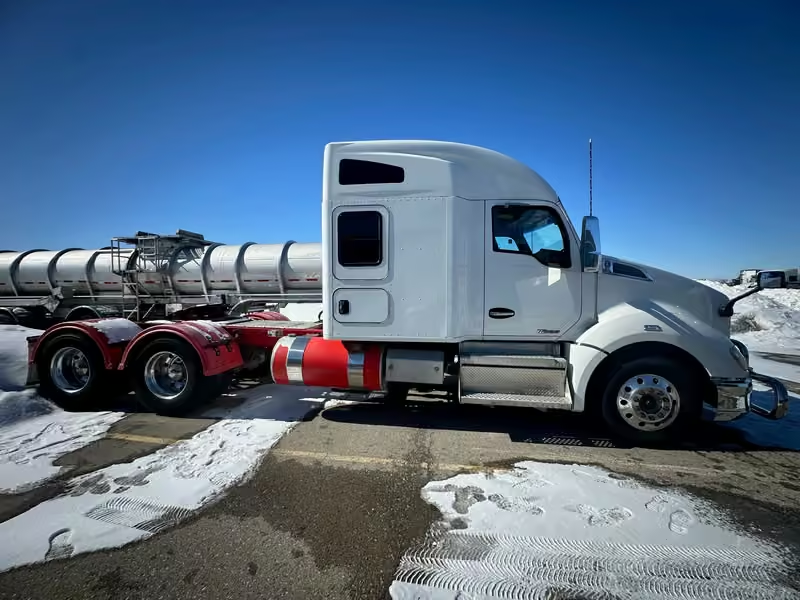
FUNDED · MARCH
$50,000
2021 Kenworth T680 sleeper truck
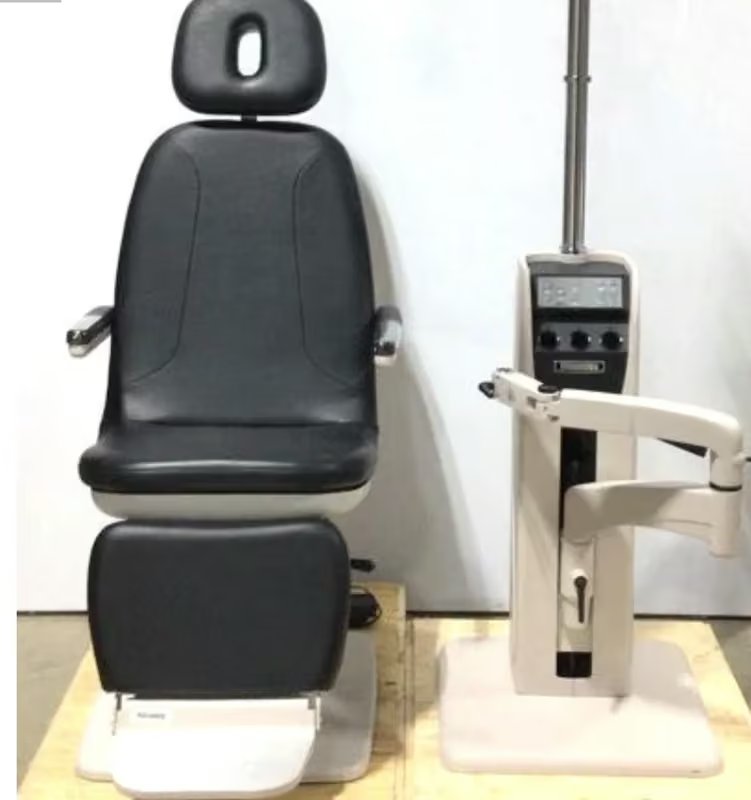
APPROVED · OCTOBER
$200,745
Medical exam-lane equipment
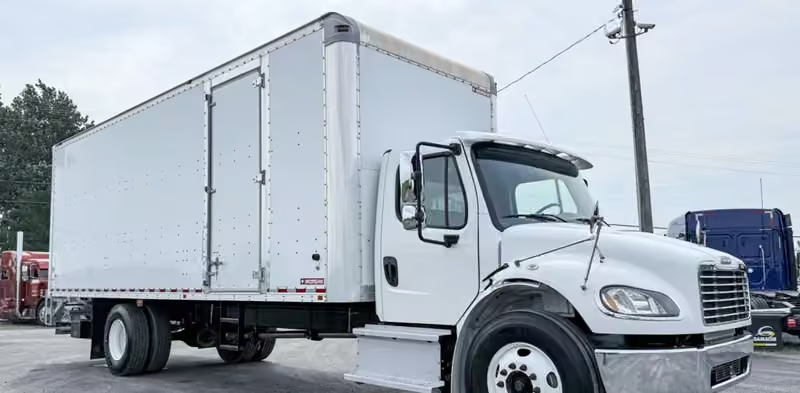
FUNDED · SEPTEMBER
$45,000
2019 Freightliner M2 106 commercial truck