Fast, Easy and Flexible Business and Equipment Financing Across Canada

Get financing for equipment, cash flow, and growth with options matched to your business.

Recently Closed & Approved
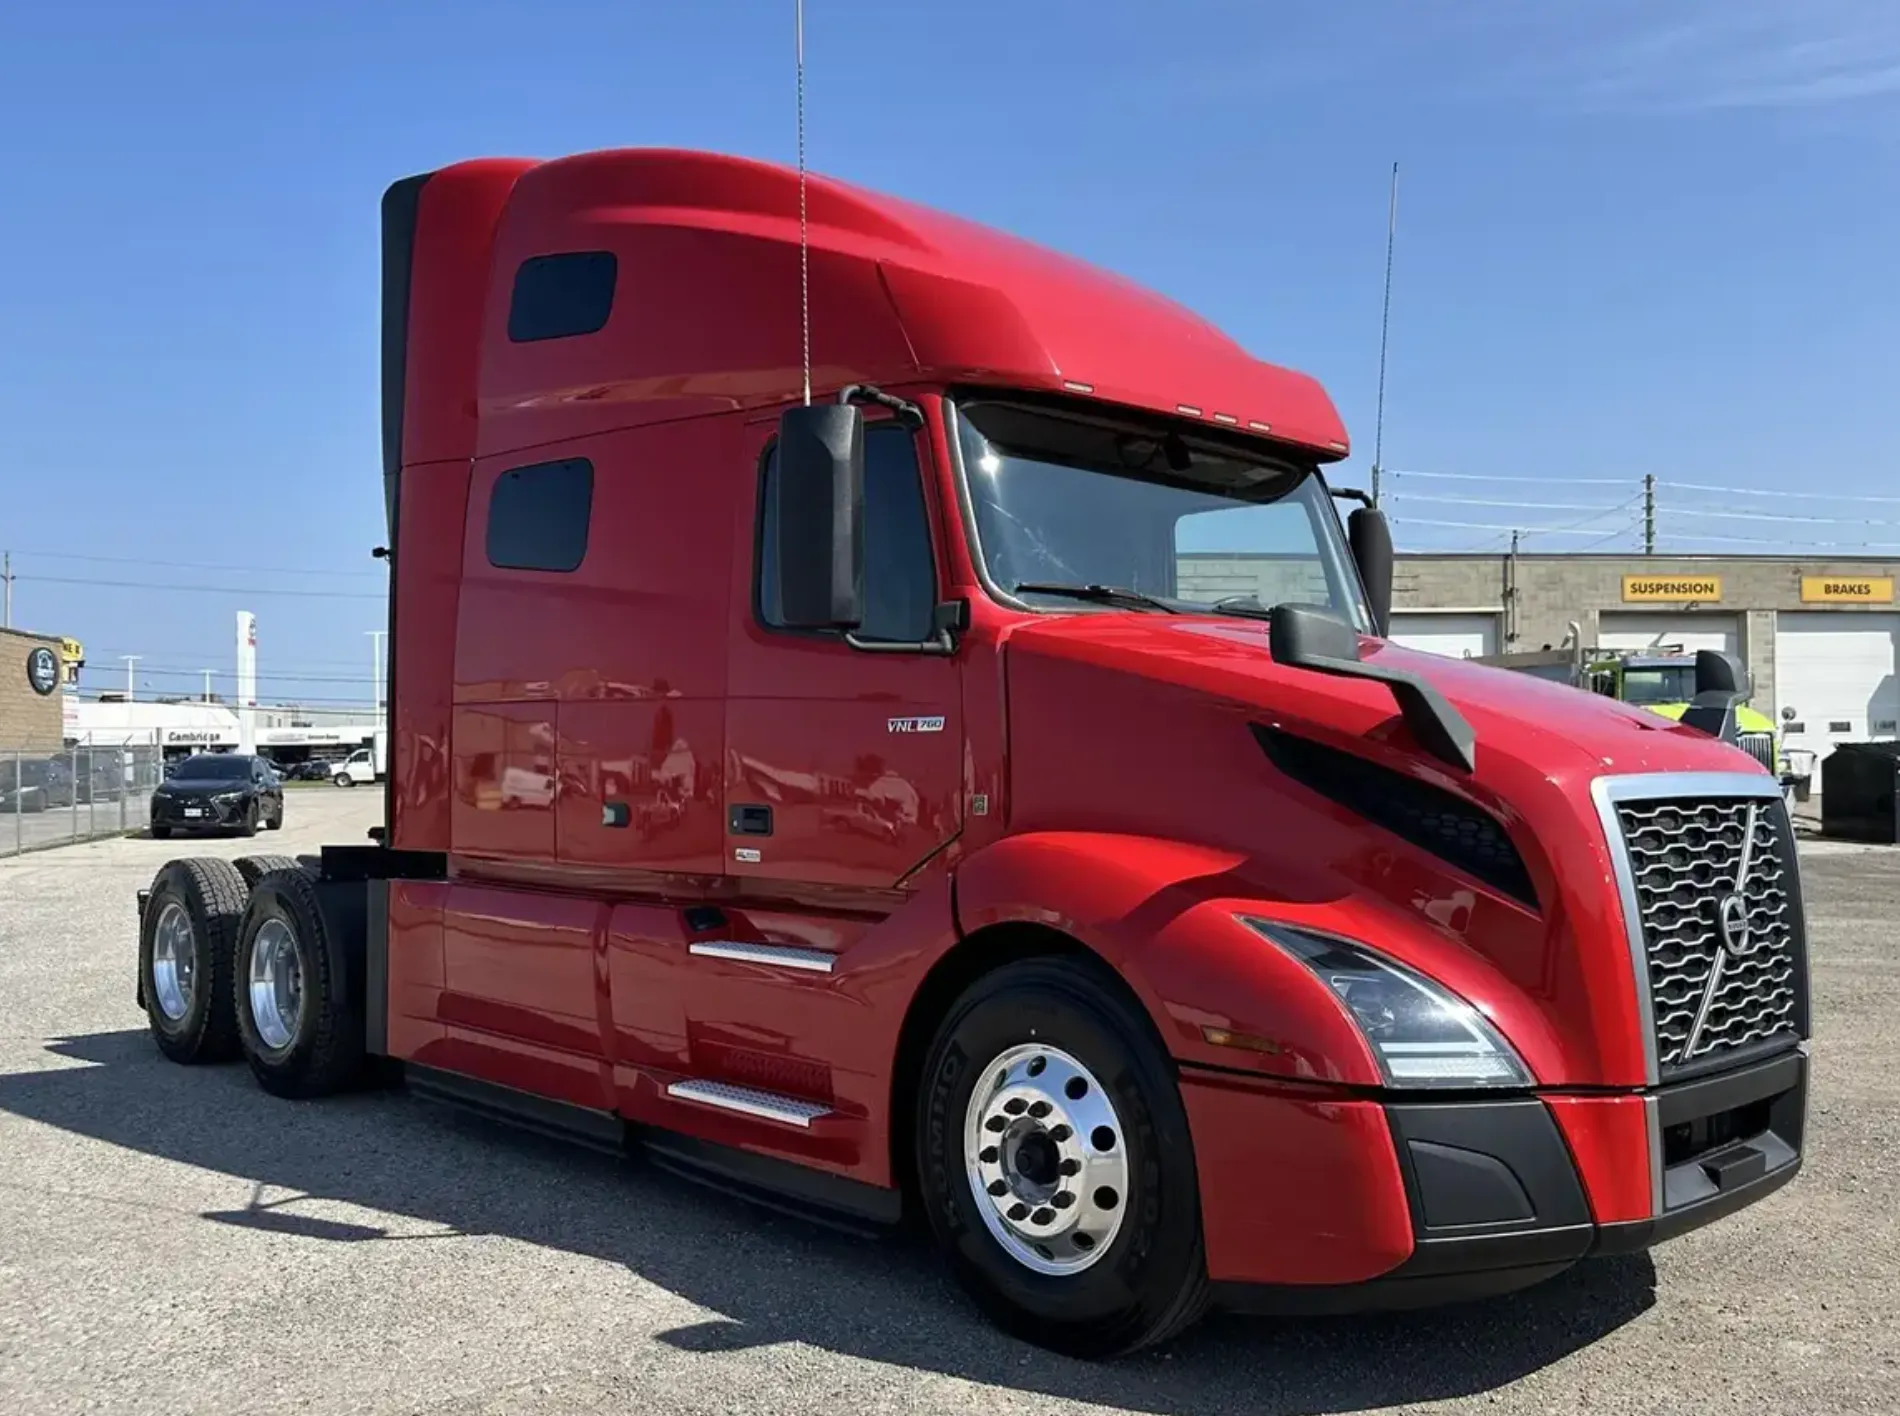
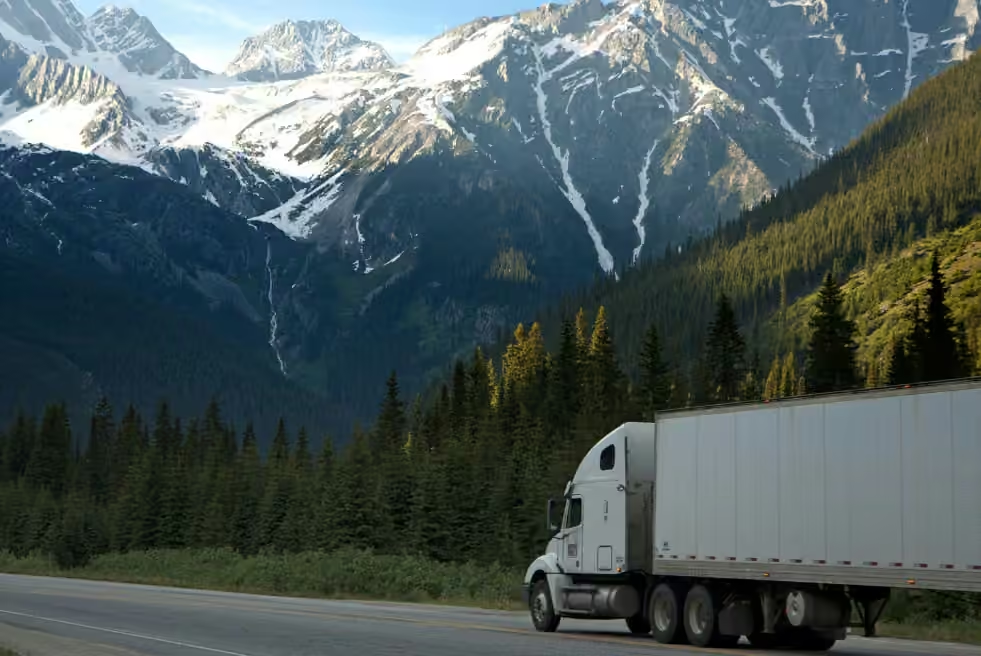
Red 2022 Volvo VNL760 sleeper truck for commercial truck financing

APPROVAL SECURED · FEB

CAD $87,495

2022 Volvo VNL760 sleeper truck
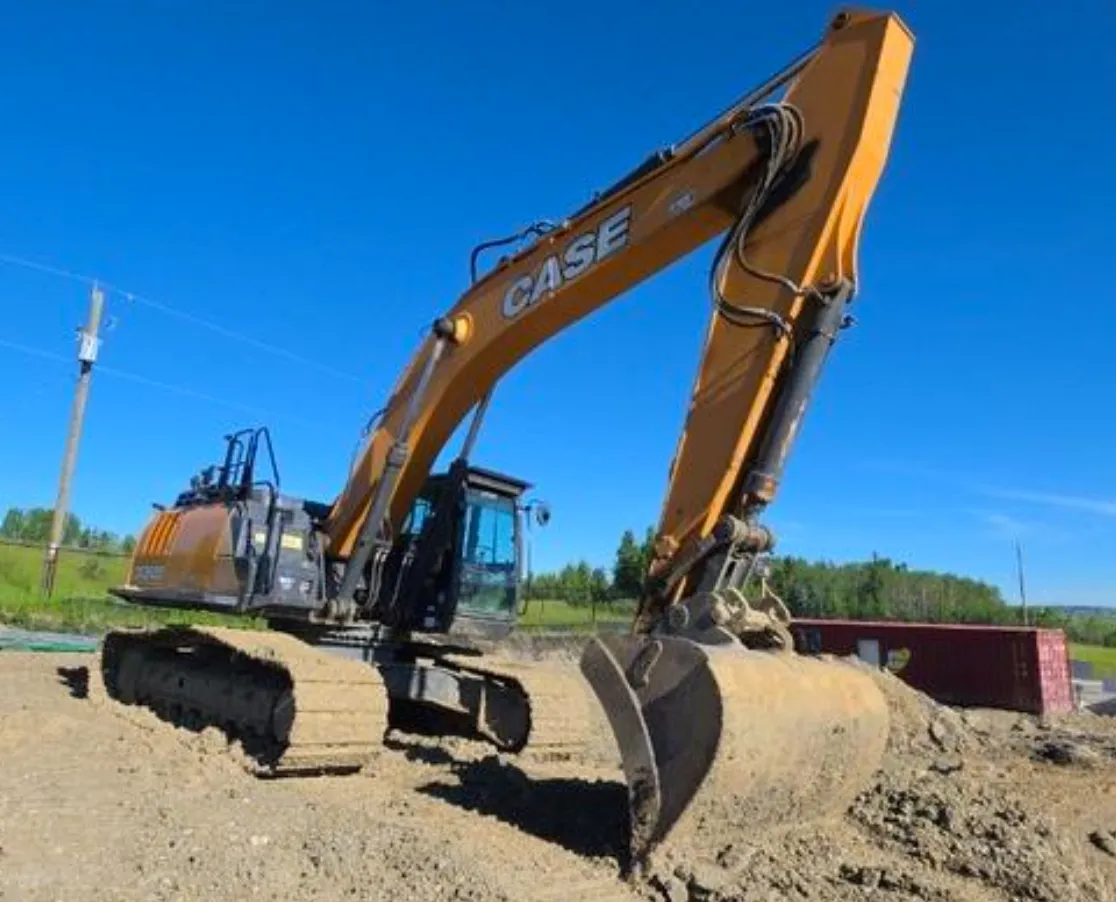
2020 Case CX350 excavator financed for construction equipment in Canada

APPROVED · JUN

CAD $218,000

2020 Case CX350 excavator with attachments
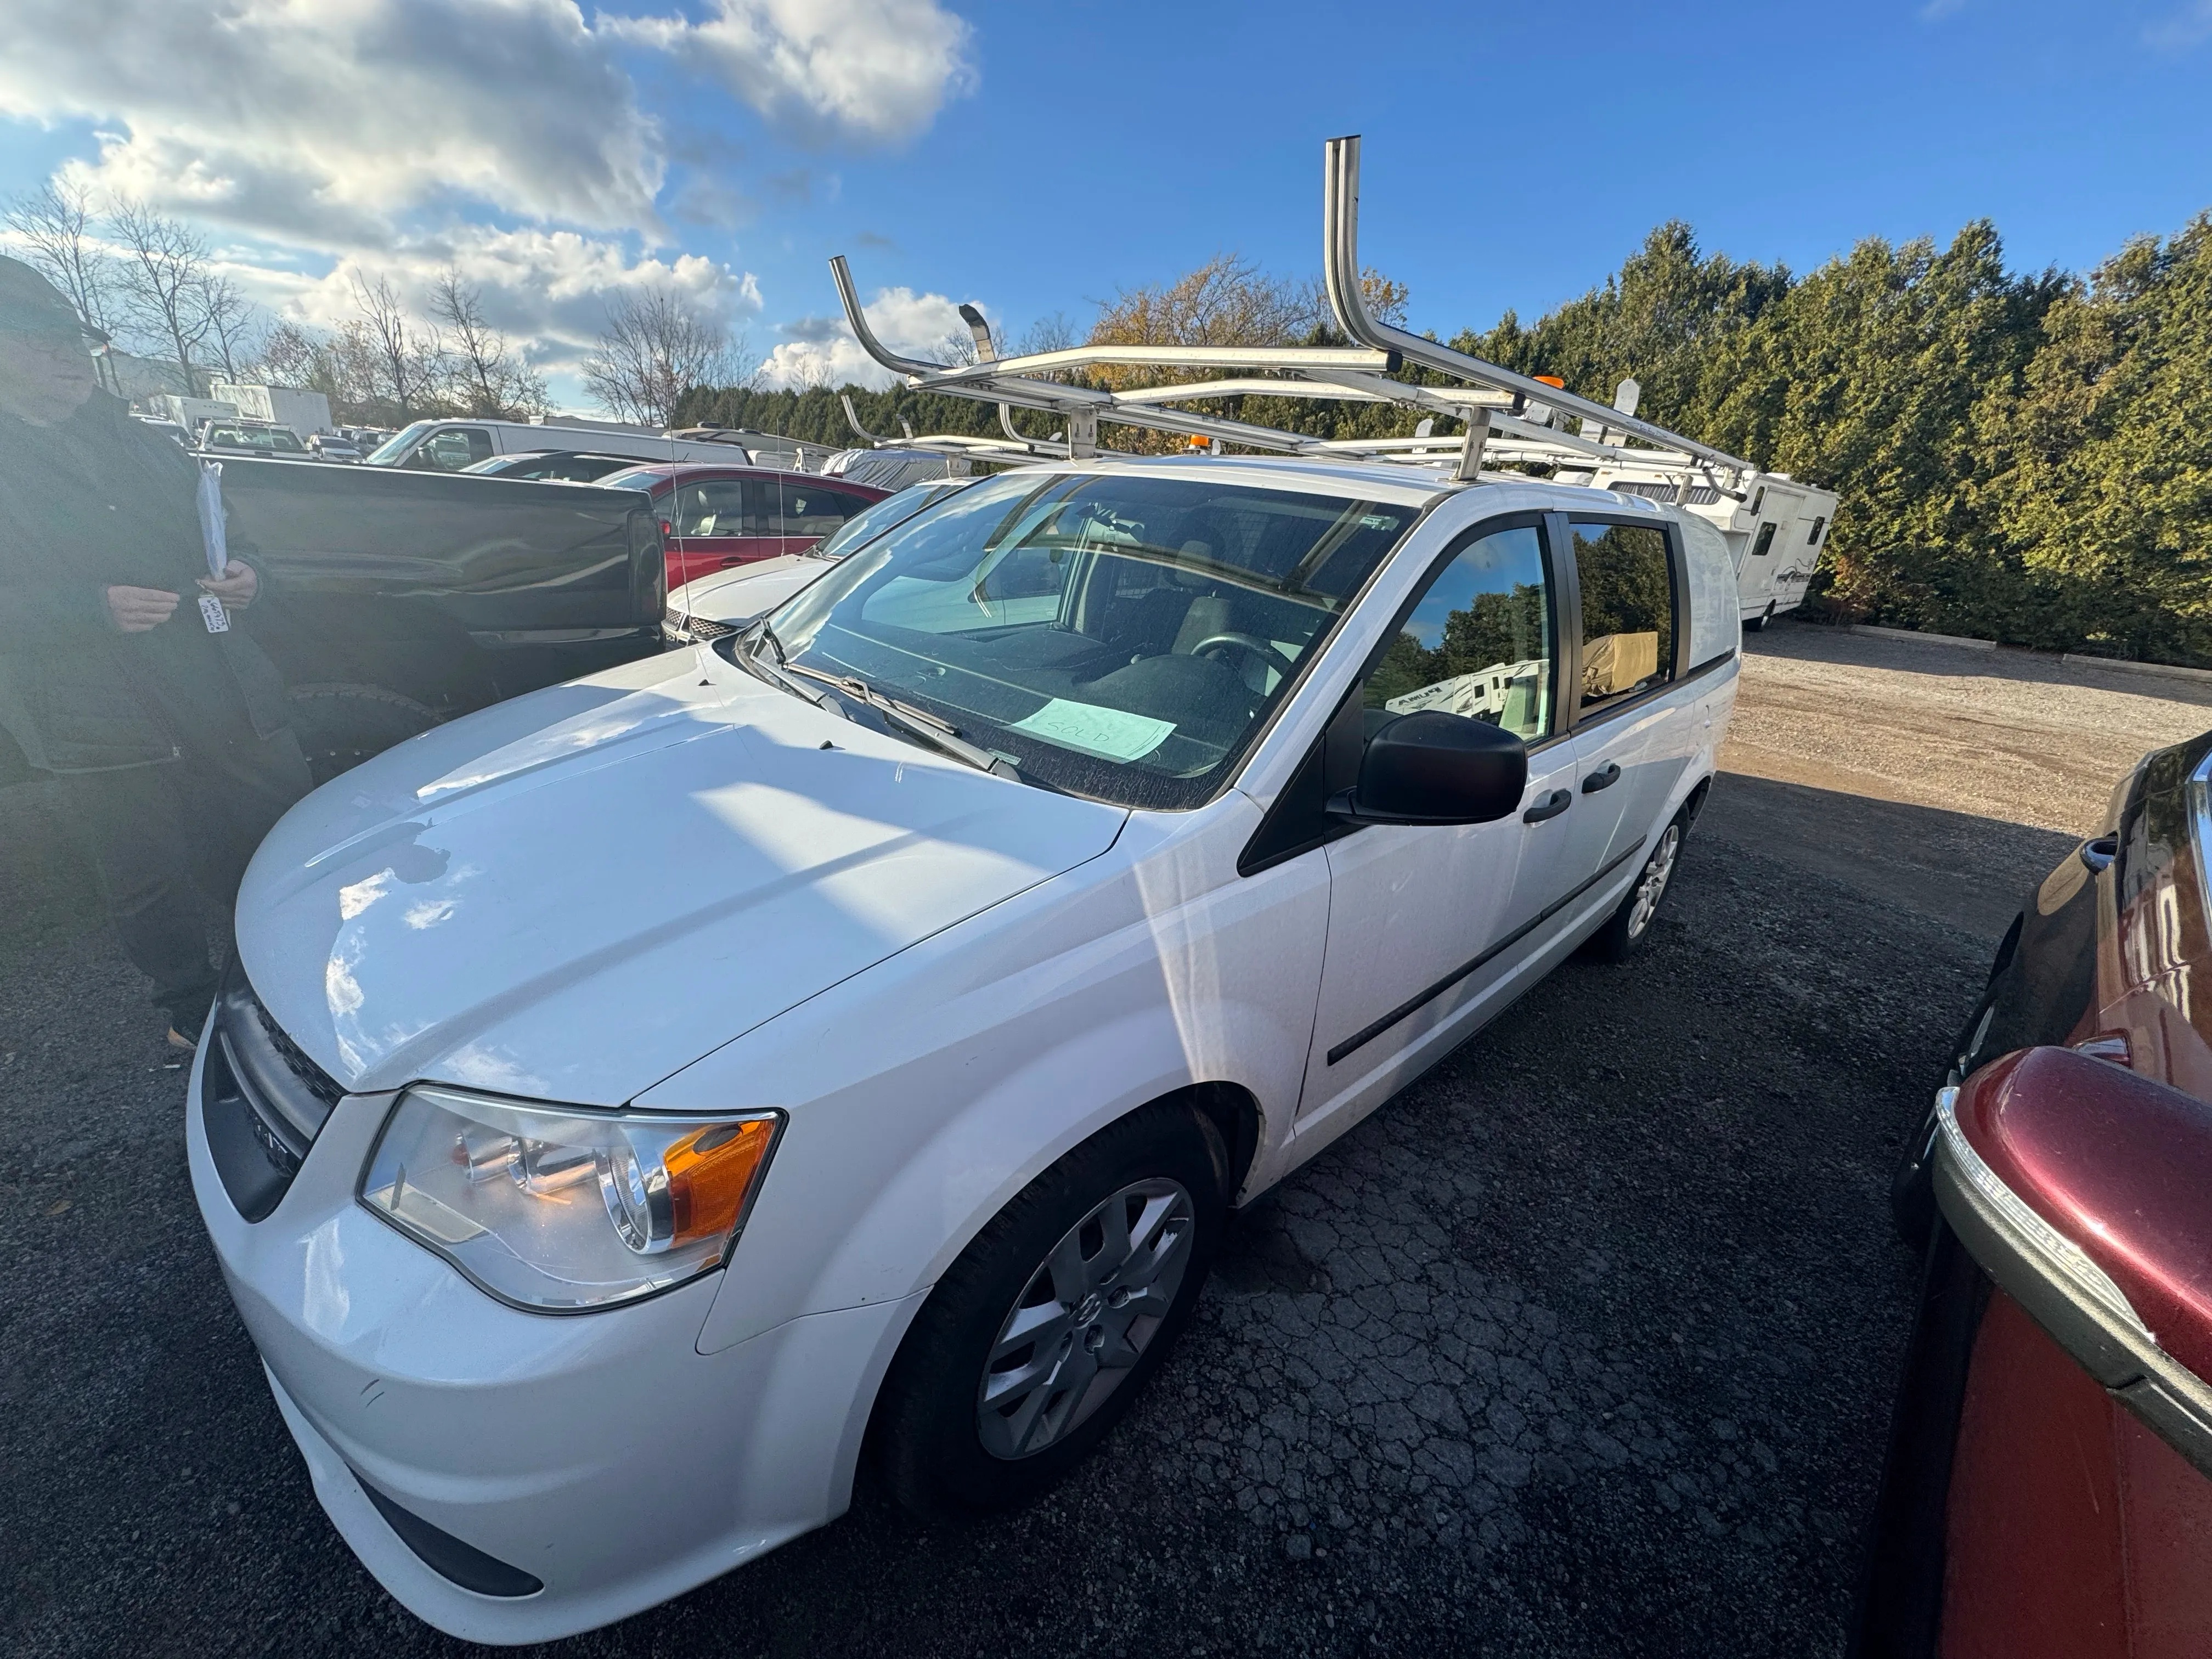
2015 Ram cargo van with roof rack for commercial vehicle financing

APPROVAL SECURED · OCT

CAD $6,200

2015 Ram cargo van
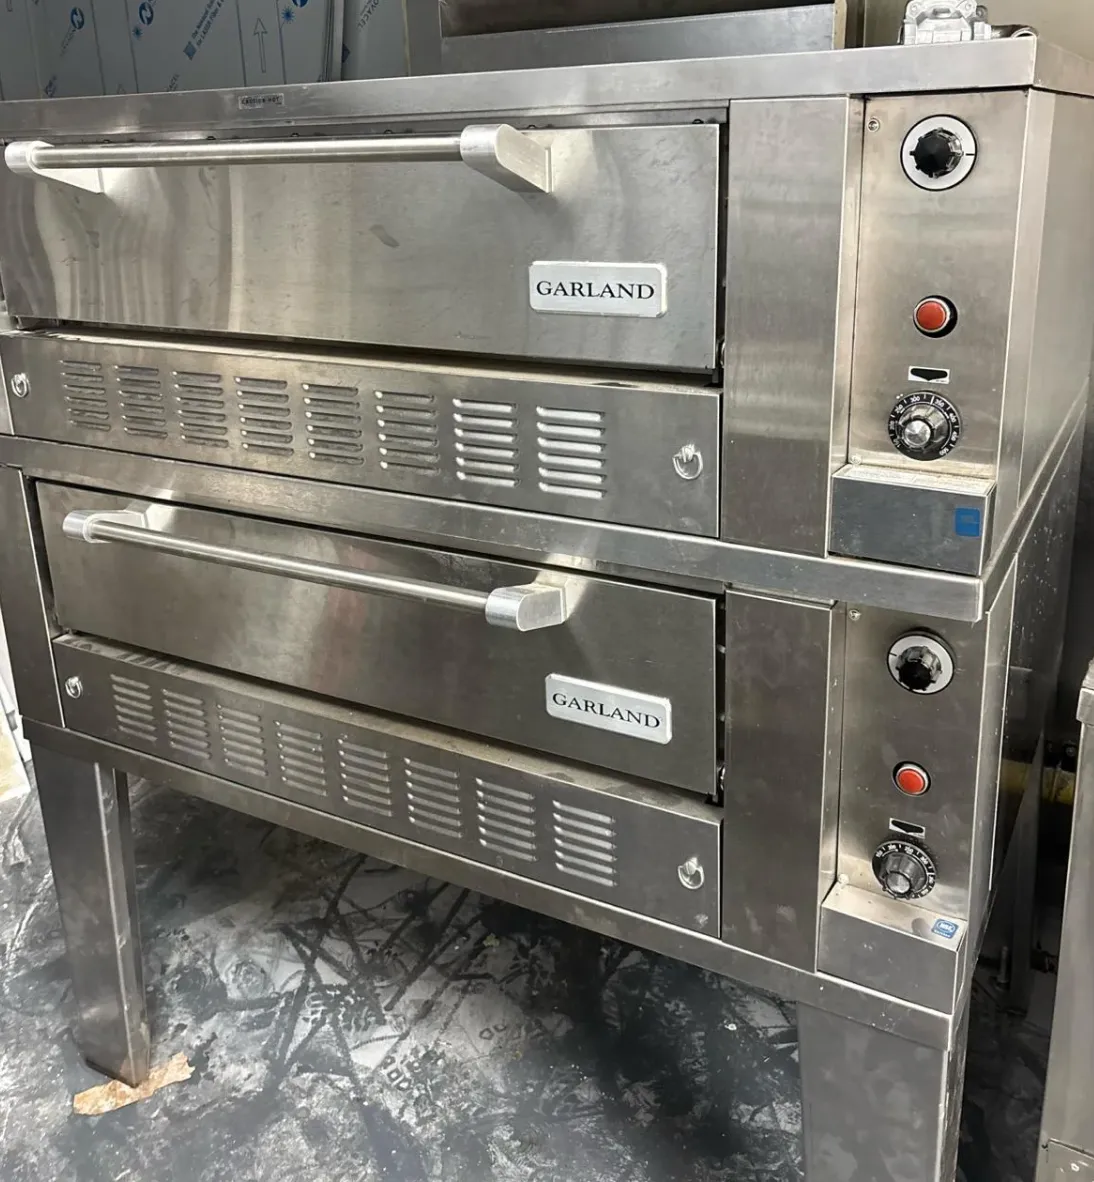
2022 Garland double-deck commercial oven for restaurant equipment financing

APPROVAL SECURED · OCT

CAD $25,350

2022 Garland double-deck oven
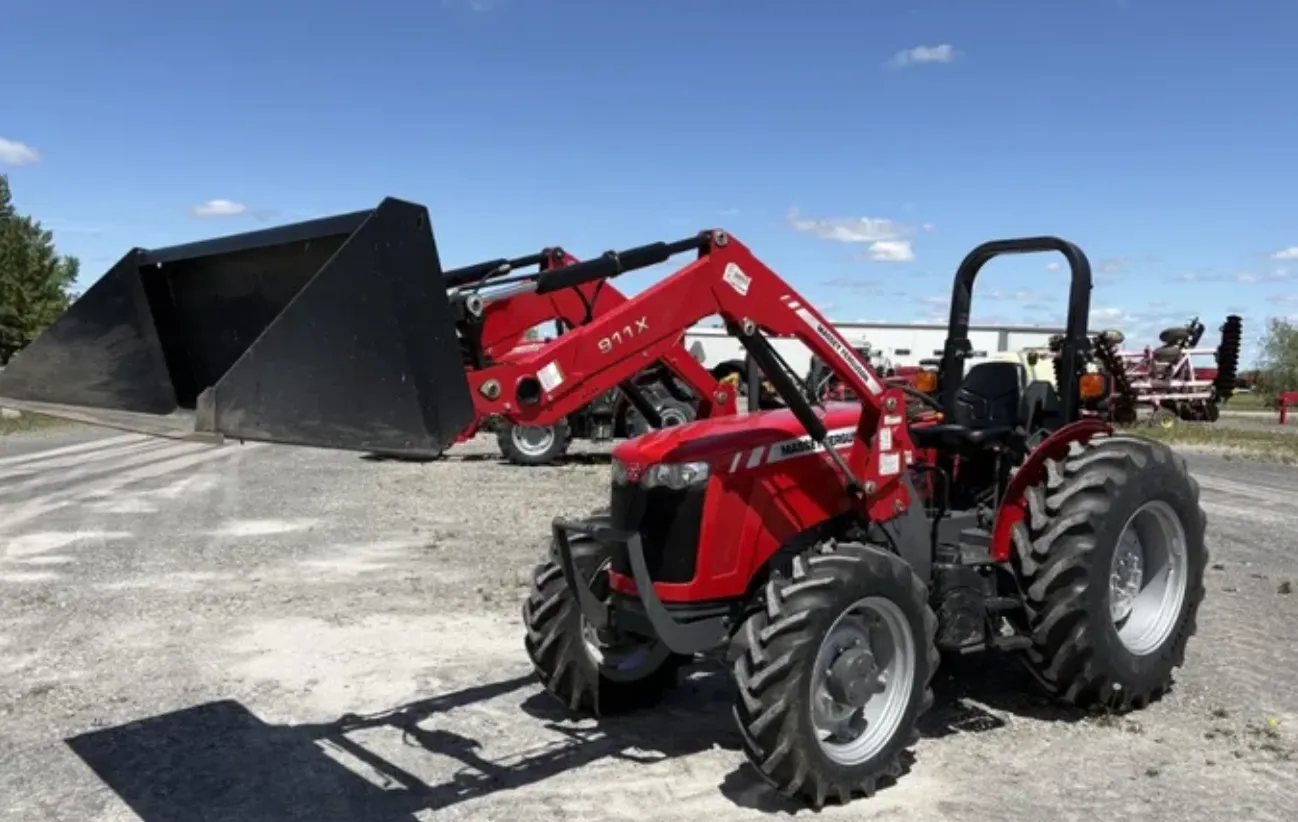
2022 Massey Ferguson 2407H tractor with front loader for agricultural equipment financing

APPROVAL SECURED · FEB

CAD $30,000

2022 Massey Ferguson 2407H tractor
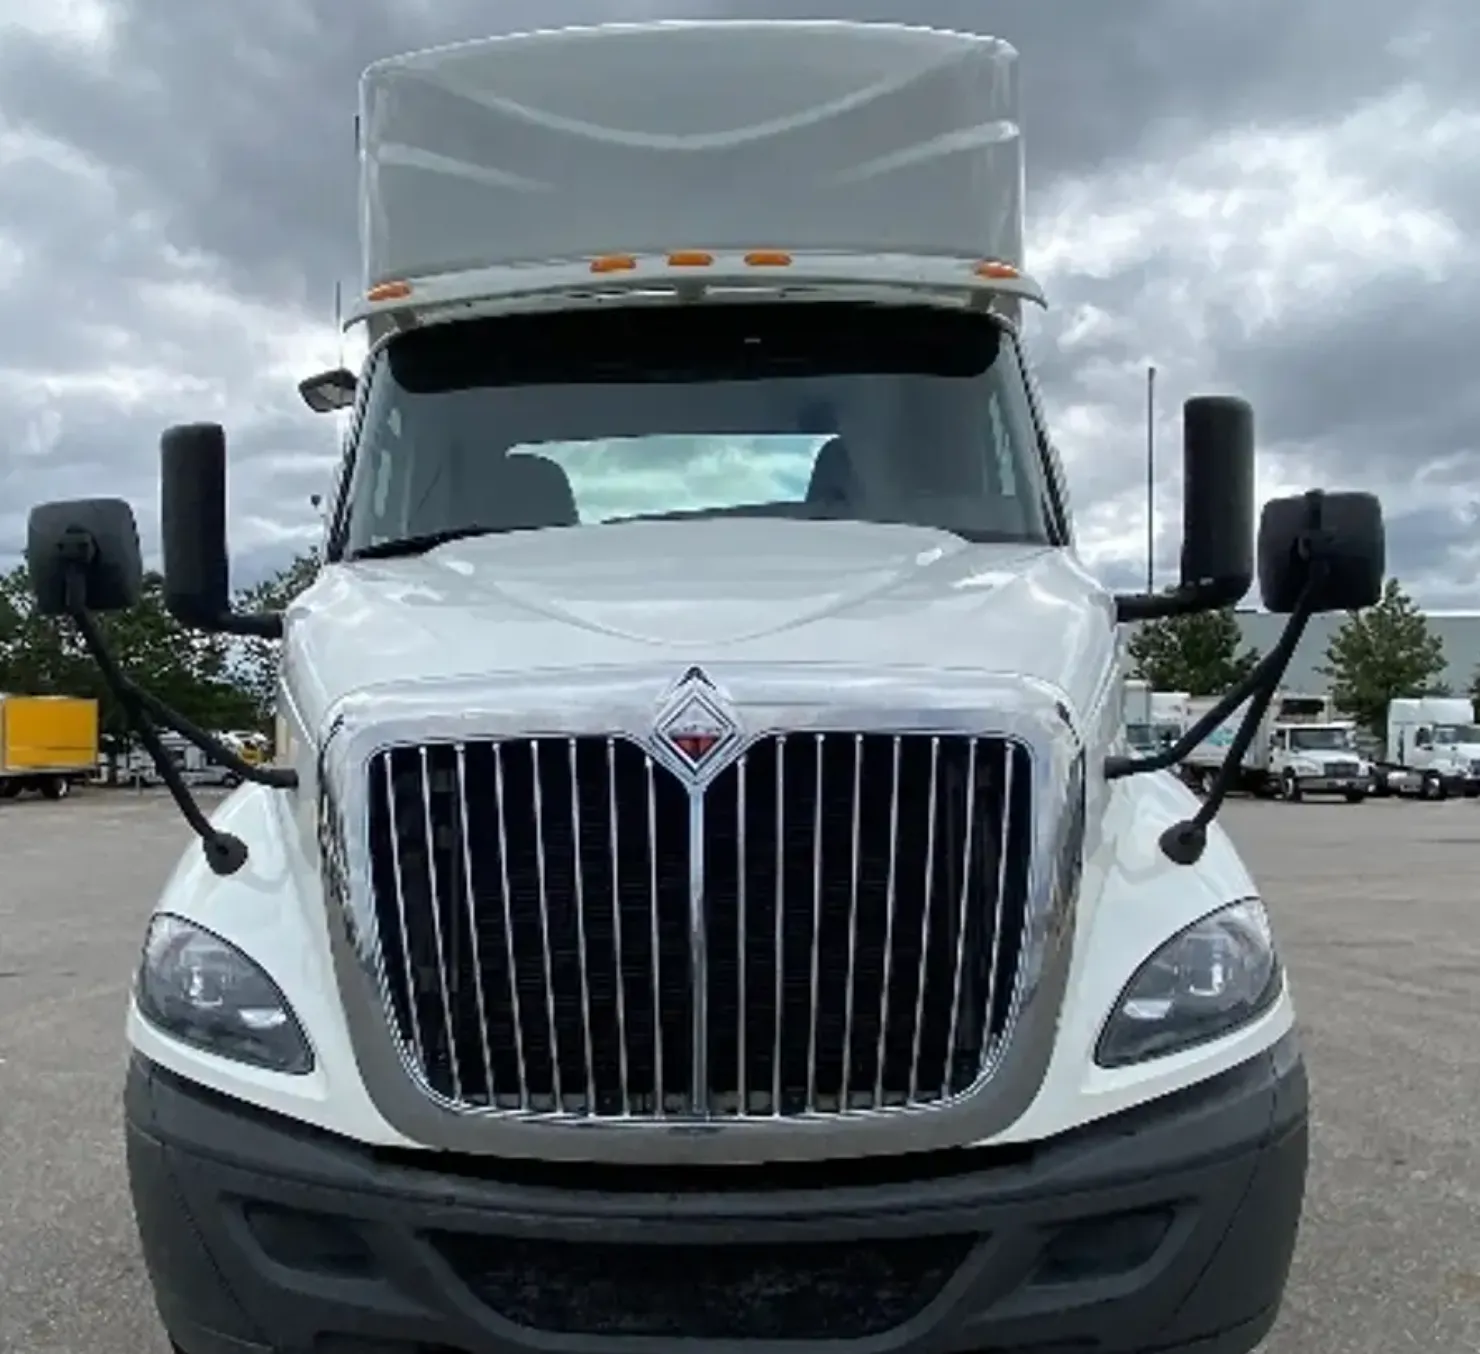
2020 International RH613 day cab truck financed for commercial transportation

APPROVAL SECURED · MAR

CAD $36,299

2020 International RH613 day cab
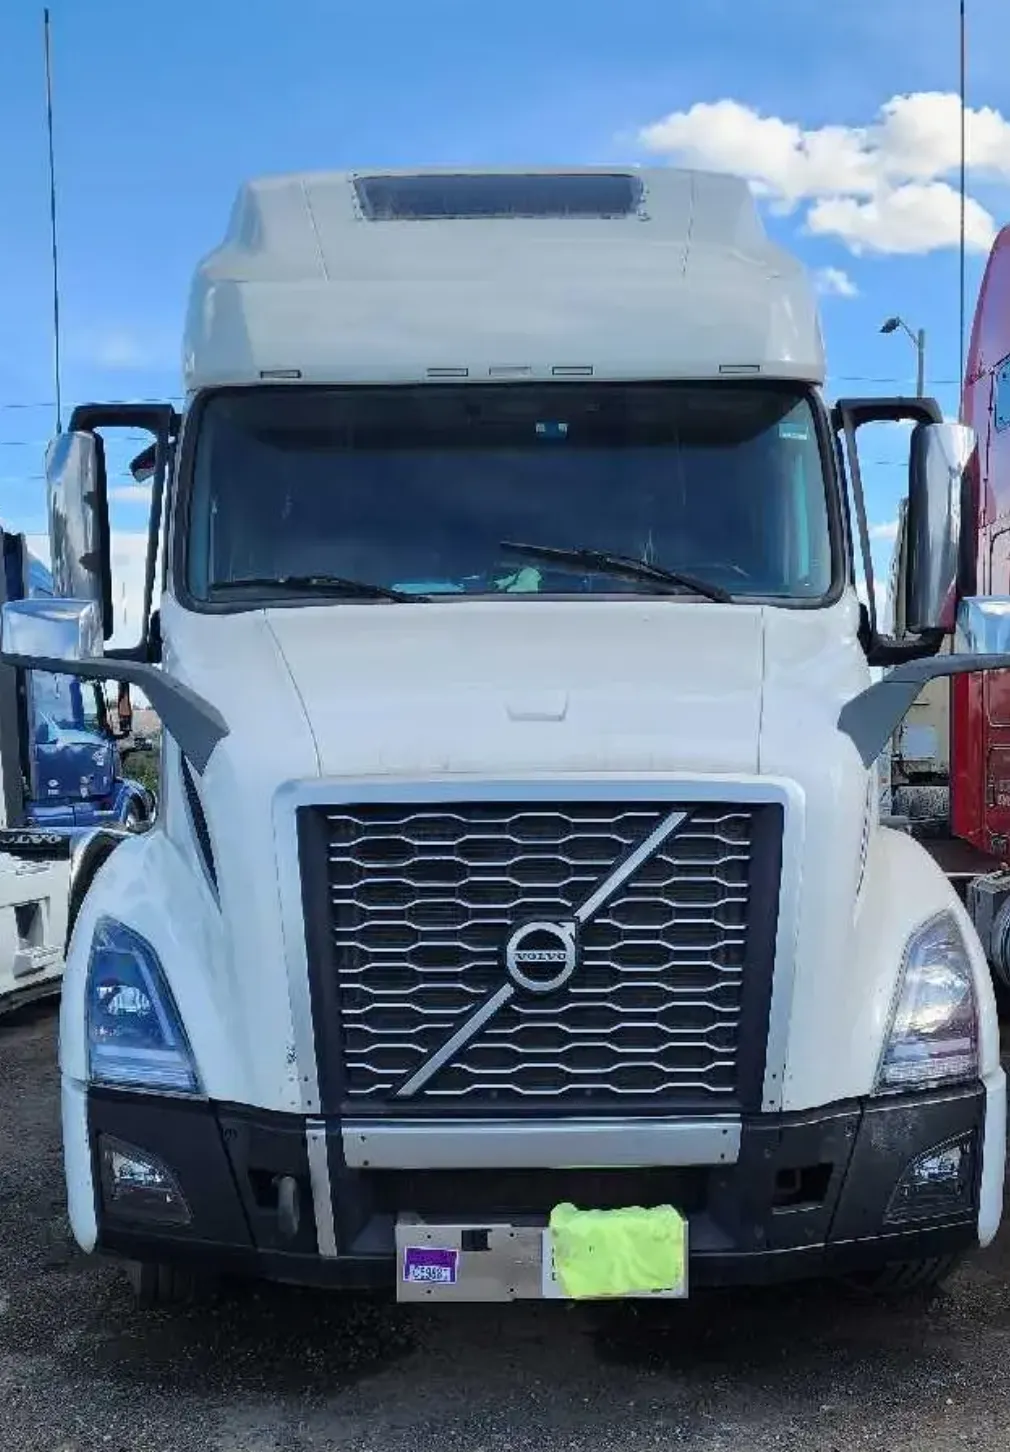
2020 Volvo VNL760 commercial truck financed for transportation

APPROVAL SECURED · NOV

CAD $65,499

2020 Volvo VNL760 commercial truck
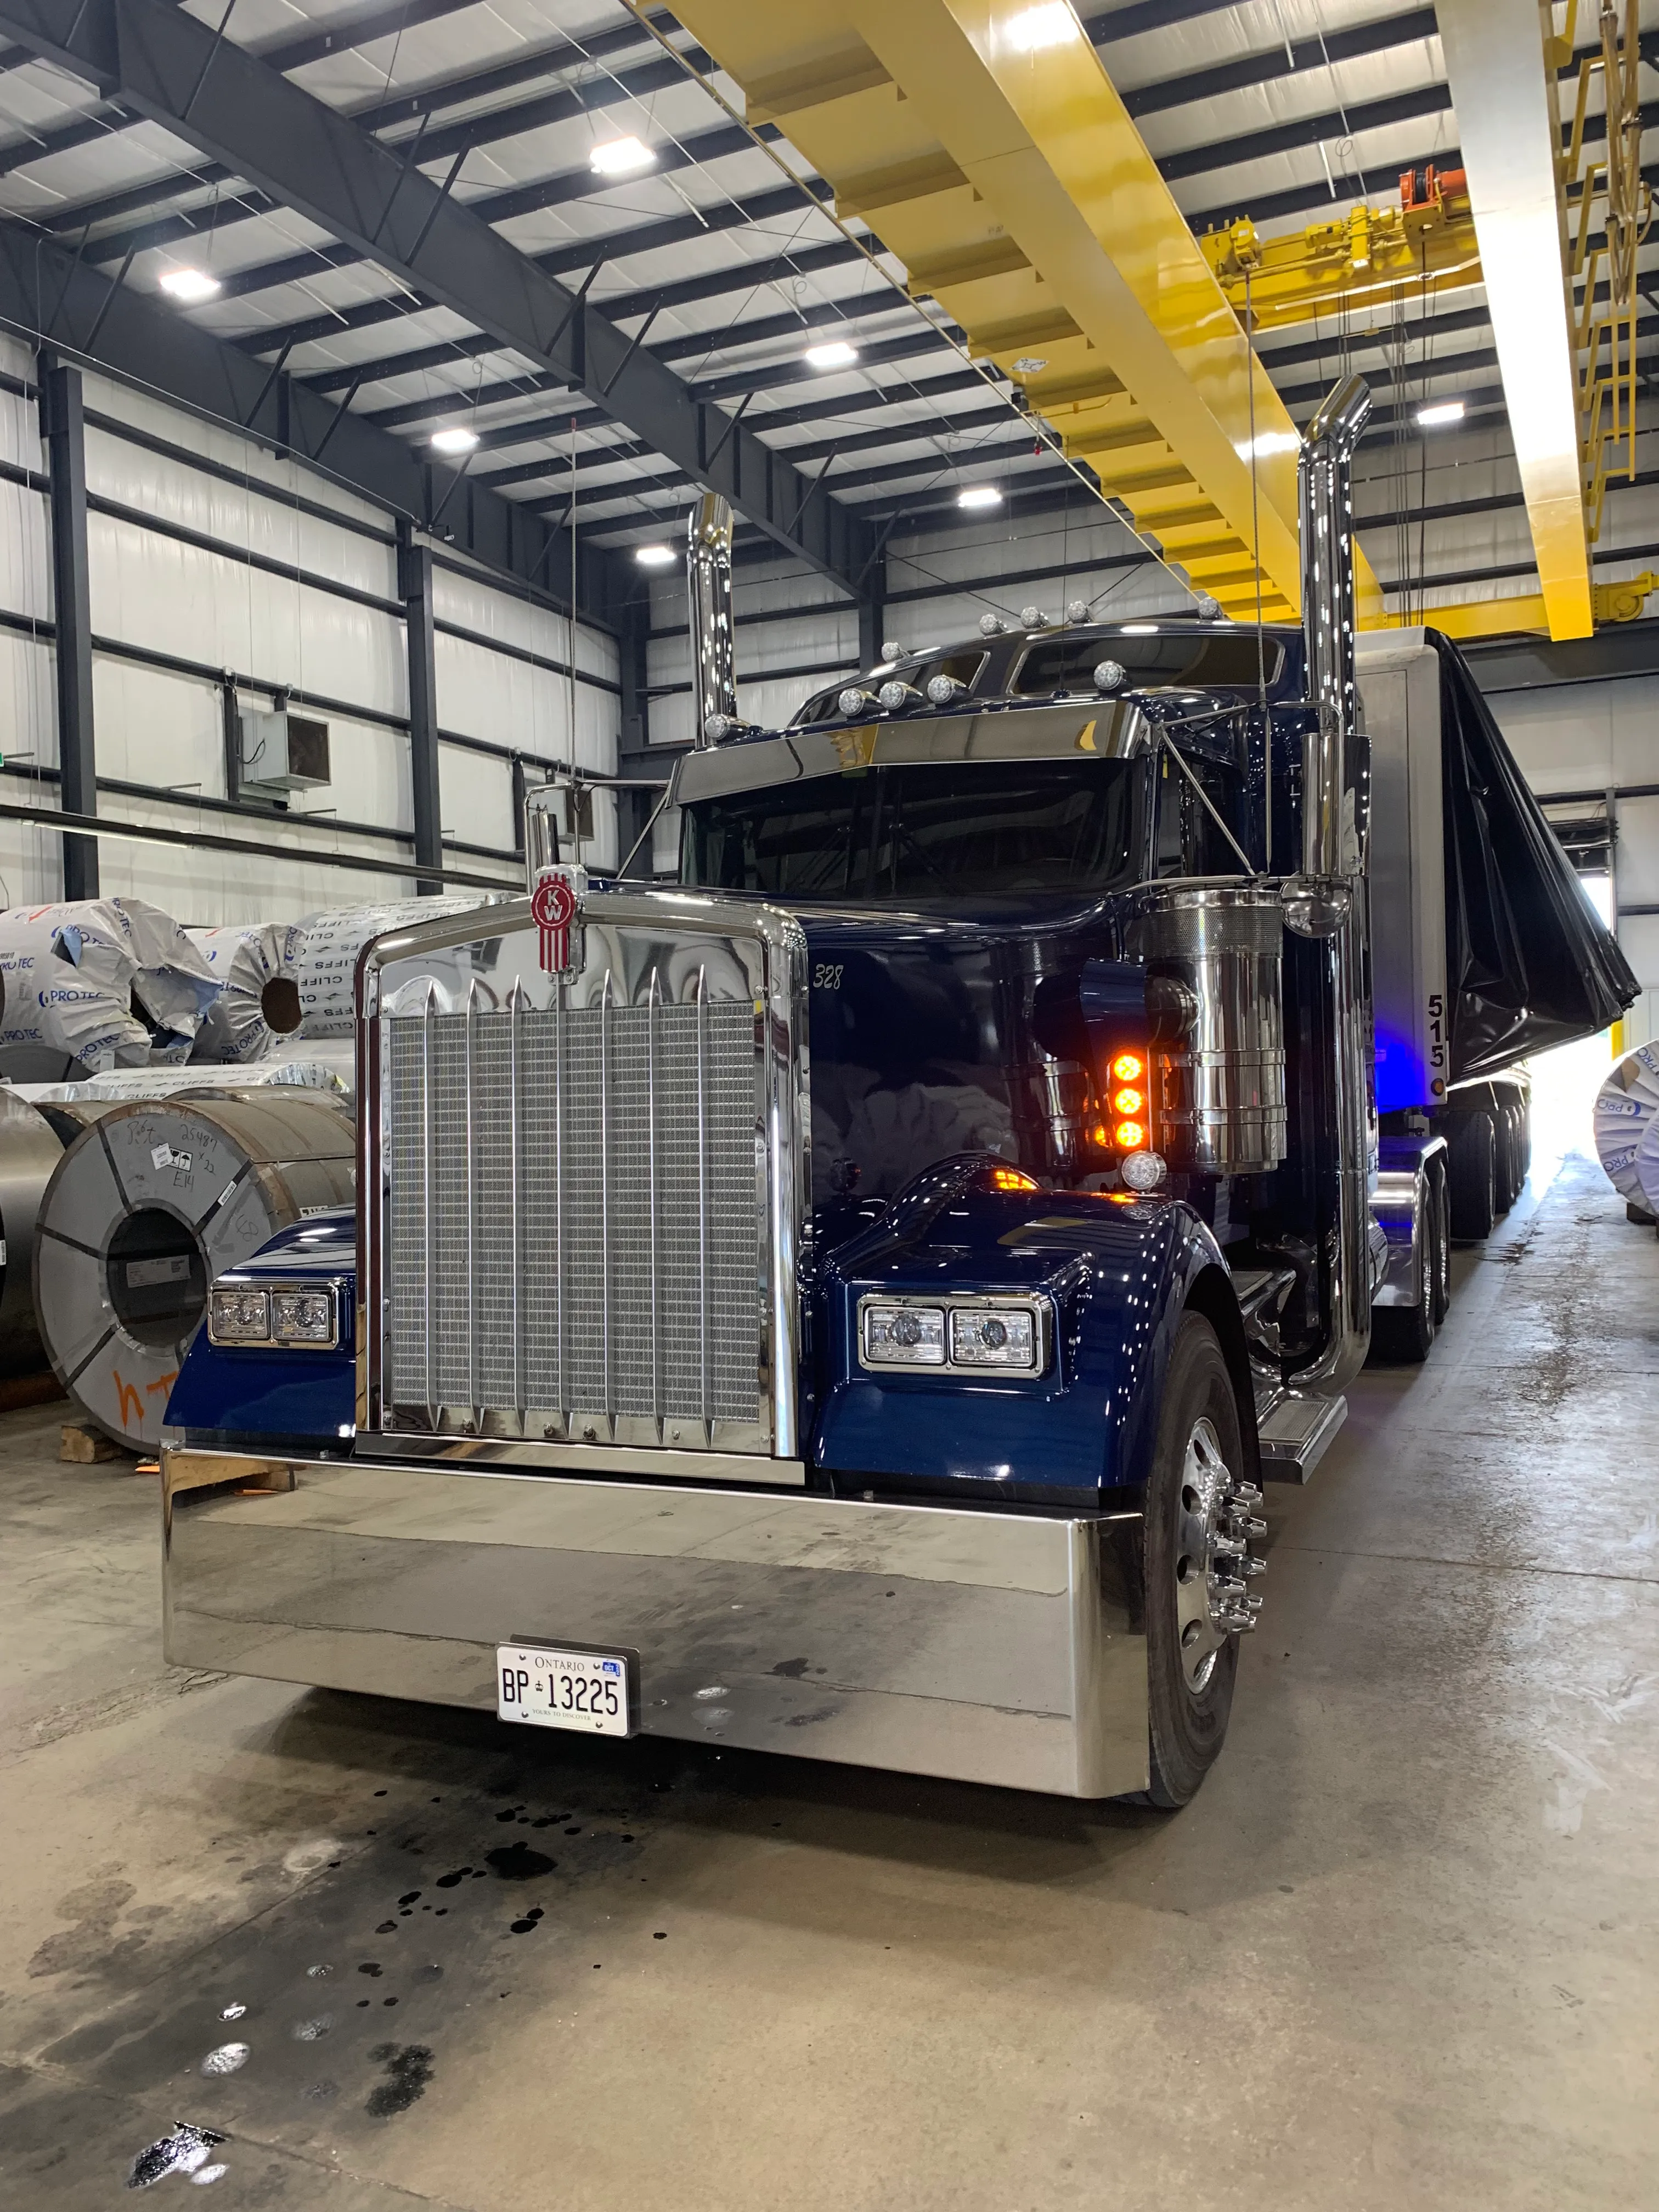
2022 Kenworth W900B commercial truck financed in Canada

FUNDED · DEC

CAD $150,000

2022 Kenworth W900B truck
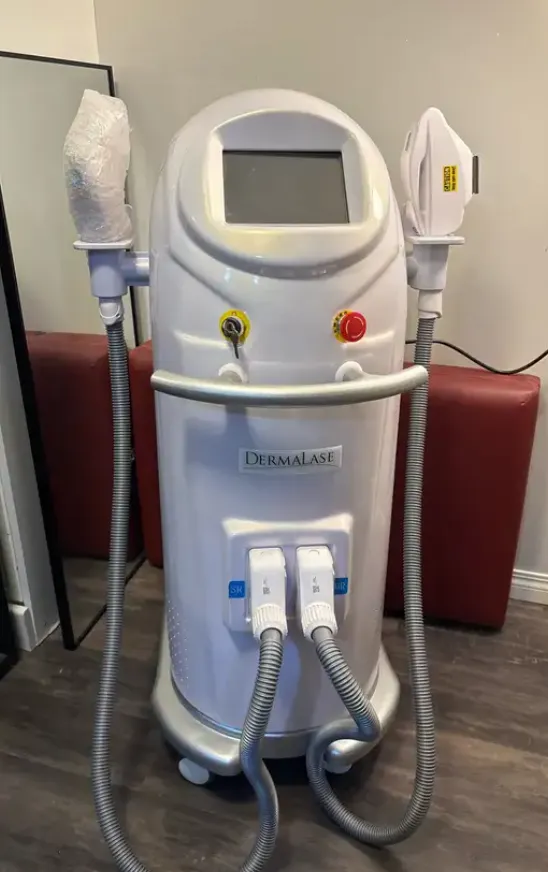
Dermalase laser hair-removal equipment financed for a beauty business

APPROVAL SECURED · FEB

CAD $25,000

Laser hair-removal equipment
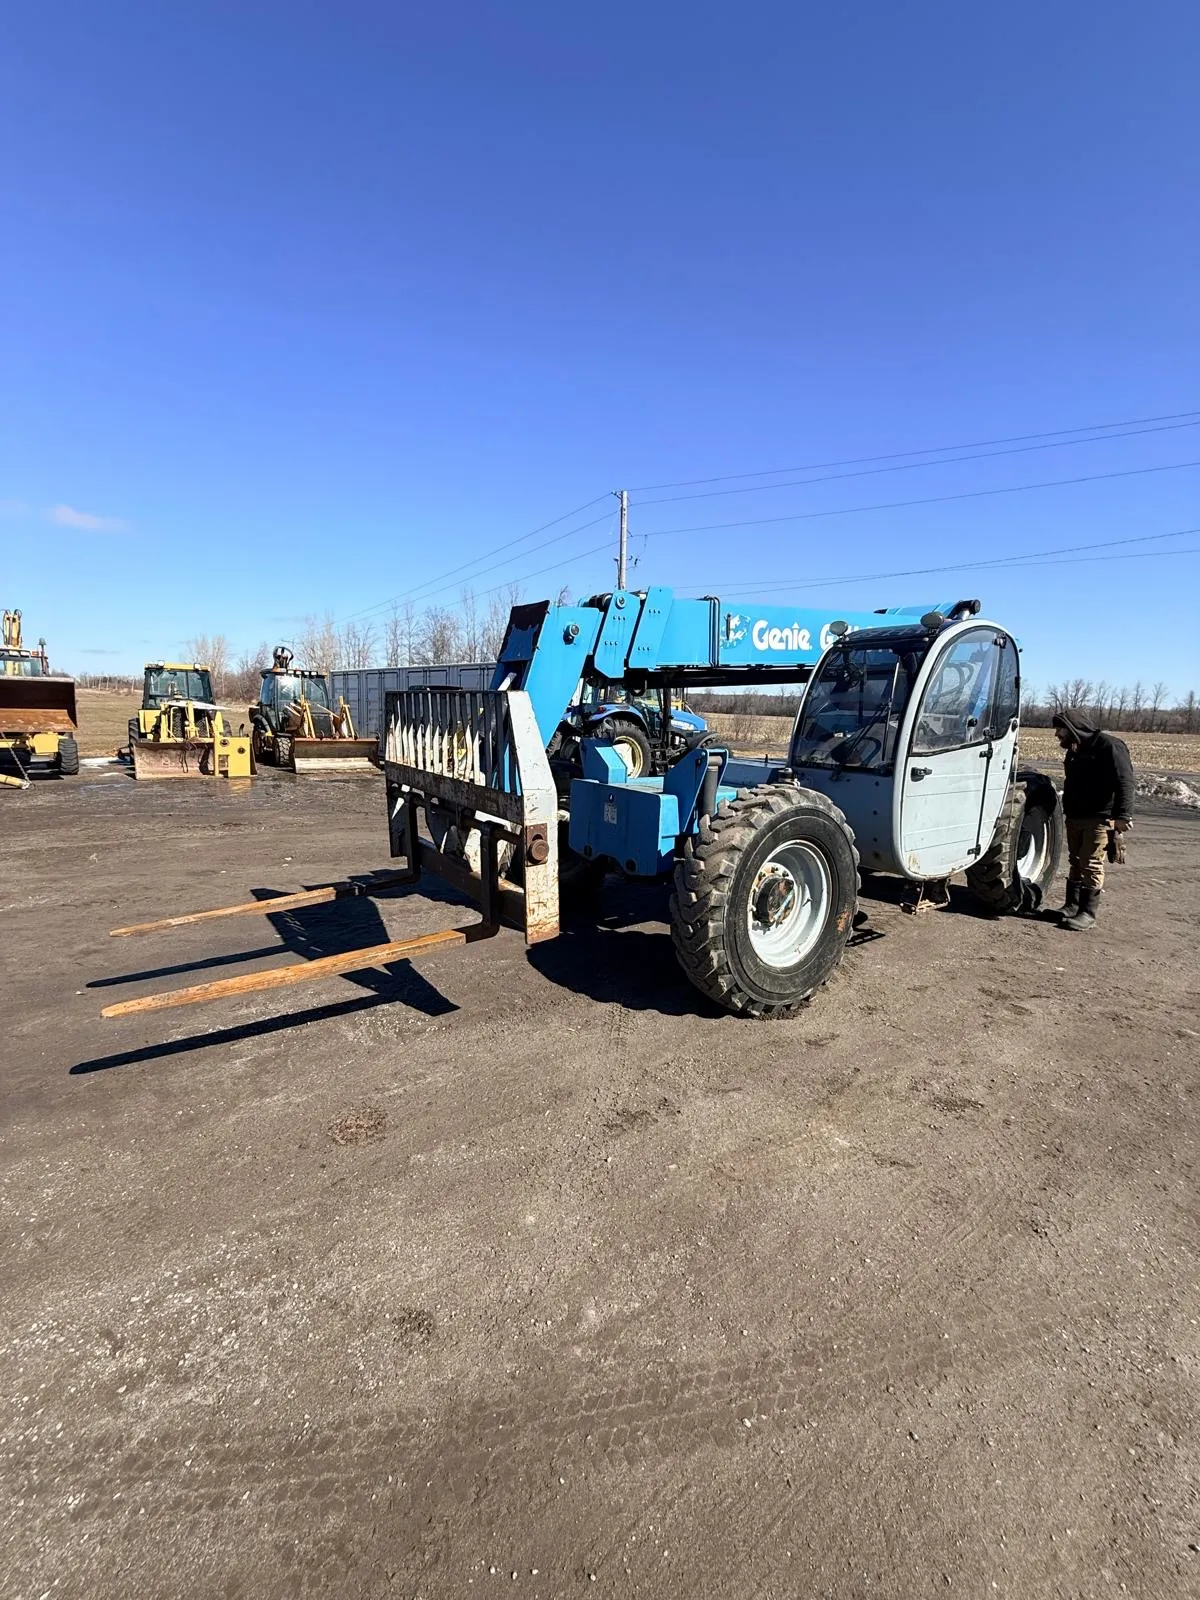
2011 Genie GTH844 telehandler financed for construction work in Canada

APPROVAL SECURED · MAR

CAD $39,000

2011 Genie GTH844 telehandler
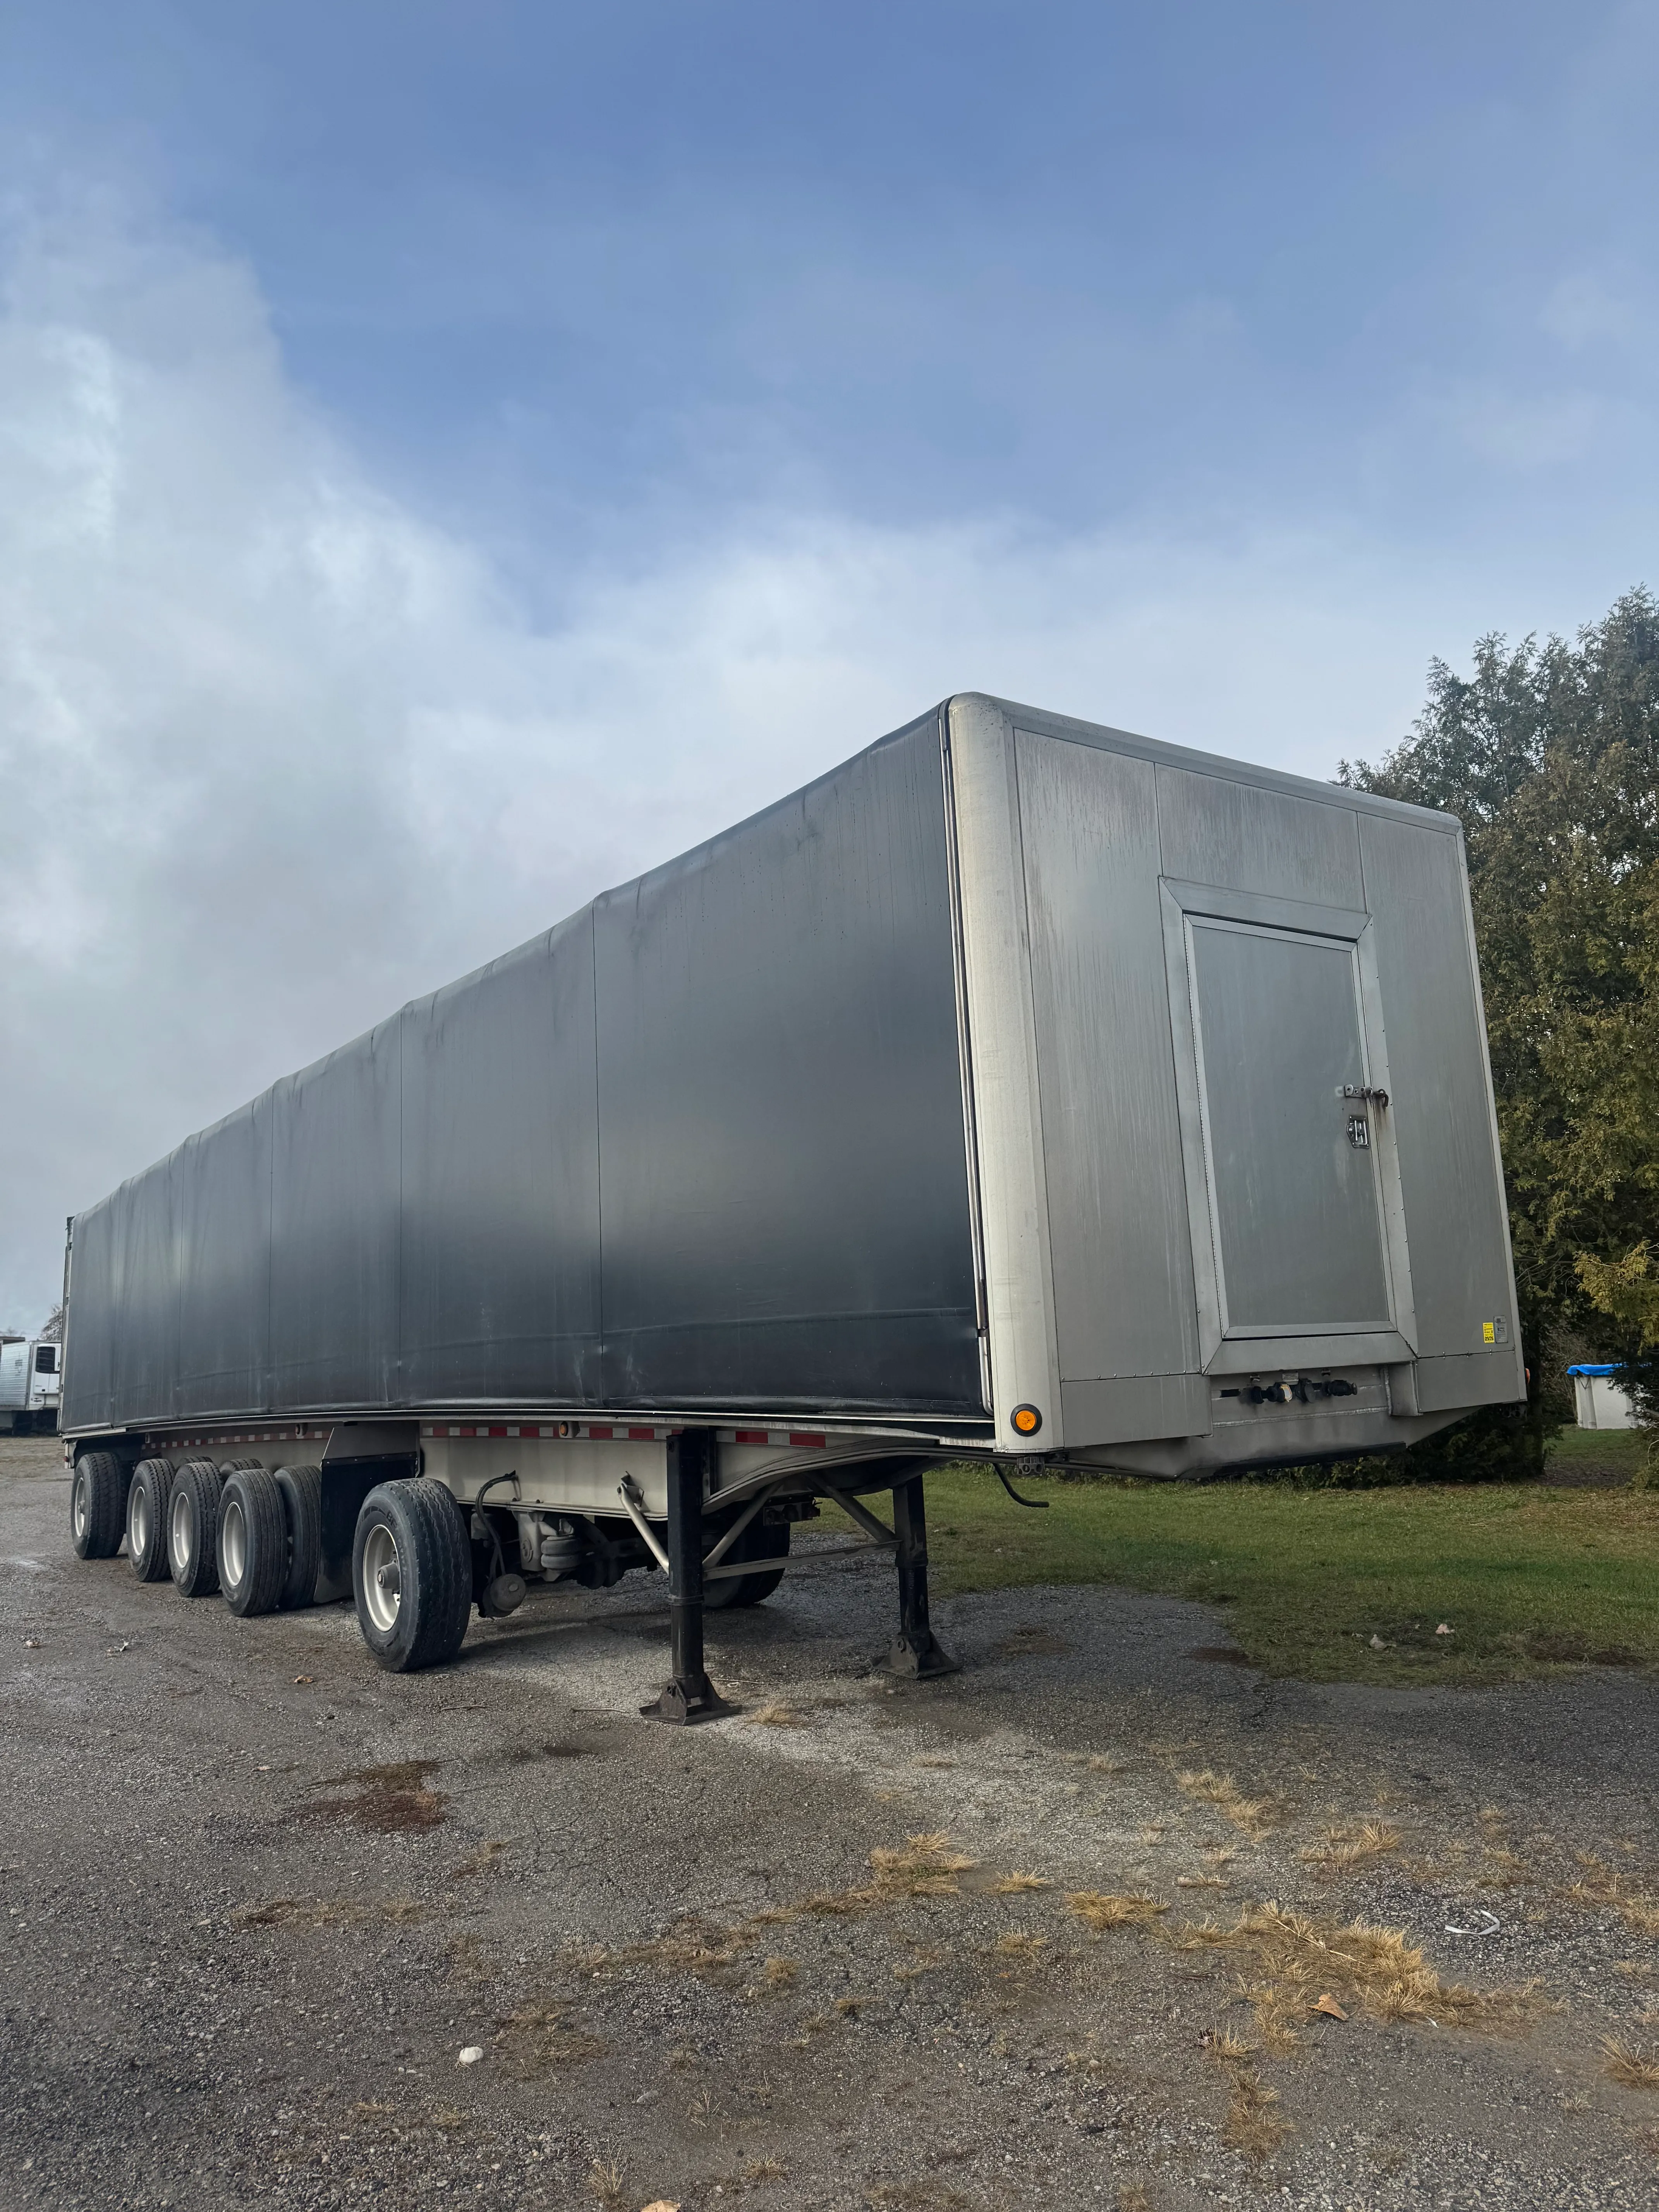
Manac flatbed trailer with Verduyn tarp system financed for commercial transport in Canada

FUNDED · JAN

CAD $132,095

2027 Manac 50-foot flatbed trailer and tarp system
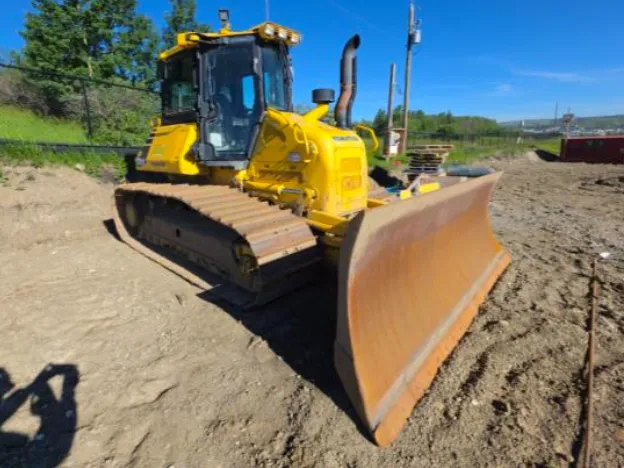
2021 Komatsu D51 bulldozer approved for construction equipment financing

APPROVED · JUN

CAD $104,650

2021 Komatsu D51 bulldozer
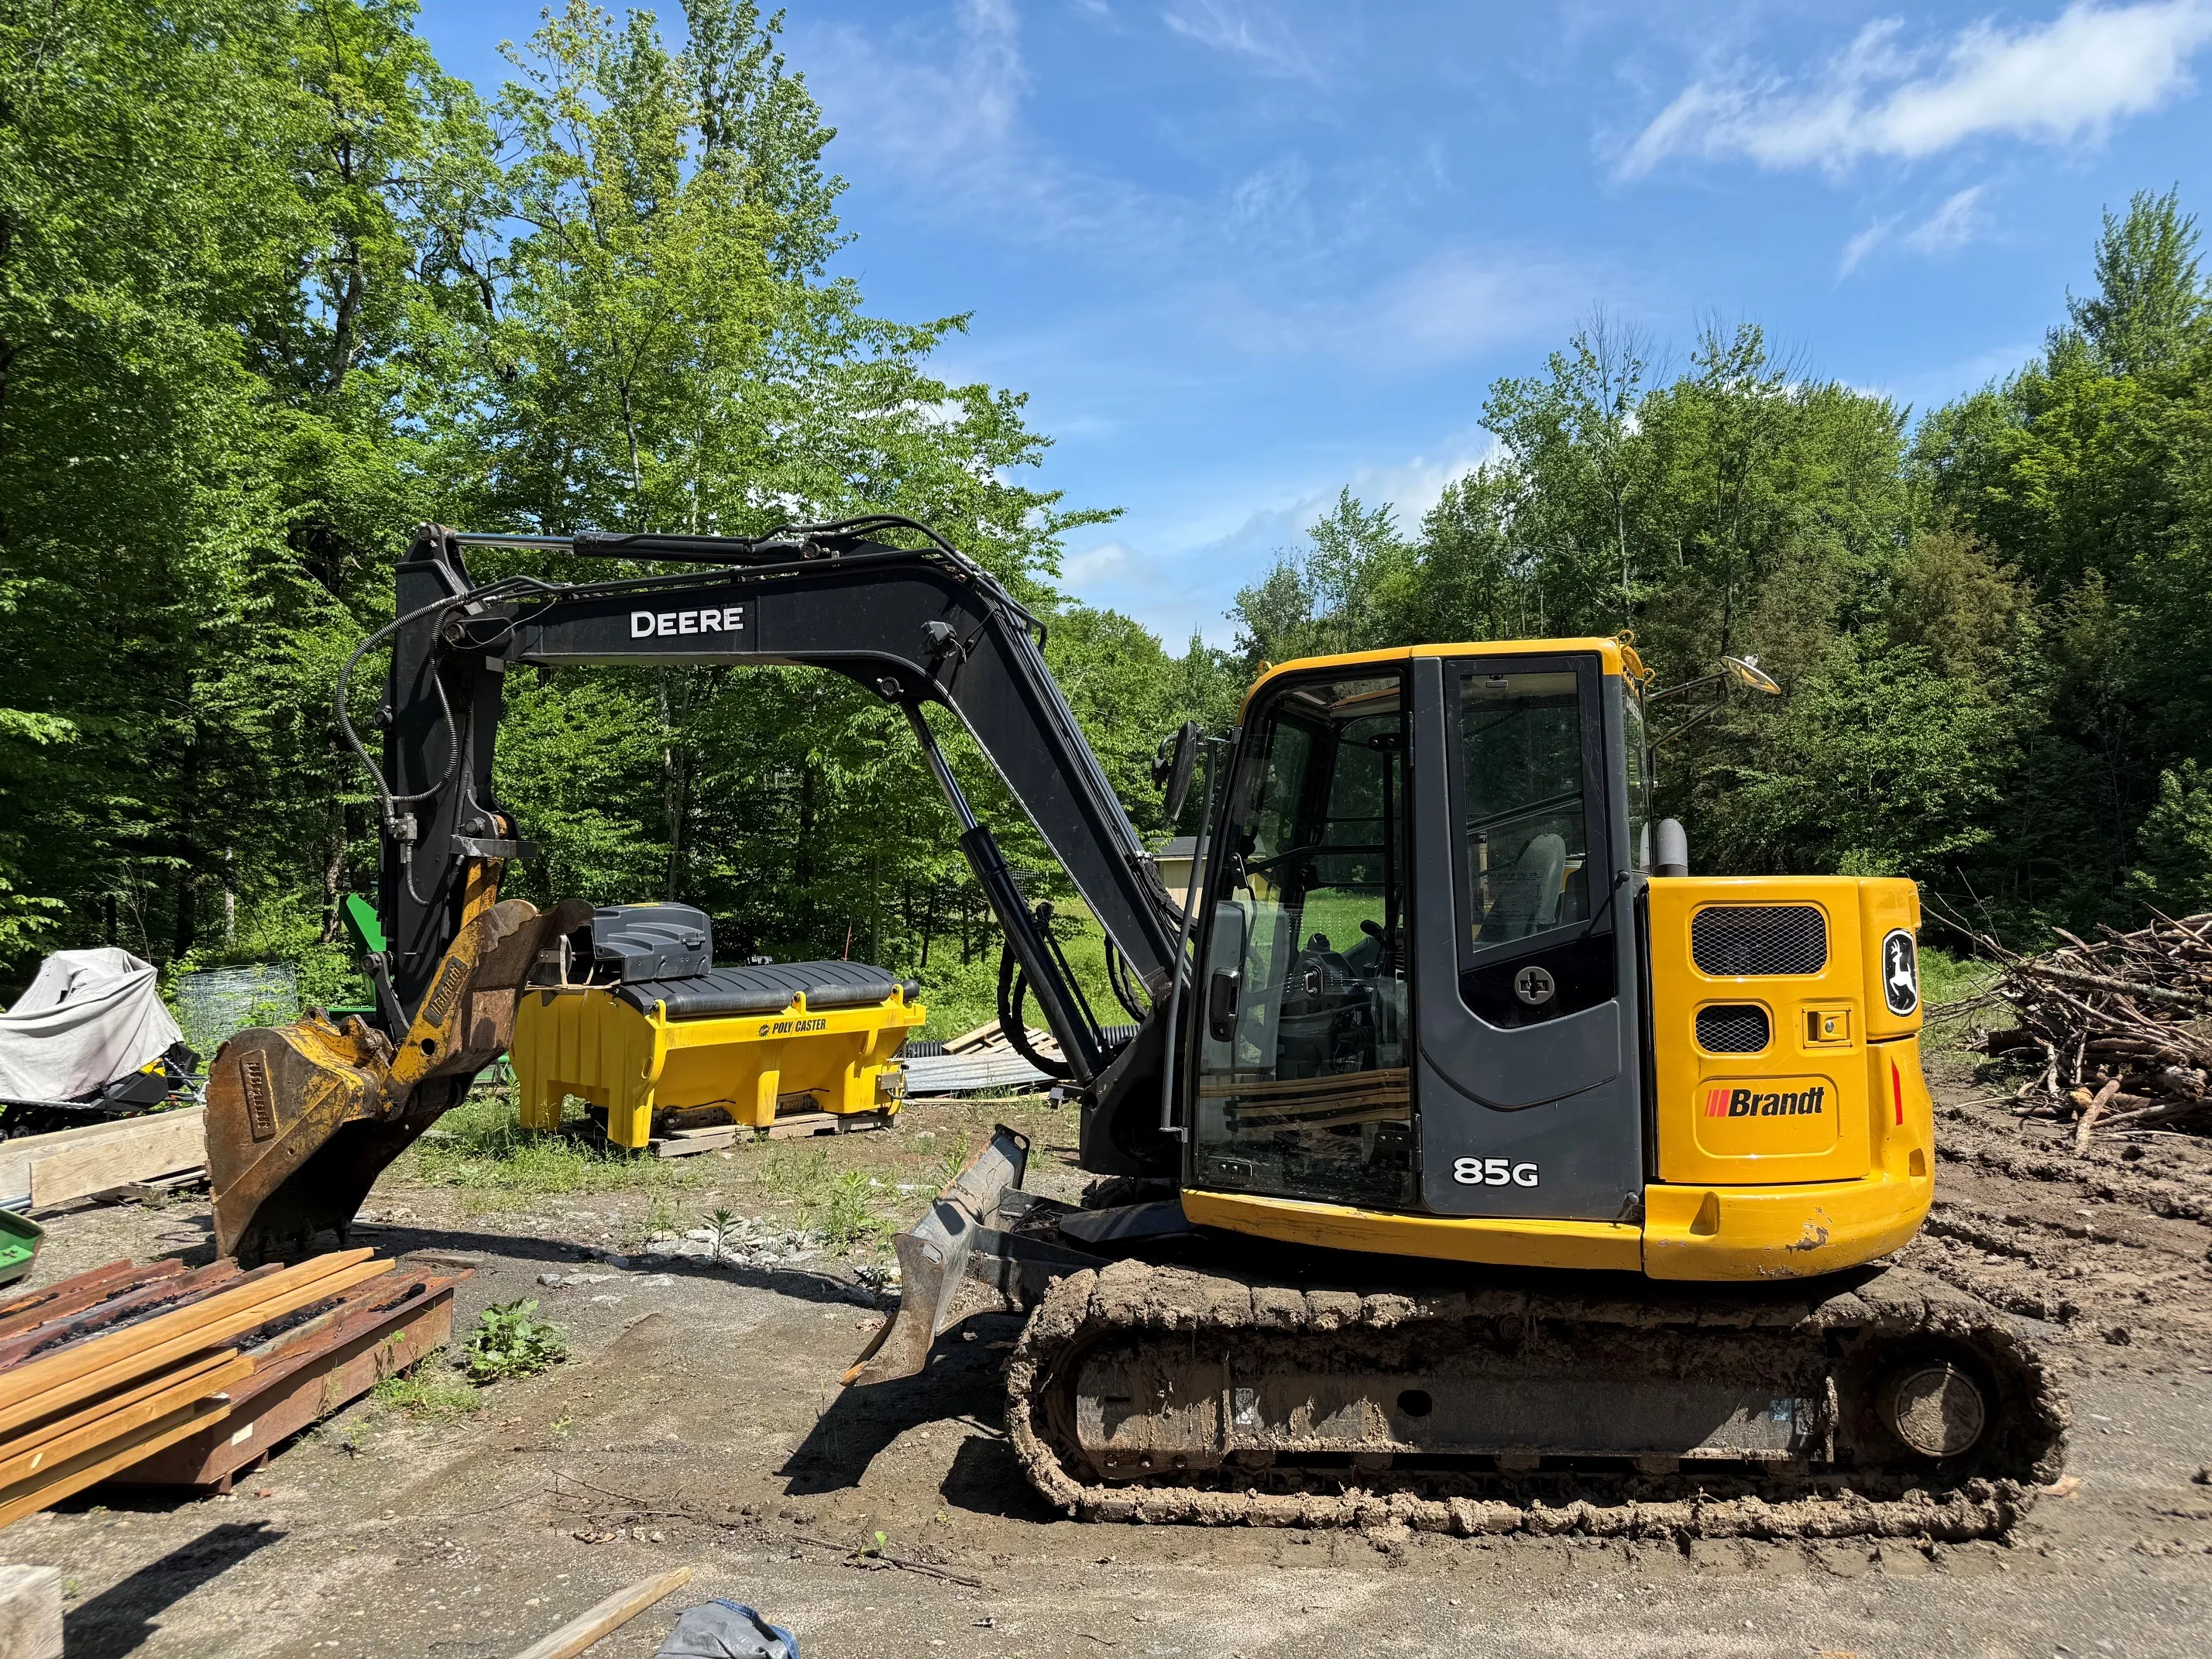
2021 John Deere 85G compact excavator financed for construction equipment

FUNDED · JUL

CAD $52,172.10

2021 John Deere 85G excavator
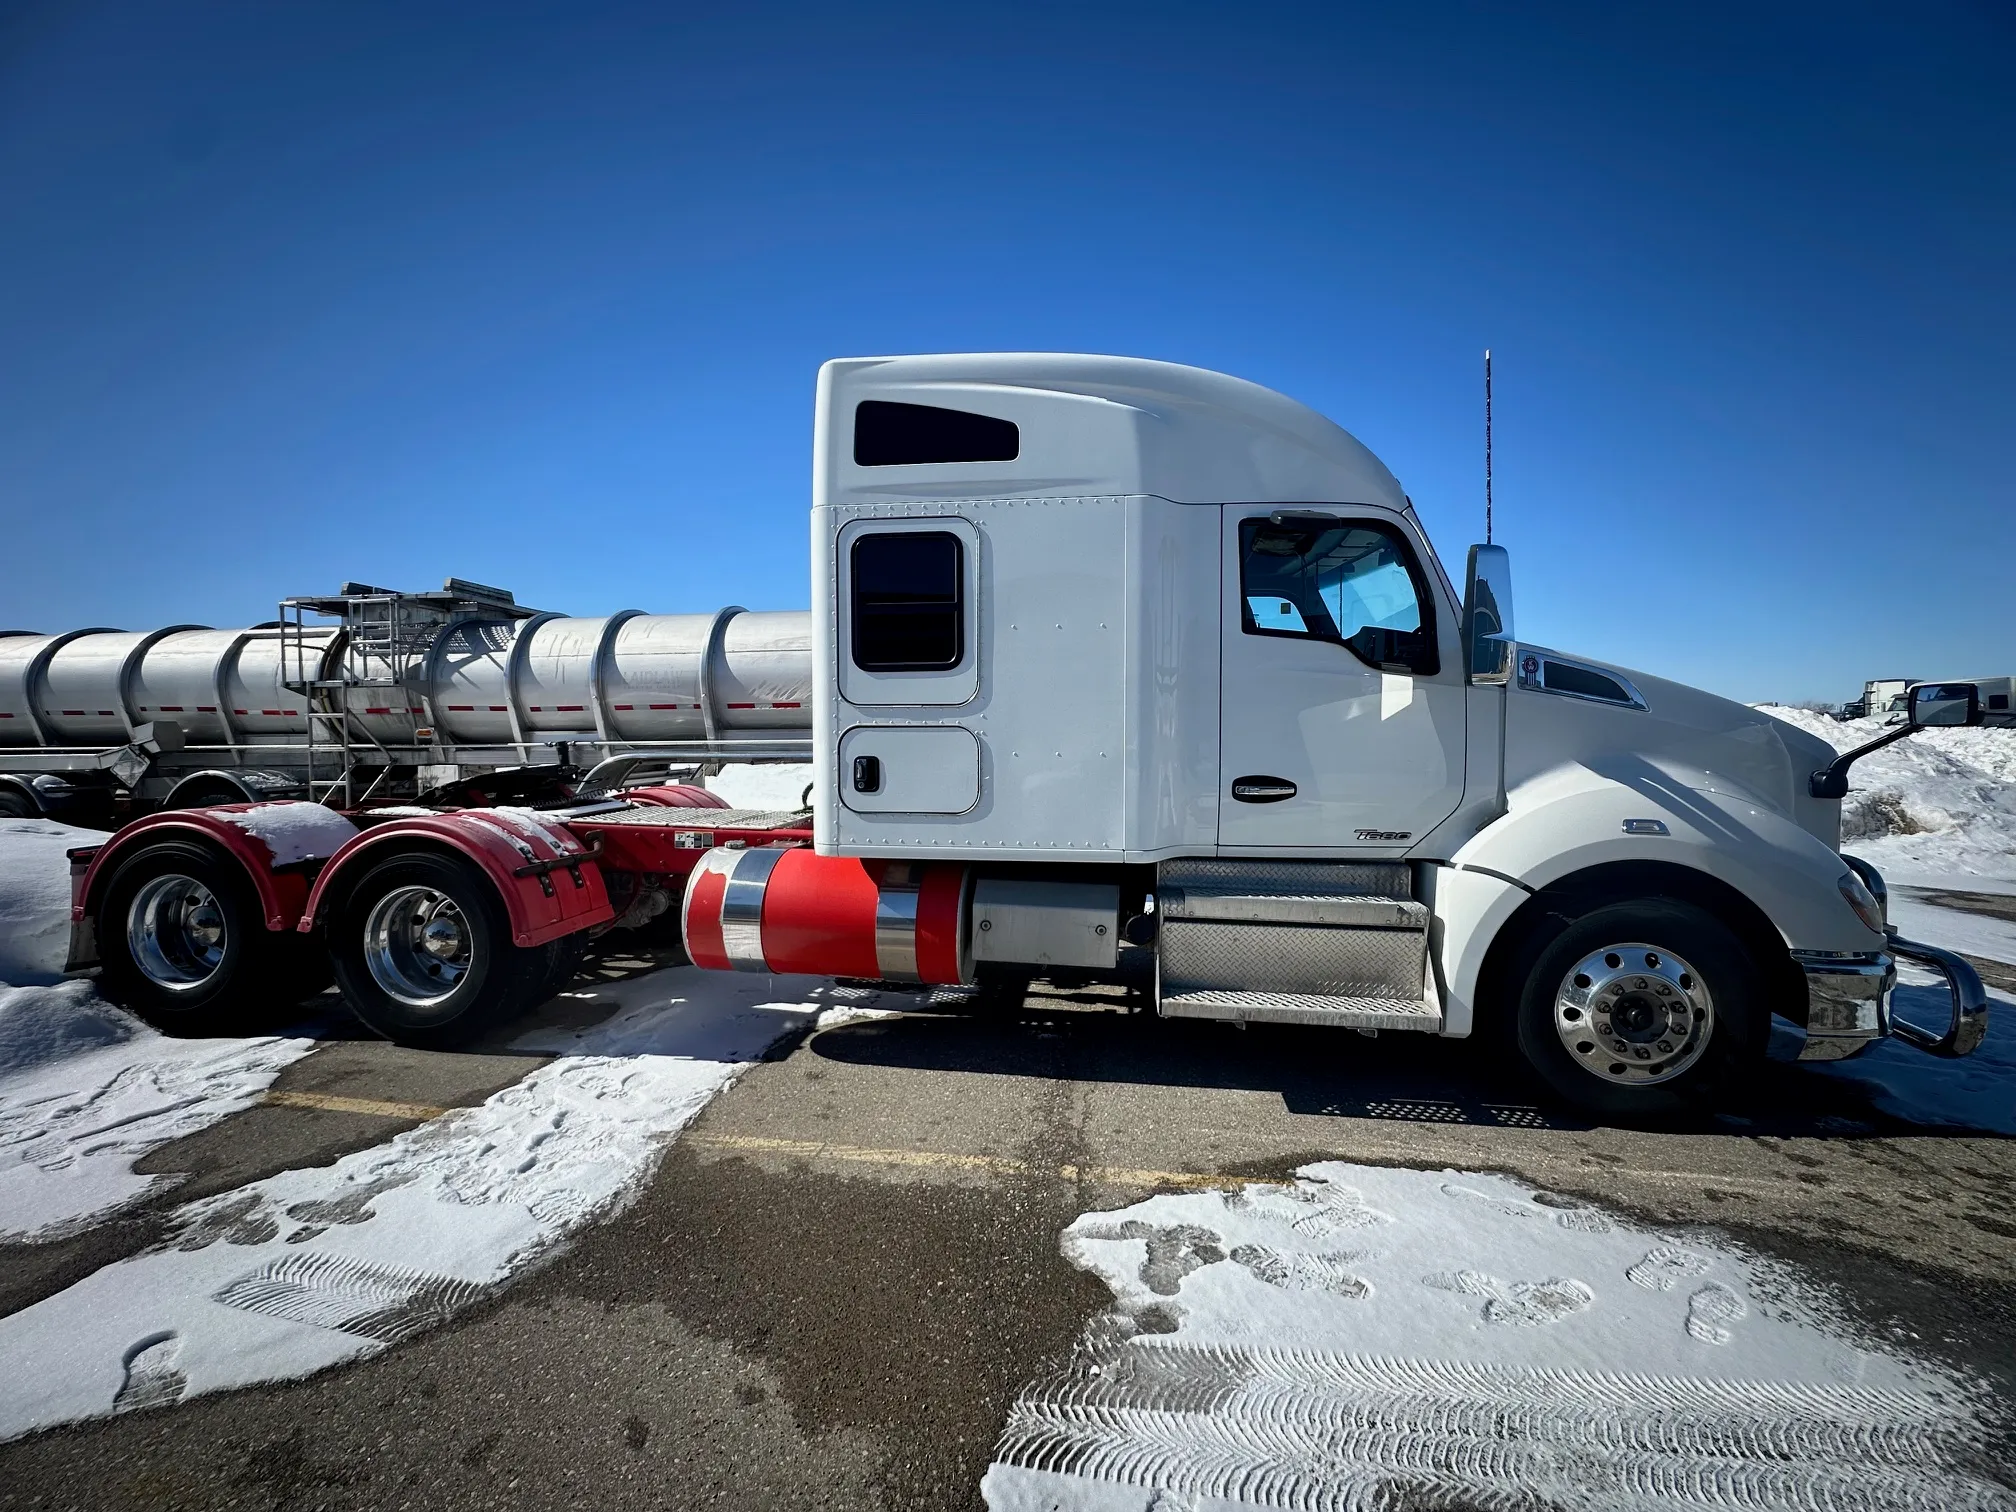
2021 Kenworth T680 sleeper truck financed for commercial trucking

FUNDED · MARCH

CAD $50,000

2021 Kenworth T680 sleeper truck
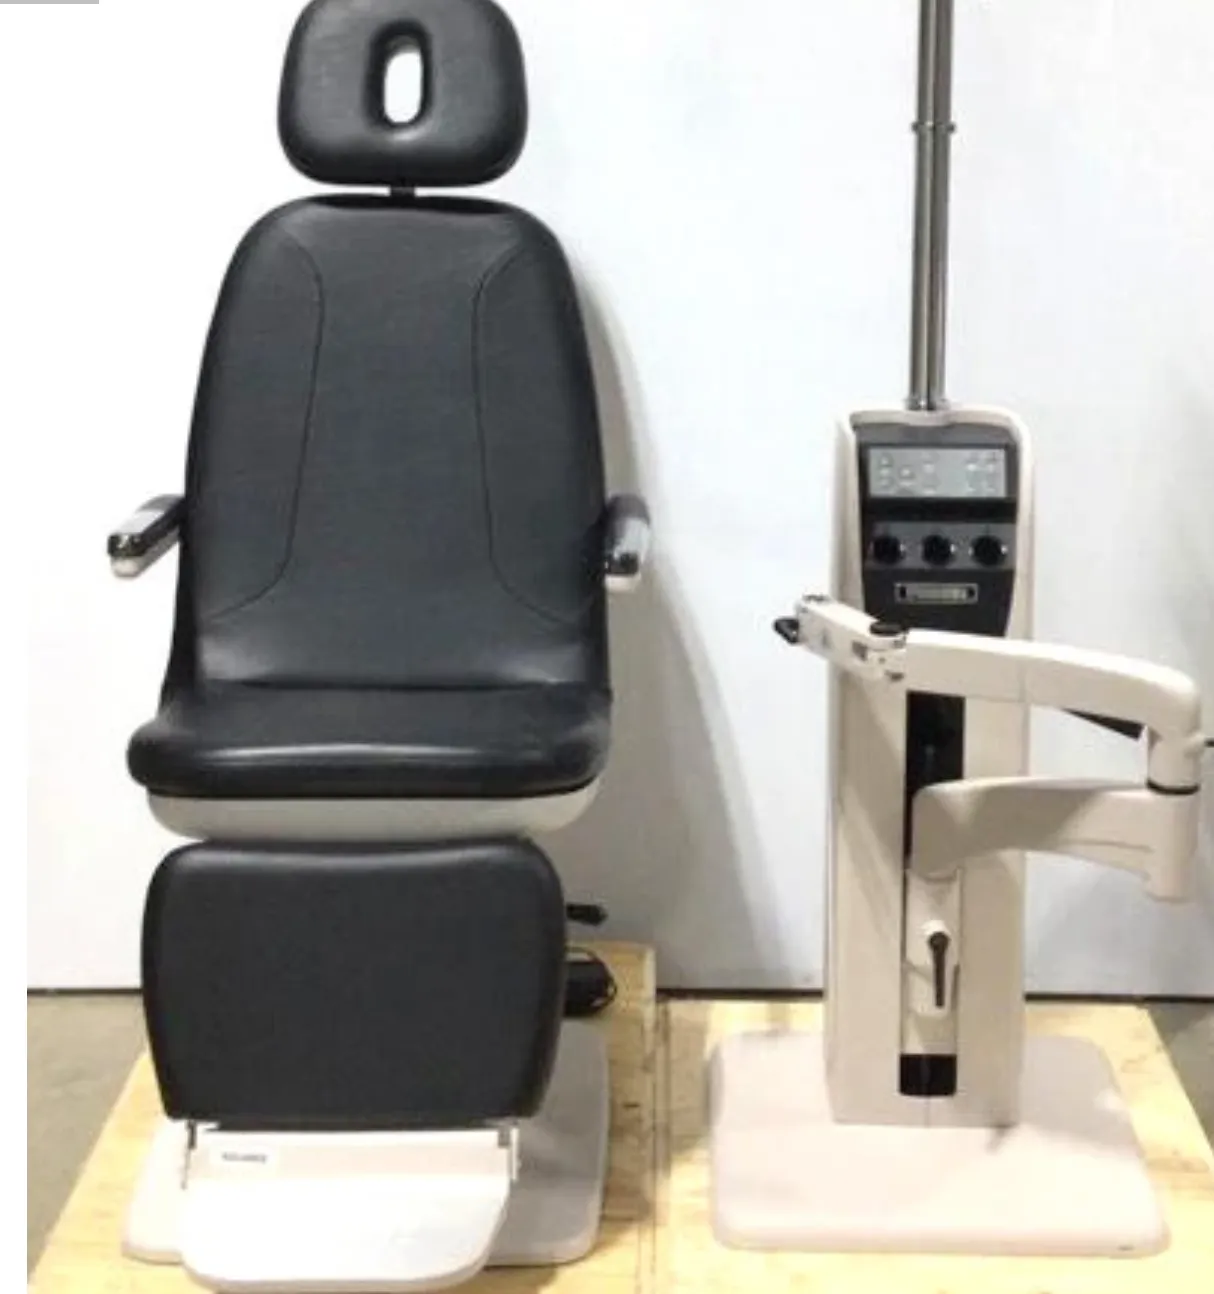
Ophthalmic exam-lane chair and instrument stand financed for an eye-care practice

APPROVED · OCTOBER

CAD $200,745

Medical exam-lane equipment
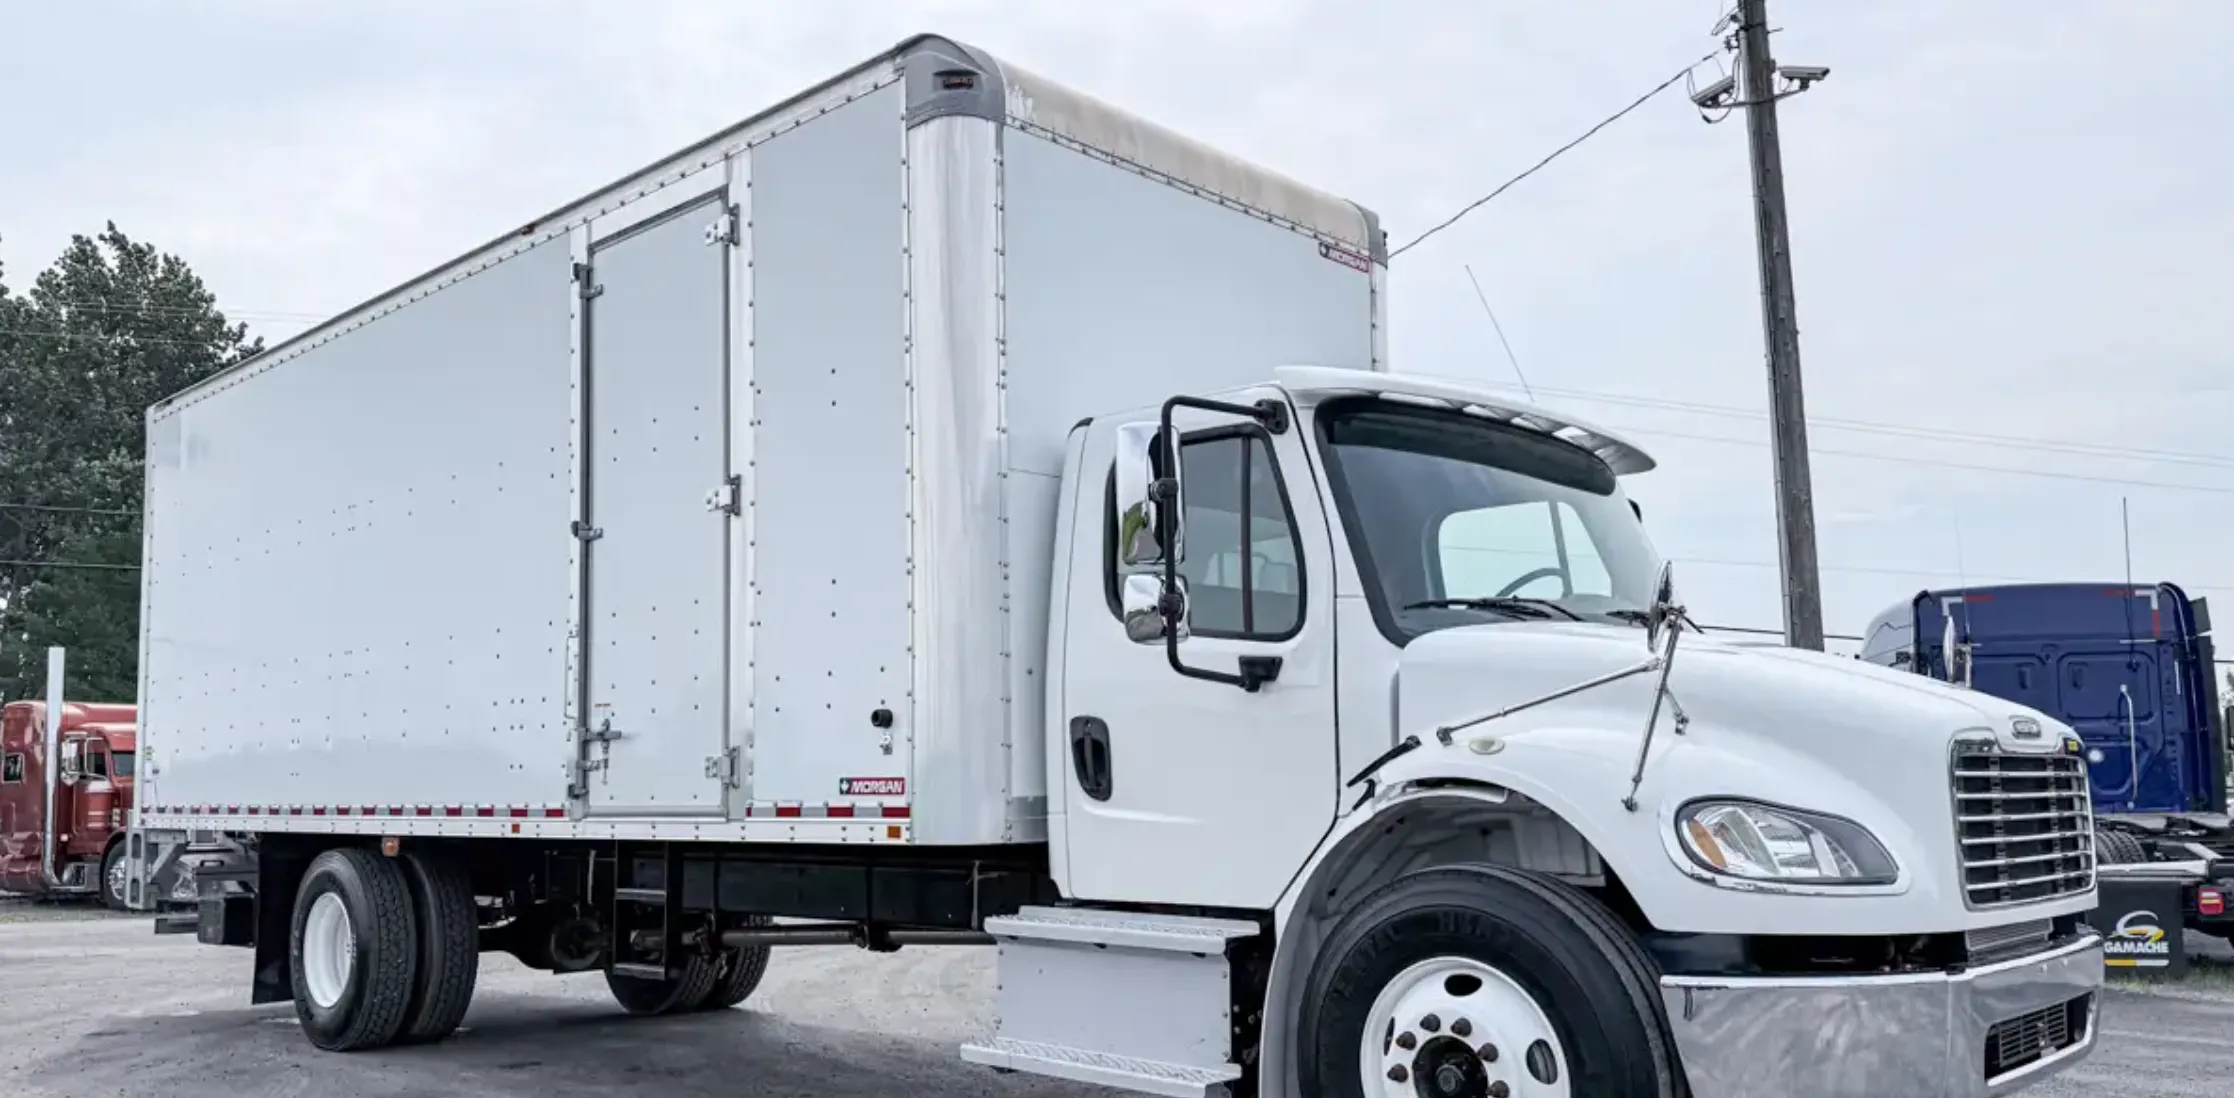
2019 Freightliner M2 106 box truck financed for commercial transportation

FUNDED · SEPTEMBER

CAD $45,000

2019 Freightliner M2 106 commercial truck

“I needed financing, not another bank runaround. Mehmi made the process simple, matched me with the right option, and helped me get the funding my business needed.” - Small Business Owner

Why Small Businesses Choose Mehmi Financial Group

  • Clarity Before Submission
    Explore equipment financing with your cash flow in mind.

  • Strong Lending Relationships
    We help compare options from providers we work with, based on your business needs.

  • Transparency and Honesty
    We explain available options and help prepare your application for provider review.

Our Process

1
Tell Us What You Need
No obligation. Clear review. Clear options.
2
Explore Financing Options
We review your file and help you apply to potential providers. Approval and terms depend on their assessment.
3
Complete Final Requirements
If approved, we help coordinate documents and outstanding conditions. Funding remains subject to the provider's final requirements.

What Our Clients Say

Google Reviews
Leave us a Review!

I am really happy with the service that was provided. Communication was great and would refer anyone to get financing/leasing done from them.

Reviewer avatar with the initial H
Harpreet Basi
1 weeks ago

Zora helped us finance our fleet of commercial trucks and trailers in Windsor and kept the process clear and organized.

Reviewer profile image
Emily Shleyfman
2 weeks ago

I had an excellent experience with Mehmi Financial Group! The team made the process of getting qualified for an equipment loan seamless and stress-free. They were professional, responsive, and really took the time to understand my needs.

Reviewer profile photo
Azaan Popat
3 weeks ago

I refinanced our equipment with flexible terms and a lower down payment, even when the banks wanted me to put much more up front. Great company to work with.

Reviewer profile photo
pierina pezan
3 weeks ago

We set up a vendor program with Mehmi Financial Group so we can offer leasing to our customers at the point of sale. David guided us through the whole process, explained everything and made it easy for our customers to get approved without delays.

Reviewer profile photo
Aaron Vasant
3 weeks ago

Mehmi Financial Group helped our Ontario business get equipment financing quickly and with minimal back-and-forth. Clear guidance, responsive team, and terms that fit our budget.

Reviewer avatar with the initial S
Sterling Phoenix
4 weeks ago
4.8
from over
86
Reviews

FAQs

How fast can I get approved and funded?
Approval and funding timelines vary by lender, financing type, and the completeness of your application. Have three to six months of business bank statements (PDF works best) ready before you apply. For equipment financing, add the equipment quote or invoice and proof of insurance. Used equipment and private sales may require additional lien searches and VIN or serial number checks.
What credit score do I need for equipment financing?
There is no single universal credit-score cutoff. Lenders may consider credit alongside time in business, cash flow, existing obligations, the asset and the requested structure. Requirements differ by financing type and provider, and stronger credit can expand the options available.
Can I get financing with bad credit, or after my bank said no?
A bank decline does not automatically mean no other options are available. Equipment-focused and alternative lenders may assess the asset, deposits, revenue trend, industry and overall credit profile differently. Approval is not guaranteed, and some files may require more equity, collateral, shorter terms or other conditions.
How much of a down payment do I need?
Down-payment requirements depend on the financing structure, lender, asset, credit profile and transaction. Some equipment transactions may require little upfront equity while others require a meaningful contribution. Working-capital products are structured differently and are not evaluated as an equipment down payment.
What are the rates right now?
Pricing varies by lender, credit profile, asset, term, amount and market conditions. Compare the full cost, not just the headline rate, including fees, payment frequency, prepayment terms, residual or buyout obligations, and any variable-rate provisions. A quote is specific to the transaction.
Should I lease or buy equipment?
The better fit depends on how long you plan to use the equipment, your cash flow and the available terms. Financing a purchase may suit long-term ownership; leasing may offer different payment and replacement options. Compare total cost as well as monthly payments, including the deposit, fees, insurance, maintenance, early-exit costs and any end-of-term payment. Payments may be fixed or variable. Ownership, buyout, return and renewal rights depend on the agreement. A lower monthly payment can still mean a higher total cost. We can help you review available quotes, subject to eligibility, provider approval and final terms.
What is Mehmi's Embedded Finance program?
If you sell, manufacture or distribute equipment, our vendor program lets you offer your customers equipment financing right at the point of sale. Your customer picks the equipment and fills out a short application through your showroom or website. We assign a credit analyst to your deals, match each customer with the right lender and handle the paperwork. Approval timelines depend on the lender and the completed application, and you get paid when the deal closes. There's no setup cost, and the financing sits with the lender, not on your books.
Difference between equipment and business financing?
Equipment financing is tied to a specific asset and may use that asset as security. Business financing such as working capital or a line of credit is generally based more on the business's cash flow and credit profile. Down payments, collateral, pricing and documentation vary by product, lender and transaction.
What documents do I need to apply?
Required documents vary by financing type and lender. Common requests can include business bank statements, government-issued identification and basic company information. Equipment transactions may also require a quote or invoice, asset details and insurance before funding, while other business-financing requests may require financial statements or tax information.

Built for Business. Backed by Experience.

Built for Business.
Backed by Experience.

White outline map of North America on a brown background, above the text 'Serving Canada & United States' in white letters.