

Revenue based financing can give a business cash without selling part of the company. Repayments move with revenue, but the total cost still depends on the deal you sign. Here’s how it works, what to check before you agree, and when another form of financing may fit better.
What Revenue Based Financing Is and How Repayment Works
Revenue based financing, often shortened to RBF, gives a business capital in exchange for a share of future revenue. The funder advances money, then collects an agreed portion of revenue until the business meets a repayment amount or other contract terms.
Unlike a standard term loan, the payment may change as sales rise or fall. That can ease pressure in a slow month. But a larger payment in a strong month can leave less cash for payroll, stock, rent, or other costs.
Every contract defines revenue and collection in its own way. It may use gross sales, card sales, or another measure. Check whether refunds, taxes, payment processor fees, and one-off income count. The word “revenue” alone doesn’t tell you how the funder will calculate a payment.
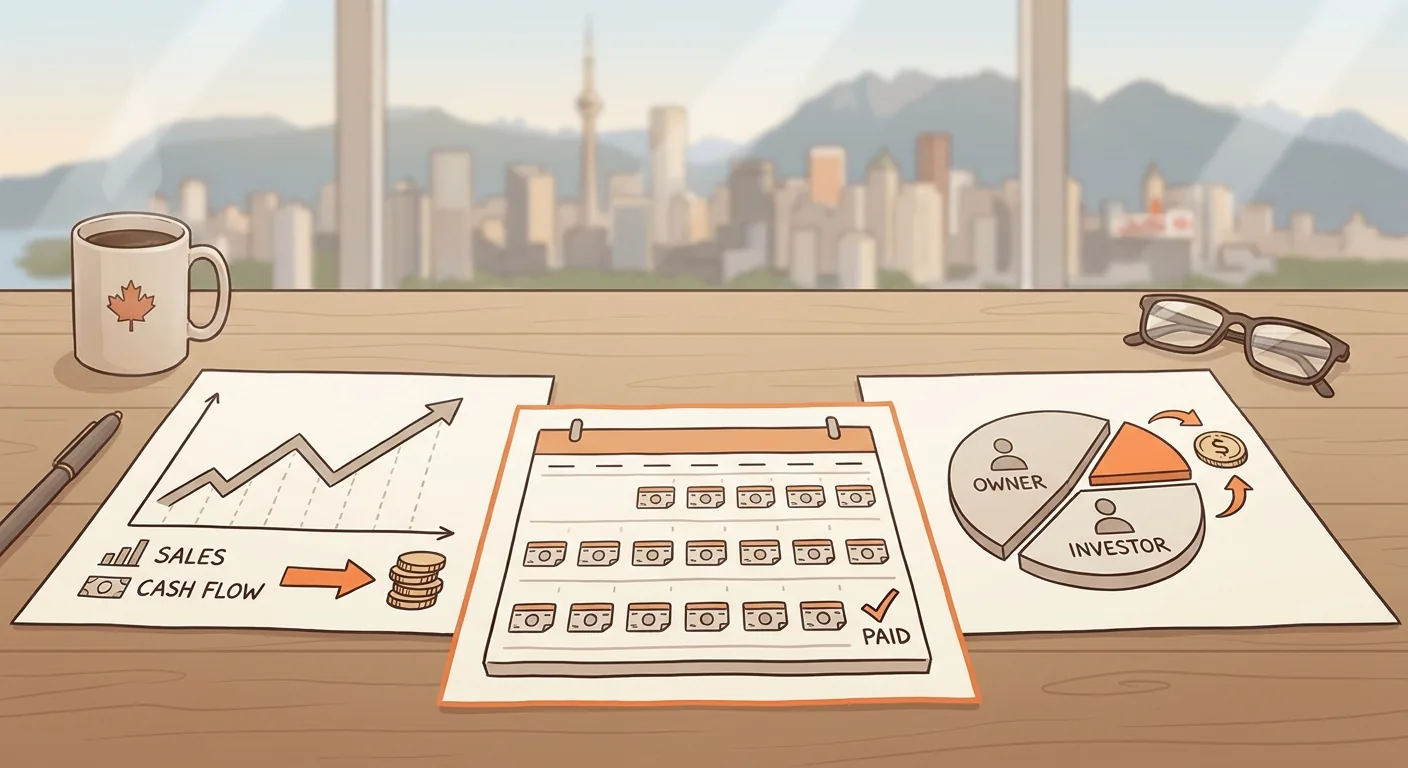
The agreement may also set a total repayment cap, sometimes expressed as a multiple of the advance. For example, imagine a business receives CA$100,000 and agrees to repay CA$130,000 in total. The CA$30,000 difference is the financing cost in this simplified example. It isn’t a quote or a typical Canadian rate. The revenue share affects how quickly the business reaches the cap, while the contract sets what it must repay.
That distinction matters. If sales grow, the business may repay the cap sooner. If sales slow, the repayment period may stretch. Ask what happens if revenue falls sharply or the business closes, and whether the agreement includes a minimum payment, a personal guarantee, or fees beyond the repayment amount.
For a Canadian business, the useful question is not only “What’s the monthly payment?” It’s “How much cash remains after this payment in a weak month?” Mehmi Financial Group helps businesses compare financing options and prepare the information lenders may need. A clear cash-flow picture can help you assess whether variable repayments suit the use of funds.
Who RBF May Suit: Industries, Eligibility and Documents
RBF may suit a business with steady, trackable sales and a clear plan for using the funds. A retailer may see sales rise and fall with the season, while a subscription business may bill on a regular cycle. In both cases, the funder needs enough reliable revenue history to judge repayment capacity.
Revenue alone isn’t enough. Thin profit margins can make a revenue share hard to carry, even when sales look strong. A business that depends on a few large invoices may also find that its cash comes in unevenly. Compare the payment formula with when customers actually pay, not just the date a sale is recorded.
Most funders review information that shows how the business earns and manages cash. The exact list varies, but you may be asked for:
- Recent business bank statements and sales or payment records.
- Financial statements, plus a current view of revenue and expenses.
- Business registration details and information about the owners.
- A short explanation of the funding need and how the money will be used.
- Details of existing loans or advances that already draw from revenue.
Be ready to explain changes in sales. If a large customer paid late or a seasonal dip affected a month, show the context with records. Clear documents help a lender assess the business as it is, rather than relying on a single unusual period.
RBF is generally discussed for businesses that already earn revenue. A business with no sales may need to consider a different route. For an equipment purchase, a lender may focus on the asset, the purchase quote, down payment, and the business’s ability to repay. Mehmi Financial Group helps Canadian businesses compare working capital and asset-based options, including commercial equipment financing. The right structure depends on the purpose and the full terms.
Before applying, make a simple monthly cash-flow view. Include current debt payments, tax instalments, payroll, supplier bills, and the proposed revenue share. If the plan only works when every month is strong, the offer may be too large for the business.
RBF Compared with Loans and Equity: Cost, Credit and Accounting
RBF sits between debt and equity in how owners experience it. It usually doesn’t require selling ownership, but it still creates a repayment obligation. A term loan has set payments under its contract, while an equity investment gives investors an ownership stake instead of scheduled repayment. The distinction between revenue-based financing and merchant cash advances can be less clear in practice; this comparison of merchant cash advances and revenue-based finance explores differences in sales definitions, repayment rules, fees, and personal obligations.
The choice depends on how the business earns money and what it can afford to give up. A business with stable cash flow may value a fixed loan payment. A business with variable revenue may prefer payments tied to sales, if the contract has no floor that makes slow periods harder. A founder who wants outside capital without repayment may weigh equity, while accepting ownership dilution and investor rights.
| Funding type | How cash is repaid or shared | What to weigh |
|---|---|---|
| Revenue based financing | A share of defined revenue, subject to the agreement’s terms | Check the total cap, revenue definition, collection rules, and effect on working cash. |
| Term loan | Scheduled payments set by the loan agreement | Check the payment amount, rate type, term, fees, security, and any guarantee. |
| Equity financing | No regular repayment, but investors receive ownership rights | Consider dilution, investor terms, and how future decisions may be shared. |
To compare cost, ask for the total amount payable in dollars, not only a revenue percentage or a headline factor. Find out whether fees are deducted before funds arrive. Then compare the repayment timeline under both a typical month and a weaker month. A low payment can still lead to a long, costly agreement if the cap is high.
Credit effects aren’t automatic or identical across funders. Ask whether the application involves a credit check, what gets reported, and whether missed payments or a default may affect business or personal credit. Also ask how the agreement treats early repayment and whether paying early reduces the total cost.
Accounting treatment depends on the contract and the business’s reporting needs. Don’t assume that a revenue-share agreement is recorded the same way as a conventional loan or an equity investment. Have your accountant review the signed terms, including any fees and obligations that continue after funding.
For information about one government-backed small-business lending program, see its program page. Private RBF terms are set by each agreement.
How to Evaluate and Negotiate an RBF Offer in Canada
Read the agreement against your actual cash-flow pattern. A useful review starts with the amount you receive, then follows every payment through to the final obligation.
- Confirm the net funds. Check the advance amount and subtract any fees taken at funding. Make sure the amount left will cover the planned expense.
- Define the revenue share. Ask which sales count, how often the funder collects, and how returns or payment disputes are handled.
- Calculate total repayment. Record the cap or other total obligation in dollars. Ask whether early repayment changes that amount.
- Test a slow month. Apply the agreement’s formula to a low-sales month from your records. Check the cash left for essentials and existing commitments.
- Review defaults and security. Read the terms for missed remittances, personal guarantees, liens, and what happens if the business closes or changes ownership.
Ask for answers in writing. If a salesperson explains a term that isn’t clear in the agreement, request an updated document or written clarification before signing. Pay close attention to renewal language and any clause that lets the funder change collection timing.
Negotiation may focus on the amount advanced, the revenue share, the repayment cap, fees, or early-payment terms. You can also ask whether the proposed payment fits your business’s monthly sales pattern. There’s no promise that a funder will change an offer, but a well-prepared forecast gives both sides a clear basis for discussion.
For a conventional business loan, review loan program information and ask how the lender assesses risk and what records support its decision. Program guidance may be specific to that program, not a universal checklist for private financing.
If you’re weighing several lending routes, Mehmi Financial Group can help you compare options and prepare an application around your business needs. We work with businesses seeking working capital, refinancing, invoice financing, and equipment financing. Terms and availability depend on the lender and transaction. You can review our business financing options as part of that comparison.
Illustrative RBF Journey, Provider Differences and Market Trends
Imagine a Canadian manufacturer that needs cash to buy materials for confirmed orders. Sales are regular, but customer payment dates vary. The owner considers RBF because repayments may follow revenue rather than a fixed monthly schedule. Before applying, the owner maps expected sales against payroll, supplier bills, and existing debt.
The owner then gathers bank statements and financial records, explains the order cycle, and requests a written offer. The key review is whether the payment formula counts revenue when an invoice is issued or when cash arrives. If the agreement takes a share before the customer pays, the business could face a cash gap even as reported sales look healthy.
That example shows why provider fit matters. Some funders focus on recurring digital revenue, while others work with a broader range of small businesses. Products also differ in how they define revenue, set repayment, and review applications.
Eligibility and terms vary across the market. Some funders focus on technology or online sales; others consider broader business types. Funding details also vary, so compare offers directly and ask each provider for its full cost and contract terms. A single industry label doesn’t tell you whether the financing fits your cash cycle.
Mehmi Financial Group works as a financing brokerage, helping businesses compare lending options and prepare applications. That can be useful if you’re deciding between cash-flow funding and asset-based financing. A truck, trailer, or machine may support a different financing structure than general operating costs. For businesses assessing an intermediary, our guide to the best business loan brokers explains what to consider. Start by matching the funding to the expense and its expected payoff period.
For a Canadian business, the sensible trend to watch is not a headline about market growth. It’s whether the available terms match the way your business earns and spends money. Ask for a written offer, run the numbers against a weaker month, and compare it with other options before you commit.
Frequently Asked Questions
How much does revenue based financing cost?
The cost depends on the agreement’s total repayment amount, fees, and payment rules. Ask for the full amount payable in dollars, then compare it with the net cash you’ll receive. A revenue share by itself doesn’t show the whole cost. Test the terms against both a normal month and a slow month before deciding.
Does revenue based financing affect my credit score?
It may, depending on the funder’s credit checks, reporting practices, and the terms you sign. Ask whether the application includes a personal or business credit inquiry. Also confirm what the funder reports and what happens after a missed payment. Don’t assume the agreement has no credit impact because payments are linked to revenue.
Can a new business qualify for RBF?
A business usually needs a trackable revenue history for a funder to assess this type of financing. A pre-revenue company may not have the sales records needed to support an offer. Eligibility varies by provider, so ask what revenue history and documents it needs before spending time on an application.
Is RBF a loan or equity financing?
Revenue based financing is generally structured around an advance repaid through a share of revenue, while equity financing gives investors an ownership stake. The legal and accounting treatment depends on the contract. Review the agreement with a qualified accountant or legal adviser, especially if it includes guarantees, security, or extra payment obligations.
Conclusion
RBF may fit a Canadian business with steady sales that wants capital without selling ownership, but the repayment cap and cash-flow impact deserve close review. Compare the written terms with a slow-month forecast before signing. If you’re weighing RBF against equipment or working-capital options, prepare your funding need and recent financial records, then discuss the fit with Mehmi Financial Group.