

Quick answer: CNC machine financing can help a Canadian shop spread an eligible purchase over scheduled payments, subject to approval. Build the request around the complete project: machine, tooling, rigging, installation, software and cash needed before customer receipts begin. Confirm which costs the proposed agreement covers, when suppliers must be paid and what happens if commissioning takes longer than planned.
Reviewed November 11, 2026.
Key takeaways
- Identify the exact machine, controller, options and seller.
- Budget the path from purchase to accepted production, not just delivery.
- Separate equipment, installation services and recurring expenses.
- Compare payment obligations with realistic production and collection dates.
Define the production problem first
Explain why the shop needs the CNC machine. It may replace unreliable capacity, bring an outsourced operation inside or support work that existing equipment cannot handle. Name the process and the constraint so the financing request has a clear business purpose.
Distinguish demand from capacity. A faster machine does not create orders by itself. If the purchase supports a customer contract, identify the expected volume, production requirements and payment terms. Separate confirmed work from quotations and sales opportunities still under discussion.
Check the rest of the production flow. Additional machining capacity may require more inspection, deburring, material handling or skilled programming. Include those needs in the plan rather than assuming the new machine alone will increase shipped output.
Document the machine precisely
Provide the manufacturer, model, year, serial number where available, controller and included options. Attach the supplier quote and specification sheet. List accessories separately so the reviewer can see what is included in the price and what must be purchased elsewhere.
For a used machine, request service records and a condition review by a qualified technician. Discuss appropriate inspection or demonstration work with that adviser. A photograph of a powered-on controller does not establish accuracy, spindle condition or suitability for your parts.
Verify the software and support arrangements. Ask which licences transfer, whether subscriptions continue and who can service the controller. Identify any necessary programming, post-processor or training work before counting the machine as production-ready.
Prepare the site before delivery
Use the manufacturer's instructions for the exact model and installation. Haas's VS-1 pre-installation guide, for example, addresses foundation, access, electrical and air preparation, installation scheduling and professional rigging. Its numerical specifications are model-specific and should not be applied to every CNC machine.
Ask qualified installers to review the shop layout and delivery route. Confirm door access, unloading arrangements, floor suitability, service clearances and the location of supporting equipment. Obtain written quotes for required work and assign responsibility for completion.
Check the sequence. If the electrical work cannot finish before delivery, storage or a second move may be needed. If the shop leases its premises, resolve any required permissions before ordering permanent changes. These practical dependencies belong in the purchase schedule.
Build a complete acquisition budget
| Cost group | Examples to identify | Financing question |
|---|---|---|
| Machine package | Base machine and permanent options | Is the full quoted package eligible? |
| Delivery and installation | Freight, rigging, electrical work and commissioning | Which costs can be included and paid to which suppliers? |
| Production setup | Toolholders, fixtures, software and training | What needs separate approval or cash? |
| Operating cash | Material, wages and customer payment delay | What reserve remains after the purchase? |
Do not assume all related expenses can be financed under one equipment agreement. Supply itemized quotes and ask for a written inclusion list. If an expense is excluded, show exactly how the business will pay it.
Check whether amounts are payable at order, shipment, delivery or acceptance. A supplier's deposit schedule and a financing provider's disbursement conditions may not align automatically. Resolve any gap before paying a non-refundable deposit.
Use a project example to find the cash gap
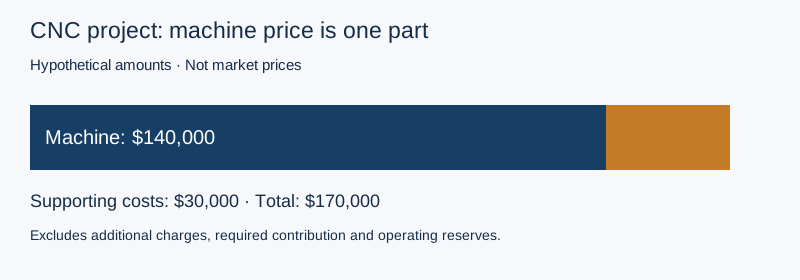
Suppose a hypothetical shop buys a machine for $140,000. Rigging and installation cost $12,000, tooling and fixtures cost $10,000, and training and software setup cost $8,000. The project totals $170,000 before any additional charges or operating reserve.
If the financing proposal covers only the $140,000 machine, the shop still needs $30,000 for the listed supporting costs, plus any required contribution and excluded charges. A quote described as financing the machine does not necessarily finance the complete project.
The example uses invented amounts, not typical CNC prices. Replace each figure with supplier quotes and avoid counting the same deposit twice. Keep a separate line for cash needed while parts are being produced, inspected, shipped and paid for.
Allow for commissioning and customer acceptance
Delivery is one milestone. Installation, operator training, programming, trial production and customer acceptance can follow on different dates. Build a schedule that connects those events to the first expected receipt of cash.
Ask when financing payments begin and whether any alternative start date is available. If a deferral is offered, obtain the full cost and conditions. A later first payment does not make installation delays harmless or remove the underlying obligation.
Test a slower start. Identify which existing receipts would cover payments and payroll if the first production run needs rework or a customer postpones acceptance. Keep the forecast realistic about scrap, setup time and the learning period.
Compare a loan and lease using the intended outcome
Decide how long the shop expects to use the machine and whether it wants ownership at the end. Then request written proposals for the same purchase price and contribution. Compare initial amounts, regular payments, final obligations and early-settlement provisions.
A lower monthly lease payment may accompany a separate buyout or another end-of-term requirement. Confirm the actual contract rather than assuming every lease permits a return or upgrade. Our equipment loan and lease comparison outlines the questions.
Ask your advisers to review the agreement and its implications for the business. Keep the machine specification and complete payment schedule together so that advice addresses the actual proposal. Resolve unanswered contract questions before committing to the purchase.
Prepare the business information
Provide current bank statements, financial records, ownership information and existing debt commitments. Include a short description of customers and the machine's role. Where the investment replaces outsourcing, show actual historical spending and the new internal costs rather than treating the entire outsourced invoice as savings.
For growth work, explain the margin assumptions and customer concentration. An order book is useful context, but it does not remove cancellation, production or collection risk. Identify what the business can support if one major order changes.
For startup requests through Mehmi, the business needs at least six months of revenue supported by bank statements. Approval remains subject to review of the business, asset and transaction. Avoid committing to an auction or supplier deadline on the assumption that a new application will be completed in time.
Handle used, private-sale and imported machines carefully
For a private sale, confirm the seller's authority and the documents needed to address existing security interests. Match the serial number across the invoice, inspection and financing file. The PPSA guide explains why a registry check forms only part of that review.
For an imported machine, identify the seller's country, invoice currency, shipping responsibility and installation destination. Obtain specialist advice on import and installation requirements. Canada-wide financing availability does not mean every foreign supplier or advance-payment arrangement is acceptable.
Keep the equipment decision and payment instructions coordinated. Tell the financing provider about changes in the machine, seller or installation package before closing. A revised purchase can require revised documents and approval conditions.
Frequently asked questions
Can used CNC machines be considered?
Yes, subject to assessment. Provide detailed machine information, condition evidence, seller documents and a clear production purpose.
Can tooling and installation be included?
Some proposals may include eligible related costs. Confirm the actual inclusion list; do not assume every service or consumable is covered.
Does a signed customer order guarantee approval?
No. It supports the business explanation but does not replace financial, asset and transaction review.
When should the financing discussion begin?
Before committing to deposits or short payment deadlines. Share the supplier schedule and required commissioning date early.
Tools and next steps
Prepare the machine specification, itemized project budget and commissioning cash schedule. Compare written offers against all three.
To discuss a CNC machine purchase, contact Mehmi Financial Group or call 1-833-863-4644.
Sources
- Haas: VS-1 pre-installation guide. Reviewed November 11, 2026. Model-specific example only; project figures are hypothetical.
By Jodhbir Mehmi. Read our editorial standards.