
Delivery and distribution
Examples to help describe the request.
- Hino L Series
- Freightliner M2
- International MV

CANADA & UNITED STATES
Build the right truck for the job.
Explore financing for commercial delivery trucks, box trucks, cab-and-chassis units and service vehicles across Canada and the United States. Consider the completed vehicle—not only the base chassis—when you prepare the budget.
Discuss your financing needs ↗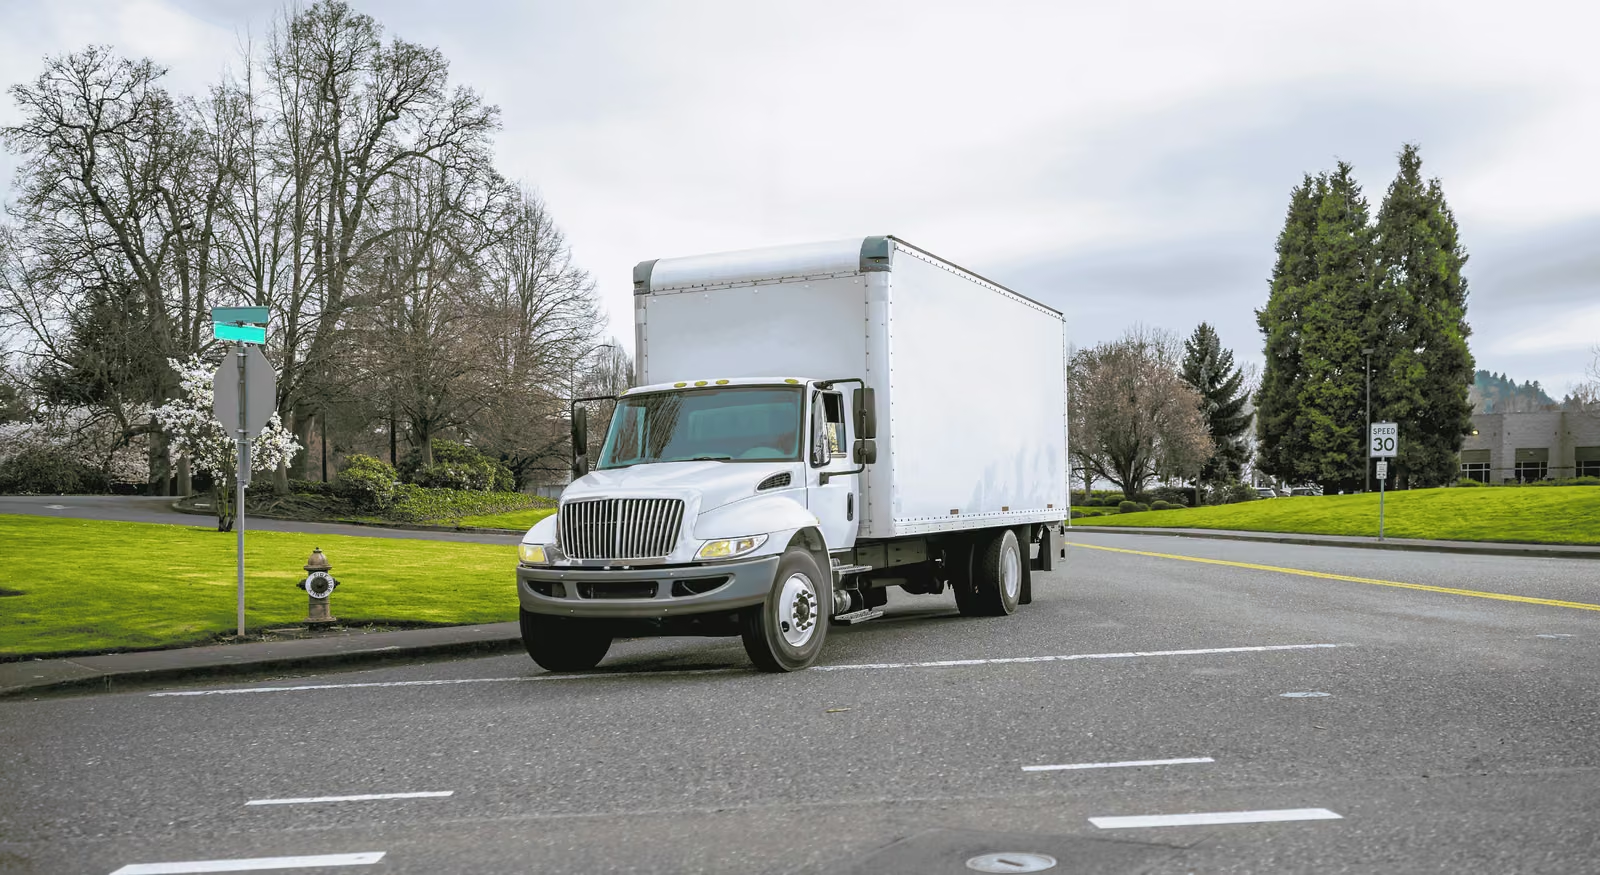
The same model family can span different weight ratings. Verify the exact gross vehicle weight rating, payload and body configuration rather than relying on a “medium-duty” label. Separate the chassis quote from the upfit and delivery costs.
EQUIPMENT FINANCING, EXPLAINED
▶ Watch video ↗A general introduction to equipment financing. Discuss the specific vehicle and transaction with our team.
Examples to help describe the request.
Examples to help describe the request.
Brands and models are illustrative equipment examples, not a statement of affiliation or guaranteed eligibility. Availability depends on the unit, seller, business and transaction.
| Approach | How it works | What to review |
|---|---|---|
| Equipment loan | A purchase financed over an agreed term. | Review security, down payment, total repayment and any final balance. |
| Equipment lease | Use of the asset under a contract with defined end-of-term conditions. | Compare rentals, deposit, buyout or return conditions and residual exposure. |
| Cash purchase | Pay the seller from available business funds. | Compare the upfront cash use with operating reserves and other planned spending. |
A financing label does not determine tax treatment. Canadian and U.S. rules differ, and a lease may be treated differently from a purchase depending on the agreement. Confirm deductions, sales tax and timing with your accountant.
Explore equipment leases ↗ · Compare loan and lease scenarios ↗Tax references: CRA leasing costs ↗ · IRS lease or purchase treatment ↗
A local distributor replacing a box truck should budget the chassis, body, liftgate, branding and delivery together. Check whether the upfitter requires a deposit before the truck is ready. Compare the proposed payment with the route’s contribution after the driver, fuel, maintenance and insurance are paid.
This is a planning example, not a customer result or forecast. Compare a base case with lower utilization, slower customer payments and an unexpected repair.
Check these costs before committing to the asset.
A route to retaining the asset may fit a business that plans to use it for several years.
Some leases provide a return, renewal or purchase choice. The agreement must actually include the option.
Cash ownership avoids a new financing payment but uses funds that may be needed elsewhere.
For eligible commercial vehicle transactions, a TRAC lease may link an end-of-term adjustment to the difference between the vehicle’s realized value and an agreed residual. Depending on the contract, a shortfall can create an additional payment and a surplus may be credited. Availability and tax treatment depend on the location, use and structure.
Applications are reviewed using the business, cash flow, credit profile, equipment and proposed transaction. A newer operation, a private seller or an unusual asset may need more supporting information. Explain how the asset will earn or save money and identify current obligations.
Prepare the business location and transaction currency. For cross-border purchases, discuss the seller, asset location, delivery and import requirements before making a non-refundable commitment.
Apply for financing ↗Requirements vary by transaction.
Describe the asset, business location, purchase price and intended use.
Provide the requested documents. Discuss cost, security, payment timing and conditions.
If approved and you choose to proceed, complete the agreement and required conditions before disbursement.
Eligible body and upfit costs may be considered with the vehicle, subject to the proposed structure. Provide separate quotes, the installation timeline and details of any deposits. Do not assume every accessory or expense will be included.
Mehmi supports business financing requests in Canada and eligible U.S. markets. Product availability, documentation and terms depend on the business location, asset and transaction.
The asset, business profile, credit, valuation and proposed structure may affect the required contribution. Do not assume a zero-down arrangement is available; review the full amount due at signing.
Yes. Compare upfront cash, all scheduled payments, fees and the final ownership or return position. Some vehicle leases include residual exposure. Ask how any final adjustment or purchase amount is determined.
Timing depends on the application, requested documents, verification and approval conditions. Identify any seller or project deadlines early. A discussion or application is not a commitment to fund.
Review the contract first. Settlement costs, security releases, notice requirements and restrictions can differ. Request a written payout figure before selling, trading or refinancing the asset.
A Canadian guide to the documents, costs and decisions behind a financing request.
A Canadian guide to the documents, costs and decisions behind a financing request.
These articles focus on Canada. Requirements for U.S. transactions may differ.
Browse all financing articles ↗Share your location, amount and purpose to begin a financing discussion.
Apply for financing ↗Financing is subject to application review and approval. Availability, costs, terms and documentation vary by business, product and location. This page provides general information and is not a financing offer.