

Quick answer: Calculate an equipment sale-leaseback in two parts: the cash available at closing and the obligations created afterward. Start with the approved purchase amount, subtract required payouts and closing deductions, then compare the resulting cash with the complete lease schedule. Equipment value alone does not tell you how much usable cash the transaction provides.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Key takeaways
- Use an approved amount rather than treating an appraisal as a funding commitment.
- Separate deductions from proceeds and expenses paid outside closing.
- Include the ending purchase or return obligations in the comparison.
- Have an accountant review the sale and lease before relying on an after-tax result.
Begin with the exact equipment and transaction
A sale-leaseback involves selling equipment and continuing to use it under a lease. The asset stays useful to the business, but ownership and payment obligations change. Confirm that the proposed arrangement is a sale-leaseback and ask how it differs from refinancing an existing obligation.
Prepare an equipment list with serial numbers, condition, location and ownership records. Identify anything included in the value but excluded from the sale, such as an attachment owned by another entity. A calculation based on a mixed or incomplete asset list will be difficult to reconcile at closing.
Obtain current payout information for any existing financing and ask the transaction professionals which interests must be addressed. Do not assume the balance on an old statement is the amount required on the planned closing date. Our refinancing and sale-leaseback service page provides a starting point for discussing the structure.
Calculate usable closing cash
Use this planning relationship: approved gross proceeds minus required payouts, fees and other amounts withheld equals estimated cash released. Record each item separately. Ask whether an initial lease payment or deposit is withheld or paid from another account so it is counted once.
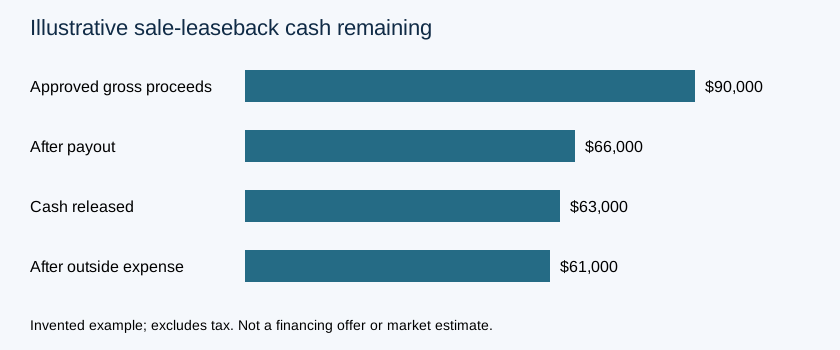
For an invented illustration, assume approved gross proceeds of $90,000, an existing payout of $24,000 and $3,000 of combined closing deductions. Estimated cash released is $63,000. If a separate $2,000 expense must be paid immediately from that cash, $61,000 remains for the intended business purpose.
These figures exclude tax and do not represent an available advance percentage or offer. They demonstrate the difference between gross proceeds, closing cash and the amount left after related expenses. Replace each input with written figures from the actual proposal.
| Illustrative item | Amount |
|---|---|
| Approved gross proceeds | $90,000 |
| Existing payout | Minus $24,000 |
| Closing deductions | Minus $3,000 |
| Estimated cash released | $63,000 |
| Separate immediate expense | Minus $2,000 |
| Cash remaining for the purpose | $61,000 |
Keep value and available proceeds distinct
A valuation can support a review without establishing the amount a provider will pay. Ask which valuation basis is being used, what equipment it covers and whether further inspection is required. Keep the report date visible if the transaction is delayed.
A machine's original invoice, current asking prices and an independent assessment may show different numbers. Ask what evidence explains the proposed amount rather than applying a generic percentage to the highest figure available.
Test a lower-proceeds scenario before spending money in anticipation of the transaction. If the cash would no longer cover the intended purpose, identify whether the project can be reduced or whether another source is needed. Do not commit the full expected amount before the conditions are satisfied.
Add up the new payment obligations
List the initial payment, number of scheduled payments, amount of each and any ending obligation. Note whether fees are included in the payment or charged separately. If the schedule changes over time, enter every phase rather than multiplying the first payment by the entire term.
For another invented calculation, 48 payments of $1,800 total $86,400. Adding a $12,000 purchase option produces $98,400 if you exercise that option, before other charges. This is a cash total for that assumed outcome, not an annual interest rate or a statement of the transaction's economic cost.
The sale also transfers ownership rights. A fair comparison with keeping the equipment must account for the asset and the end-of-term outcome, not simply subtract the cash received from all future payments and call the difference interest.
Compare the use of cash with the payment burden
Write down exactly where the proceeds will go. If they fund inventory, identify when it should turn into customer receipts. If they fund a project, include the lead time before it generates cash. If they address overdue obligations, explain how the business will avoid rebuilding the same shortage.
Prepare a cash forecast with the new lease payment and existing commitments. The cash-flow calculator can help organise timing. Use a slower collection scenario and leave necessary maintenance spending in the budget.
A transaction can release useful cash today while creating pressure later. Compare the benefit with the complete payment schedule and the importance of the equipment to operations. If the business cannot afford the new obligation under a reasonable forecast, a larger advance does not solve that problem.
Have the tax calculation prepared separately
The sale and subsequent lease need review by your accountant. Ask about the treatment of the disposal, future lease expenses and GST/HST. Do not assume that the amount arriving in the bank is all available to spend.
The CRA describes a special GST/HST calculation for certain sale-leaseback arrangements where the seller does not have to collect tax on the sale. That guidance has specific conditions and is not a universal rule for every business. Have the accountant determine whether it applies rather than applying an example mechanically.
Keep the gross cash comparison visible before adding any estimated tax consequences. Label the assumptions, timing and professional review required. A hoped-for future tax benefit should not be used to cover an immediate payment without checking when and whether it arises.
Reconcile the closing statement before signing
Ask for a statement showing the sale amount, payouts, deductions and cash released. Match it to the lease schedule and any purchase-option documents. Resolve differences between a preliminary worksheet and the final documents before accepting them.
Check what happens if the equipment needs repairs, is moved, sold or no longer required. Review insurance, maintenance and early-termination obligations. Our early payout and buyout guide identifies questions that can affect a later change of plan.
Keep copies of the completed ownership and payment documents. Assign someone to track the lease's notice dates and ending requirements. The calculation remains useful after closing when it becomes a record of what the business agreed to do.
Frequently asked questions
Can I use the equipment's invoice price as the proceeds?
Use the approved transaction amount. An old invoice can support ownership records but does not establish today's value or the available proceeds.
Can equipment with an existing balance be considered?
Ask for a review of the asset, payout and proposed structure. Any required discharge and sufficient net proceeds must be assessed. Do not assume all existing obligations can be carried into the new arrangement.
Does a lower payment mean a lower total cost?
Compare term length and ending obligations as well as the payment. A lower recurring amount may be paired with a longer schedule or larger final amount.
Is a sale-leaseback calculation a financing approval?
No. A worksheet tests assumptions. Eligibility, value, documents and repayment capacity still require review, and the final offer may differ from the estimate.
Tools and next steps
Gather the equipment records, current payout and intended use of cash. Complete separate closing-cash and payment-schedule worksheets. Ask your accountant to review tax treatment before committing.
For a review of the proposed equipment transaction, contact Mehmi Financial Group or call 1-833-863-4644. Include the asset list and the amount of usable cash the business actually needs.
Reviewed November 11, 2026. By Jodhbir Mehmi. Read our editorial standards.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Sources
- Canada Revenue Agency: GST/HST in special cases, sale-leaseback arrangements. Reviewed November 11, 2026.