

Equipment financing terms depend on the asset, business, seller and proposed agreement. Compare the repayment period, cash required upfront, payment schedule and final obligation together. A longer schedule can reduce the regular payment while increasing the total interest in a conventional loan, so affordability and total cost need separate checks.
Key takeaways
- There is no single term or down payment suitable for every equipment purchase.
- Match the repayment schedule to realistic remaining useful life and cash flow.
- Compare offers using the same price, amount financed and ownership outcome.
- Check early payout, security, guarantees and final purchase conditions.
- Use illustrative calculations to understand tradeoffs, then obtain an actual written quote.
What does the financing term describe?
Ask whether the quoted term is the full repayment period or only the period covered by the agreement before renewal or another payment. Confirm the amortization schedule and any balance remaining at the end. Similar monthly payments can hide different final obligations.
A lease may include a purchase option, return requirement or renewal condition. A loan may have a balloon payment or other features that differ from a fully amortizing schedule. Read the actual agreement rather than assuming the balance reaches zero after the last regular payment.
The term and useful life guide helps frame the decision. Start with how long the machine can realistically serve the operation under the expected workload.
What affects the proposed terms?
The equipment's condition and remaining useful life matter alongside the business's ability to make payments. Used equipment may need condition evidence, while specialized assets may raise questions about resale and valuation. Explain the asset and its role in the business clearly.
| Factor | Question to prepare for | Useful evidence |
|---|---|---|
| Equipment condition | How long can it reasonably remain productive? | Inspection and service records |
| Business cash flow | What payment fits ordinary and weaker months? | Bank records and operating forecast |
| Purchase price | What is included in the amount requested? | Itemized supplier quote |
| Seller and ownership | Can the transaction and asset be verified? | Seller details and equipment identification |
| Existing obligations | How does the new payment fit current borrowing? | Debt and payment schedule |
Use the private sale and dealer guide when preparing a purchase. A provider's general willingness to finance equipment does not establish acceptance of a particular seller or machine.
See the payment and interest tradeoff
This hypothetical example compares a $100,000 fully amortizing loan at an assumed nominal annual rate of 12%, compounded monthly. Payments occur at month-end. There are no fees, extra payments or residual balance. The rate and periods are chosen for illustration, not as market terms or an offer.
| Illustrative repayment period | Monthly payment | Total interest |
|---|---|---|
| 24 months | $4,707.35 | $12,976.33 |
| 36 months | $3,321.43 | $19,571.52 |
| 48 months | $2,633.38 | $26,402.41 |
| 60 months | $2,224.44 | $33,466.69 |
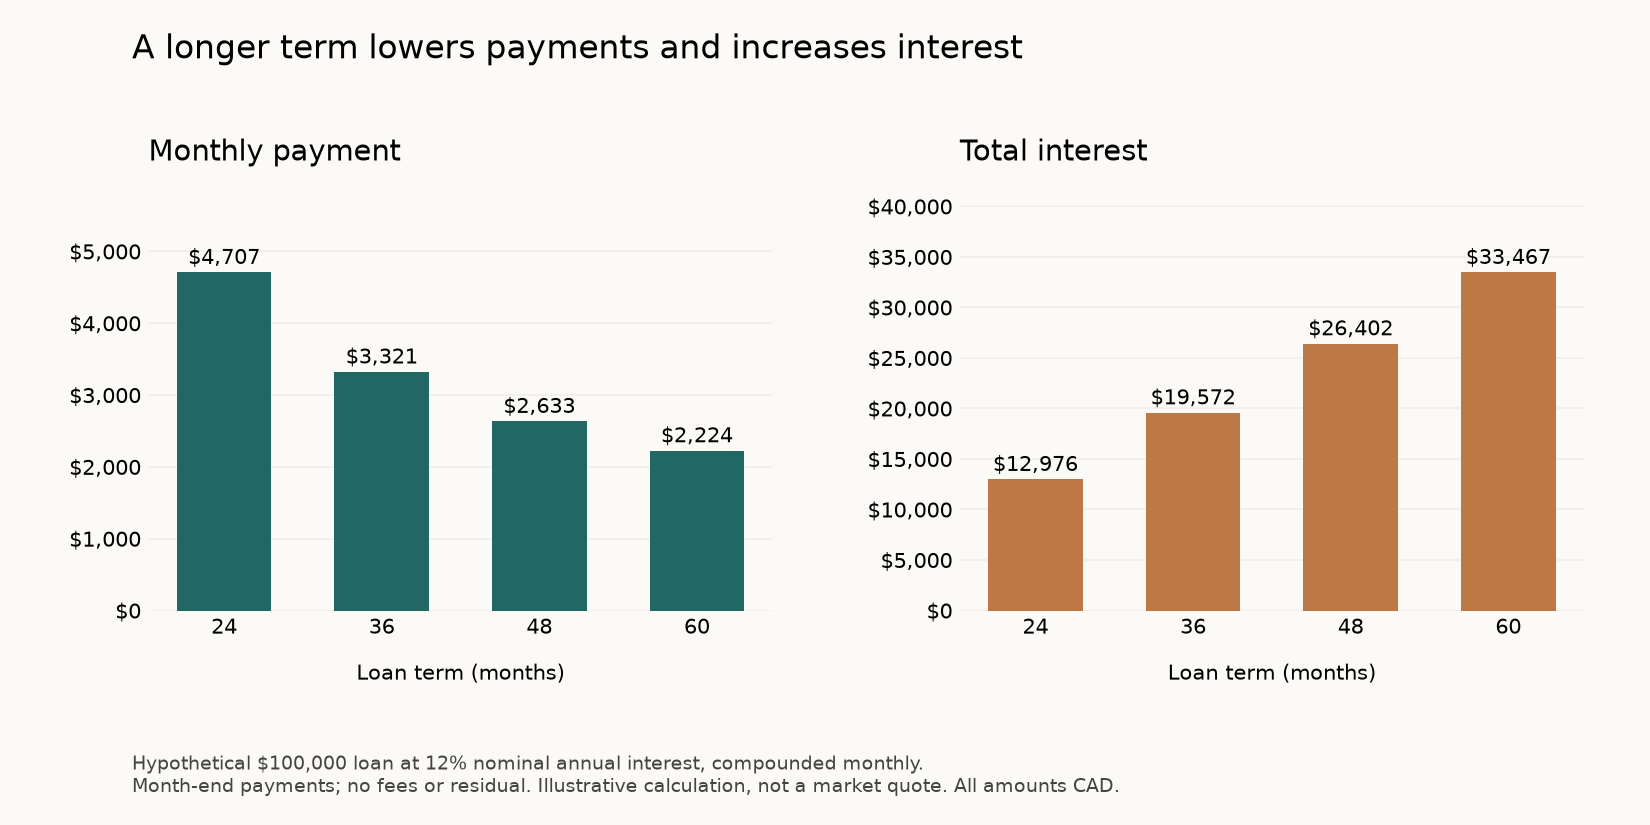
The chart rounds dollar amounts for readability; the table provides the same scenarios to cents.
Calculations use a monthly rate of 1% and the standard level-payment formula. Total interest is calculated from unrounded payments; displayed amounts are rounded to cents. Actual schedules may adjust the final payment for rounding.
In this example, extending repayment lowers the monthly commitment but leaves interest accruing for longer. That does not make the shortest period automatically suitable. A payment that consumes the operating reserve can leave the business exposed to repairs or delayed customer receipts.
The offer comparison guide helps apply the same assumptions across actual proposals. Include fees and final obligations before deciding which offer costs less.
Separate the down payment from other cash needs
Ask what contribution is required and how it is applied to the purchase. A supplier deposit, advance lease payment and refundable security deposit may have different purposes. Record each amount separately to avoid counting it twice.
The down payment guide explains the questions to ask. Do not assume a public zero-down description means the transaction requires no cash at closing or during delivery and setup.
Prepare a budget for transport, installation, insurance and initial maintenance where relevant. Confirm which costs the provider accepts for financing and which must be paid separately. Keep an operating reserve after the purchase contribution.
Check flexibility before choosing the payment
Ask for the early payout method and an example based on a possible exit date. Some agreements do not calculate payout like a simple declining-balance loan. Check fees, notice requirements and any final purchase amount.
If revenue is seasonal, discuss the expected collection pattern before requesting a structure. The seasonal payment guide provides related questions. A seasonal schedule must still be affordable over the whole operating cycle.
Review security and guarantee obligations with qualified advisers. The security registration guide and guarantee guide help identify issues that a payment comparison alone will miss.
Prepare a request that can be assessed
Provide the equipment quote, business details, current records and intended use. Identify the desired contribution and payment range, but explain the assumptions behind them. A request based only on the lowest monthly payment leaves too much unresolved.
Use the bank statement worksheet to organize the cash-flow evidence. If the equipment will support a new contract, distinguish confirmed work from forecast sales and show what happens if the start date moves.
Mehmi considers startup enquiries where the business has at least six months of revenue supported by bank statements. This does not guarantee approval or a particular term. The asset and proposed obligation still need to fit the assessment.
What we see on real files
The practical question is what remains after the payment is made. Include repairs, insurance and ordinary operating costs when assessing affordability. A lower payment can be useful, but it does not compensate for an unsuitable machine or an unresolved final balance.
Put every offer on one comparison sheet. Mark missing information as unresolved instead of entering zero. Request clarification before treating the comparison as complete.
Frequently asked questions
What is the normal equipment financing term?
There is no universal period. The equipment, remaining useful life, business and structure affect the offer. Ask for suitable alternatives and compare their complete payment schedules.
Is a longer term always more expensive?
With the same principal and positive interest rate in the illustrated fully amortizing loan, a longer period increases total interest. Actual offers may differ in rate, fees and residuals, so compare the complete terms.
Does a larger down payment guarantee approval?
No. It reduces the amount requested when applied to the price, but the provider still assesses the business and transaction. Do not exhaust necessary working capital solely to increase the contribution.
Can used equipment receive financing?
It may be considered, subject to the provider's assessment of the machine, seller and business. Prepare condition and ownership evidence and ask how remaining useful life affects the proposed schedule.
Tools and next steps
Use the financing calculators and loan and lease cost comparison to prepare consistent scenarios.
To review an equipment financing request, contact Mehmi or call 1-833-863-4644.
Sources
- Province of Manitoba, Lease or Buy: The Best Equipment Option, reviewed November 2026. General cash-flow comparison framework.
- Innovation, Science and Economic Development Canada, Buying or leasing a vehicle, reviewed November 2026. General comparison concepts; commercial terms remain contract-specific.
Written by Jodhbir Mehmi. Reviewed under our editorial standards. Updated November 2026.