

Quick answer: A Canadian lease-versus-buy tax comparison starts with the actual contract and the business's tax position. Lease costs, capital cost allowance and eligible borrowing costs follow different rules. Compare the full cash schedule, the timing of usable deductions and the equipment's value at the end. A larger deduction does not automatically mean a cheaper transaction or more cash available today.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Reviewed November 11, 2026. By Jodhbir Mehmi. Read our editorial standards.
Key takeaways
- Send the final agreement to your accountant, not just the monthly payment quote.
- Separate cash payments from deductions and estimated tax reductions.
- Use the same equipment, ownership outcome and comparison period.
- Keep proposed incentives separate from rules confirmed for your transaction.
Identify what you are acquiring
Begin with the supplier invoice and proposed agreement. A cash purchase, purchase financed by a loan and lease can provide access to the same machine, but their payment schedules and rights differ. Record who owns the equipment, whether there is a purchase option and what happens if you exit early.
The CRA's leasing-cost guidance describes deducting lease payments incurred for business property. It also describes a joint election that can treat qualifying leased property as purchased with borrowed money. That election has conditions and filing requirements. It is not a choice to make by changing a bookkeeping label.
Ask your accountant to document the treatment appropriate to your entity and contract. An equipment salesperson can explain the payment structure, but cannot establish your tax result by calling the agreement an operating lease or a capital lease. Financial-statement treatment and income-tax treatment need separate review.
Keep three schedules separate
The first schedule is cash. List deposits, instalments, fees, service payments and any final purchase amount on the dates they are due. For a purchase financed by a loan, distinguish the equipment price from the lender's repayment schedule. Do not count both as separate costs without also accounting for the loan proceeds.
The second schedule is deductions. The CRA's CCA overview explains that depreciable property is generally handled through capital cost allowance rather than simply deducting the purchase price. The actual claim depends on the applicable rules. Your accountant should establish the class, dates, use and any eligible special treatment.
The third schedule is the estimated tax effect. A deduction reduces the income on which tax is calculated; it is not automatically an equal cash refund. Its value and timing depend on the business's circumstances. Keep the tax payment forecast separate from the financing payment forecast so an expected future benefit does not hide a near-term shortage.
Understand a deduction before comparing two offers
Suppose, purely for illustration, that an accountant confirms a $10,000 deduction can be used immediately and that each dollar reduces tax by an assumed 25 cents. The estimated reduction is $2,500, not $10,000. If the related cash expense is $10,000, the simplified net cost is $7,500 after that reduction. The assumed rate is not a Canadian tax-rate quote.
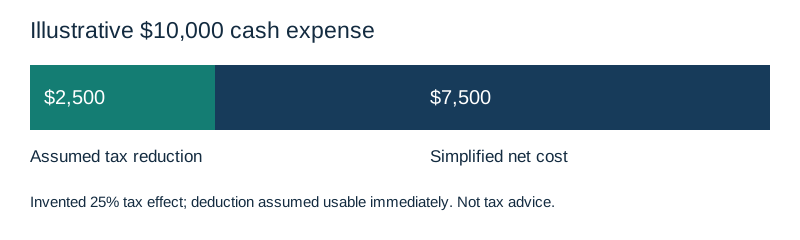
| Item | Assumption or result |
|---|---|
| Cash expense | $10,000 |
| Deduction assumed usable now | $10,000 |
| Assumed tax effect per dollar | 25% |
| Estimated tax reduction | $2,500 |
| Simplified net cost | $7,500 |
This example does not establish that a particular lease payment or equipment purchase is deductible. It explains the arithmetic after eligibility and timing have been established. If the business cannot use the deduction in the assumed period, the cash comparison changes. Ask the accountant to model the actual situation rather than applying a headline rate to every payment.
Compare the same equipment and end position
A lease ending with a return and a purchase ending with an owned machine are not equivalent outcomes. Include the equipment's estimated value at the comparison date, or compare the cost of reaching the same ownership position. Use a supportable resale estimate and a lower-value scenario rather than assuming the machine retains a fixed percentage.
Check whether service, insurance and installation are included consistently. A lease package containing maintenance cannot fairly be compared with a bare purchase price unless the ownership option includes an appropriate service allowance.
Use the same operating period. If one quote runs longer, show the remaining obligation at the chosen comparison date. A smaller monthly amount can simply reflect more months or a larger final payment. The lease, loan and cash comparison covers those commercial differences.
Review timing before making a year-end commitment
Give the accountant the acquisition, delivery, installation and intended operating dates. A signed order and a machine ready for use are different milestones. Do not assume that paying a deposit by year-end establishes the deduction you expect.
Ask which rules apply to the specific property and relevant dates, including any available-for-use conditions. If a supplier's delay moves installation, request an updated comparison. The finance agreement may still create payments even though the original tax forecast no longer fits.
Keep an ordinary cash forecast that works without an unconfirmed incentive. A proposal, announcement or supplier summary should not be entered as an assured benefit. Ask your tax adviser to identify the enacted rule and applicable conditions before including an incentive in the decision.
Separate income tax from sales-tax cash flow
Ask the accountant how GST/HST and any applicable provincial taxes affect the transaction. Record amounts due, any recoverability the adviser confirms and the expected timing. Do not subtract a recovery from the day-one cash requirement if the business must first pay it and recover it later.
Use consistent gross or net figures across the comparison. If one equipment quote includes taxes and the other excludes them, the apparent cost difference may be a presentation issue. The same problem arises when installation or documentation charges appear only in the final agreement.
Include the exit, not just the first deduction
Ask what happens if you sell, trade, return or buy out the equipment. Request both the commercial settlement and the tax review. A payout statement answers what the financing provider requires; it does not by itself answer the reporting consequences.
Keep the original cost records, prior claims and proposed proceeds available for the accountant. A useful model includes the full ownership period and the intended exit. Choosing solely on the largest first-year deduction can overlook costs that arrive when the equipment is replaced.
Prepare a useful accountant review package
Bring the final supplier quote, financing schedules, purchase-option terms and expected use. Identify the legal business entity, location, existing equipment being traded and any personal use. Include a realistic cash forecast rather than only the busiest month's sales.
Ask for the result in two parts: the treatment the adviser considers supportable and the commercial assumptions that could change. For example, the deduction treatment might be settled while resale value remains uncertain. Keeping those uncertainties separate makes the comparison easier to update.
Frequently asked questions
Is leasing always better for tax?
No. The contract, deductible amounts, timing, tax position and full cost all matter. Compare the actual alternatives rather than selecting the largest apparent deduction.
Can I deduct a loan payment as an equipment expense?
Do not treat the whole repayment as a current equipment expense. Have your accountant separate principal, eligible borrowing costs and the applicable equipment deductions.
Does accounting depreciation equal CCA?
No. They serve different reporting purposes. Ask for a tax schedule alongside the financial-statement treatment.
Can a proposed incentive decide the purchase?
Model it separately until the adviser confirms the applicable rule and eligibility. The business should understand its cash commitment without assuming an unconfirmed benefit.
Tools and next steps
Use the leased-equipment CCA guide to prepare contract questions. Review the capital and operating lease comparison when separating accounting terminology from the commercial agreement.
For equipment financing options to take to your accountant, contact Mehmi Financial Group or call 1-833-863-4644. Bring comparable supplier quotes and your intended ownership period.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Sources
- CRA: Leasing costs, updated August 31, 2026.
- CRA: Claiming capital cost allowance, updated August 31, 2026.
- Sources reviewed November 11, 2026. The graph uses invented assumptions, not a tax assessment. No proposed incentive is included as an enacted benefit.