

Quick answer Compare equipment sales tax across Canada before financing a purchase. Ordinary taxable equipment attracts GST/HST and, in B.C., Saskatchewan, Manitoba or Québec, a separate provincial tax. The invoice and the tax recoverable later depend on the province, registration, equipment use and exemptions.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Last updated: November 10, 2026. Sources rechecked November 11, 2026 for 2027 purchase planning. The sales taxes described below are current law. Confirm the applicable rules again when the transaction occurs.
Key takeaways
- Business use alone does not establish a provincial sales tax exemption.
- An out-of-province supplier's invoice can leave the buyer responsible for self-assessing tax.
- GST/HST credits and Québec QST refunds depend on registration, eligible use and supporting documents.
- Compare the cash needed at delivery with the amount recoverable later. These can be different figures.
Equipment sales tax by province and territory
The rates below apply to ordinary taxable supplies. Exempt equipment, special vehicle rules and transaction-specific relief require separate review. CRA determines GST/HST by place of supply. Provincial authorities administer their own rules for goods acquired or brought in for use.
| Province or territory | GST or HST | Separate provincial tax |
|---|---|---|
| British Columbia | 5% GST | 7% PST |
| Saskatchewan | 5% GST | 6% PST |
| Manitoba | 5% GST | 7% RST |
| Québec | 5% GST | 9.975% QST |
| Ontario | 13% HST | Included in HST |
| Nova Scotia | 14% HST | Included in HST |
| New Brunswick, Newfoundland and Labrador, Prince Edward Island | 15% HST | Included in HST |
| Alberta, Yukon, Northwest Territories, Nunavut | 5% GST | No general provincial or territorial sales tax |
Use the provincial sources below to check the equipment classification. A machine's advertised price does not establish its taxable invoice value. Ask the seller to show delivery and installation separately so your accountant can review each charge.
Tax on a $100,000 equipment purchase
This hypothetical calculation assumes an ordinary taxable machine priced at $100,000 before tax, with no exemption, trade-in, delivery charge or installation charge. Each tax uses that same base. The buyer is appropriately registered and uses the machine wholly in eligible commercial activities. Actual recovery depends on the applicable capital-property rules and supporting records.
| Destination | GST/HST | Provincial tax | Total invoice | Potential recovery under these assumptions |
|---|---|---|---|---|
| B.C. | $5,000 GST | $7,000 PST | $112,000 | $5,000 GST ITC |
| Saskatchewan | $5,000 GST | $6,000 PST | $111,000 | $5,000 GST ITC |
| Manitoba | $5,000 GST | $7,000 RST | $112,000 | $5,000 GST ITC |
| Québec | $5,000 GST | $9,975 QST | $114,975 | $5,000 GST ITC plus $9,975 QST ITR |
| Ontario | $13,000 HST | Included | $113,000 | $13,000 HST ITC |
| Nova Scotia | $14,000 HST | Included | $114,000 | $14,000 HST ITC |
| New Brunswick, Newfoundland and Labrador, Prince Edward Island | $15,000 HST | Included | $115,000 | $15,000 HST ITC |
| Alberta and territories | $5,000 GST | None | $105,000 | $5,000 GST ITC |
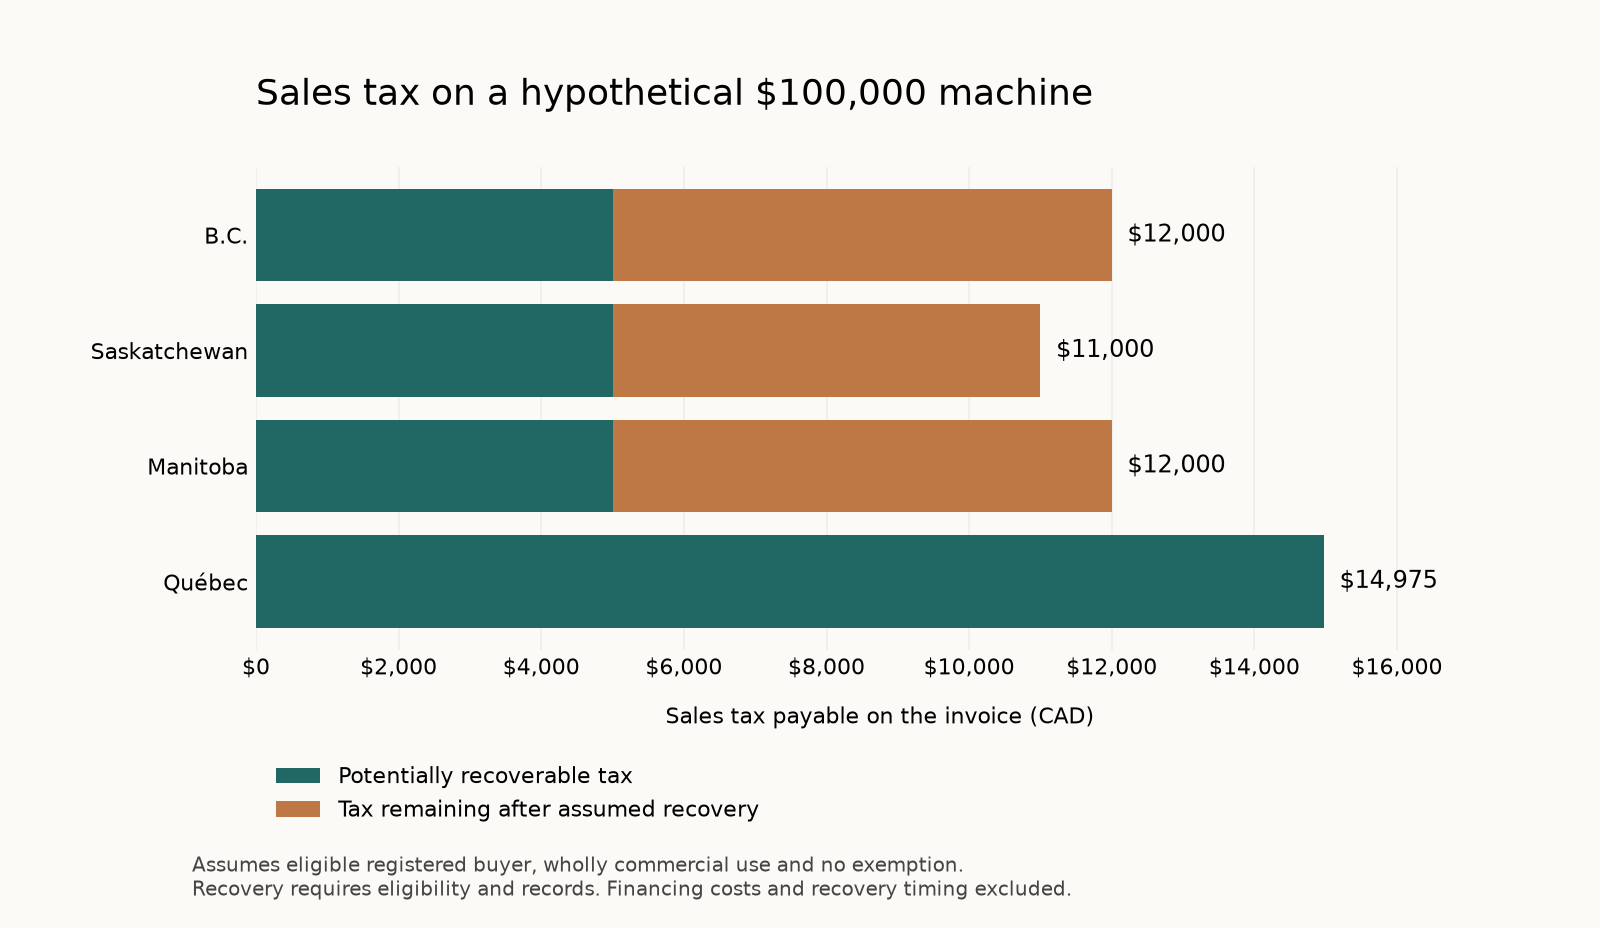
For example, the B.C. invoice is $100,000 plus $5,000 GST plus $7,000 PST. With the assumed GST credit, its cost after that recovery is $107,000. Québec's larger initial invoice can produce a $100,000 cost after both assumed recoveries. Financing costs and the timing of recovery are additional considerations. The example is hypothetical.
British Columbia equipment purchases
B.C. generally applies PST to equipment bought or leased for business use. Its guidance expressly says there are no PST input tax credits for business purchases. Unless an exemption or refund applies, include the PST in your acquisition budget.
The production machinery and equipment exemption can apply to qualifying equipment and qualifying activities. Bulletin PST 110 sets out the conditions. A manufacturer's production machine and its office furniture can receive different treatment. Identify what the equipment actually does and where it operates before claiming relief.
Ask your accountant to match the asset and its intended use to the bulletin. Confirm the exemption certificate required for your purchase with the seller and B.C. Ministry of Finance. Retain the supporting records with the invoice. A general statement that a purchase is industrial equipment leaves important eligibility questions unanswered.
B.C. also taxes taxable goods brought into the province for use. Bulletin PST 110 explains that the amount paid to bring taxable goods into B.C. can include transportation and other acquisition costs, excluding GST. Review the delivered cost when comparing suppliers.
Saskatchewan equipment purchases
Saskatchewan's 6% PST applies to taxable new and used goods consumed or used in the province, including imported purchases. If a supplier fails to collect it, the purchaser must self-assess and pay the province. Used equipment therefore needs the same tax review as a new machine.
The province's business-assets guidance distinguishes assets acquired when starting operations from subsequent purchases. It directs businesses to use a Business Assets Declaration for the former and report later purchases through the consumption-tax line of the regular PST return. Have your bookkeeper confirm the correct filing route before payment is due.
For a private sale or a business closure purchase, request a detailed invoice identifying the asset and showing any tax collected. Record the seller's details and the delivery arrangements. An invoice with no PST line is a reason to investigate the payment obligation. It does not establish exemption.
Manitoba equipment purchases
Manitoba's general RST rate is 7% on the retail sale or rental of most goods. The province calculates RST on the selling price before GST. Review the asset's classification and any exemption with Manitoba Finance or your accountant.
Keep the financing proposal beside the supplier's invoice. If the proposal covers only the equipment price, you need a separate plan for the taxes and other charges. Ask which amounts are included in the financed balance and which you must pay directly. Approval of financing does not settle the tax treatment.
When comparing an equipment loan with a rental or lease, use the complete contract. Our provincial equipment lease tax guide provides related reading, while equipment lease fees and clauses helps you identify the payment obligations to review.
Québec QST and recoverable tax
Québec generally calculates 5% GST and 9.975% QST on the selling price excluding GST. An input tax credit (ITC) concerns GST/HST. An input tax refund (ITR) concerns QST. Revenu Québec says registrants can generally recover eligible GST/HST through input tax credits and eligible QST through input tax refunds when purchases support commercial activities.
Confirm your registration status and the equipment's intended use before putting an expected refund into your forecast. Mixed use, exempt activities and special rules can affect entitlement. Keep the supplier invoice and evidence supporting the claim.
A refund claim also creates a timing question. The invoice can require payment before the credit or refund benefits your cash balance. Ask your accountant when the purchase should enter the return, then build the equipment budget around that timing. Avoid using an expected refund as cash already available for delivery.
Which tax follows equipment across provincial borders?
CRA's place-of-supply examples show that delivery and pickup arrangements can change the GST/HST charged. For provincial taxes, equipment brought into B.C. or Saskatchewan for use can create a payment obligation even when the seller is elsewhere.
Before ordering, write down the seller's location, delivery address and intended operating locations. Give this information to the seller and accountant. If a machine will move between jobs, retain a location log and ask about temporary-use rules before the move. The treatment of a mobile asset requires more detail than its owner's mailing address.
Compare supplier quotes using the same delivery assumptions. A local delivered quote and an out-of-province pickup quote may cover different transport costs and tax obligations. Keep the freight quote with the equipment quote so both can be reviewed together.
Build a tax-aware purchase budget
Use a worksheet that separates money due, money financed and any recoverable tax. This prevents a low base payment from hiding a substantial delivery-day cash requirement. Enter the amounts from the actual documents after your accountant confirms the tax treatment.
| Budget line | Evidence to obtain | Question to resolve |
|---|---|---|
| Equipment price | Itemised supplier invoice | Does it identify the correct asset and buyer? |
| Freight and installation | Separate charges or supplier breakdown | Which charges enter the taxable amount? |
| GST/HST and QST | Invoice and registration records | What is recoverable, and when? |
| PST or RST | Invoice, exemption support or self-assessment calculation | Who collects or remits the tax? |
| Financing contribution | Written financing terms | Which invoice amounts are funded? |
| Cash due from buyer | Reconciled closing statement | What must clear before delivery? |
Our equipment financing cost calculator guide helps organise the payment comparison. Review zero-down equipment financing carefully if a quote uses that wording. Ask explicitly about taxes, deposits and fees before treating the cash requirement as zero.
What we see on real files
The useful financing conversation starts with a complete supplier quote and a clear description of where the equipment will work. A missing tax line creates another question to resolve before funding. Bringing the invoice, intended use and accountant's tax treatment together helps everyone work from the same acquisition cost.
For the application itself, use our equipment financing document checklist. Keep tax eligibility questions with your accountant and confirm the financing contribution in the written offer.
How buying and leasing change the timing
A financed purchase still involves a purchase invoice. Confirm how its taxes are funded. A lease can have tax payable as lease amounts become due, subject to the province and contract. B.C.'s current guidance explicitly links tax on written leases to the payment obligations under the agreement.
Compare the deposit, regular payments and end-of-term obligations, including their applicable taxes. Ask for a written breakdown of any buyout. A lease can spread payments while still leaving charges at signing or termination.
Read GST/HST on equipment leases alongside the provincial rules. If you also need an income-tax comparison, see leasing versus financing tax considerations with your accountant. Sales tax recovery and income-tax deductions require separate calculations.
Frequently asked questions
Does buying used equipment avoid PST?
Used status alone does not establish exemption. Saskatchewan expressly includes new and used goods. Review the relevant province's rules and retain a proper invoice even when buying from a private seller.
Can I recover all the tax on a business machine?
Eligibility depends on the tax system, registration and use. CRA lists equipment among capital purchases that may qualify for GST/HST credits. Québec has QST input tax refunds. B.C. expressly provides no general PST input tax credit for business purchases.
Does an Alberta supplier make my purchase PST-free?
Equipment brought into a province that taxes its use can still attract provincial tax. Check both the seller's invoice and your own self-assessment obligations before comparing the final cost.
Is manufacturing equipment automatically exempt?
Review the specific exemption and its conditions. B.C.'s production machinery bulletin provides qualifying rules. Keep written support for your equipment's function and use, and confirm the required documentation before the sale.
Can financing include the sales tax?
Ask for the funded amounts in writing. The financing offer determines what the provider will fund. Your accountant determines the tax treatment, and the purchase documents establish what must be paid.
Tools and next steps
Prepare the equipment quote, delivery details and intended-use description for your accountant. Request confirmation of the applicable taxes, exemption evidence and recovery eligibility. Then reconcile the invoice against the proposed financing and your available cash.
Our equipment financing overview and B.C. financing guide explain the funding discussion. For another structure to compare, review equipment loans and equipment leases. Use the same invoice and delivery assumptions for both proposals so the comparison remains meaningful.
Discuss your equipment financing
Mehmi Financial Group works with over 50 lenders. Share your equipment quote and operating location to discuss financing options, subject to review and terms. Startups need 6 or more months of revenue shown in business bank statements. Call 1-833-863-4644 or contact us.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Sources
Official guidance accessed November 11, 2026. These sources describe current law and administrative guidance for planning purchases in 2027.
- Canada Revenue Agency, Which rate to charge.
- Canada Revenue Agency, Types of purchases and expenses, September 15, 2016.
- British Columbia, Provincial sales tax.
- British Columbia, PST frequently asked questions.
- British Columbia, Bulletin PST 110, Production Machinery and Equipment Exemption.
- British Columbia, Charging and collecting PST, September 18, 2026.
- Saskatchewan, Provincial Sales Tax.
- Saskatchewan, Pay PST on Your Business Assets.
- Manitoba Finance, Retail Sales Tax.
- Revenu Québec, Basic Rules for Applying the GST/HST and QST.
- Revenu Québec, Input Tax Credits and Input Tax Refunds.
Written by Jodhbir Mehmi. Reviewed under our editorial standards. Updated November 2026.