

Compare Canadian equipment leasing companies by the terms they will offer for your actual purchase: equipment eligibility, cash required, payment schedule, fees and end-of-term obligations. This guide uses seven checks to evaluate a shortlist. A familiar company name or a low advertised monthly payment does not establish the best fit for your business.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Key takeaways
- Request comparable written quotes for the same equipment and intended outcome.
- Confirm who owns the equipment and who will service the agreement.
- Add fees and the purchase option when comparing the cost of ownership.
- Review early payout, return and renewal requirements before signing.
- Keep enough cash available for installation, operating expenses and a slower month.
Use seven checks to evaluate your shortlist
Mehmi Financial Group arranges commercial financing and publishes this guide. The worksheet below evaluates an offer for a particular business and purchase. It does not rank providers or claim that one company is best for every applicant.
Start with a short purchase brief. Record the equipment description, supplier, price, condition and required delivery date. Explain whether your business intends to keep the equipment for its working life or replace it after a defined period.
Give each provider the same starting information. If a quote changes the contribution, term or final purchase amount, record the difference. Those changes may be useful, but they need to remain visible when you compare the offers.
| Check | Ask for | Decision it supports |
|---|---|---|
| 1. Equipment fit | Confirmation that the exact asset and seller can be considered | Whether to proceed with an application |
| 2. Transaction roles | Identity of the lessor, arranger and servicing contact | Who is responsible at each stage |
| 3. Cash required | All amounts due before delivery and during the term | Whether the budget is workable |
| 4. End-of-term choices | Written purchase, return or renewal conditions | Whether the agreement matches your equipment plan |
| 5. Early changes | Payout, transfer and replacement provisions | How an unexpected business change would be handled |
| 6. Funding process | Remaining documents and approval conditions | Whether delivery timing is realistic |
| 7. Ongoing service | Contacts, notice procedures and account access | How you will manage the agreement |
1. Confirm the equipment and seller fit
Ask whether the provider will review the specific transaction before spending time on a detailed application. Describe whether the equipment is new, used, refurbished or being purchased privately. Include the model, year and serial number when available.
For a used machine, obtain service information and an independent inspection where appropriate. Ask what evidence the provider needs about ownership, condition and value. Confirm whether the seller can supply the invoice and payment details required to complete the transaction.
Separate the equipment price from transport, installation, accessories and other costs. Ask which items can be included in the financing request. Any item left outside the agreement still needs a place in the business's purchase budget.
Check that the machine can perform the intended work and that your premises can accommodate it. A financing quote cannot replace a technical inspection or a review of the installation requirements. Resolve equipment questions with the supplier and appropriate specialist.
2. Understand each company's role
Ask who will own the leased equipment and be named in the agreement. If you are speaking with an intermediary, ask who receives the application and who makes the financing decision. Obtain a clear explanation of any arranging fee and when it becomes payable.
The Competition Bureau's Canadian SME financing study distinguishes financial institutions, other providers and intermediaries in the market. For your transaction, establish the actual roles through the written proposal. A company's marketing description alone may leave important responsibilities unclear.
Confirm the contact for changes before funding and the contact for questions after funding. Keep the legal company name, agreement number and service details in your records. Ask how to request an account statement or a payout calculation.
Read the consent documents before submitting financial information. Ask which parties will receive the file and how to provide sensitive records securely. Coordinate submissions so each provider receives accurate, current information about the purchase.
3. Compare all required payments
Ask for the number of payments, their amount and their due dates. Identify any amount required at signing and confirm whether it is included in the stated payment count. Record documentation charges and other mandatory fees separately.
If ownership is your goal, include the contractual purchase amount in the comparison. Where that amount depends on a future valuation, label it as unknown. Ask how the valuation is determined and whether there is a process for resolving disagreement.
The following figures are hypothetical and are not available offers. Both examples assume 36 monthly payments and no additional initial payment. They compare stated payments, fees and a fixed purchase option only. They exclude applicable sales taxes, insurance, maintenance and other operating costs.
| Illustrative item | Offer A | Offer B |
|---|---|---|
| Monthly payment | $950 | $1,050 |
| Number of payments | 36 | 36 |
| Total scheduled payments | $34,200 | $37,800 |
| Assumed fee | $300 | $200 |
| Fixed purchase option | $5,000 | $1,000 |
| Total of these stated amounts | $39,500 | $39,000 |
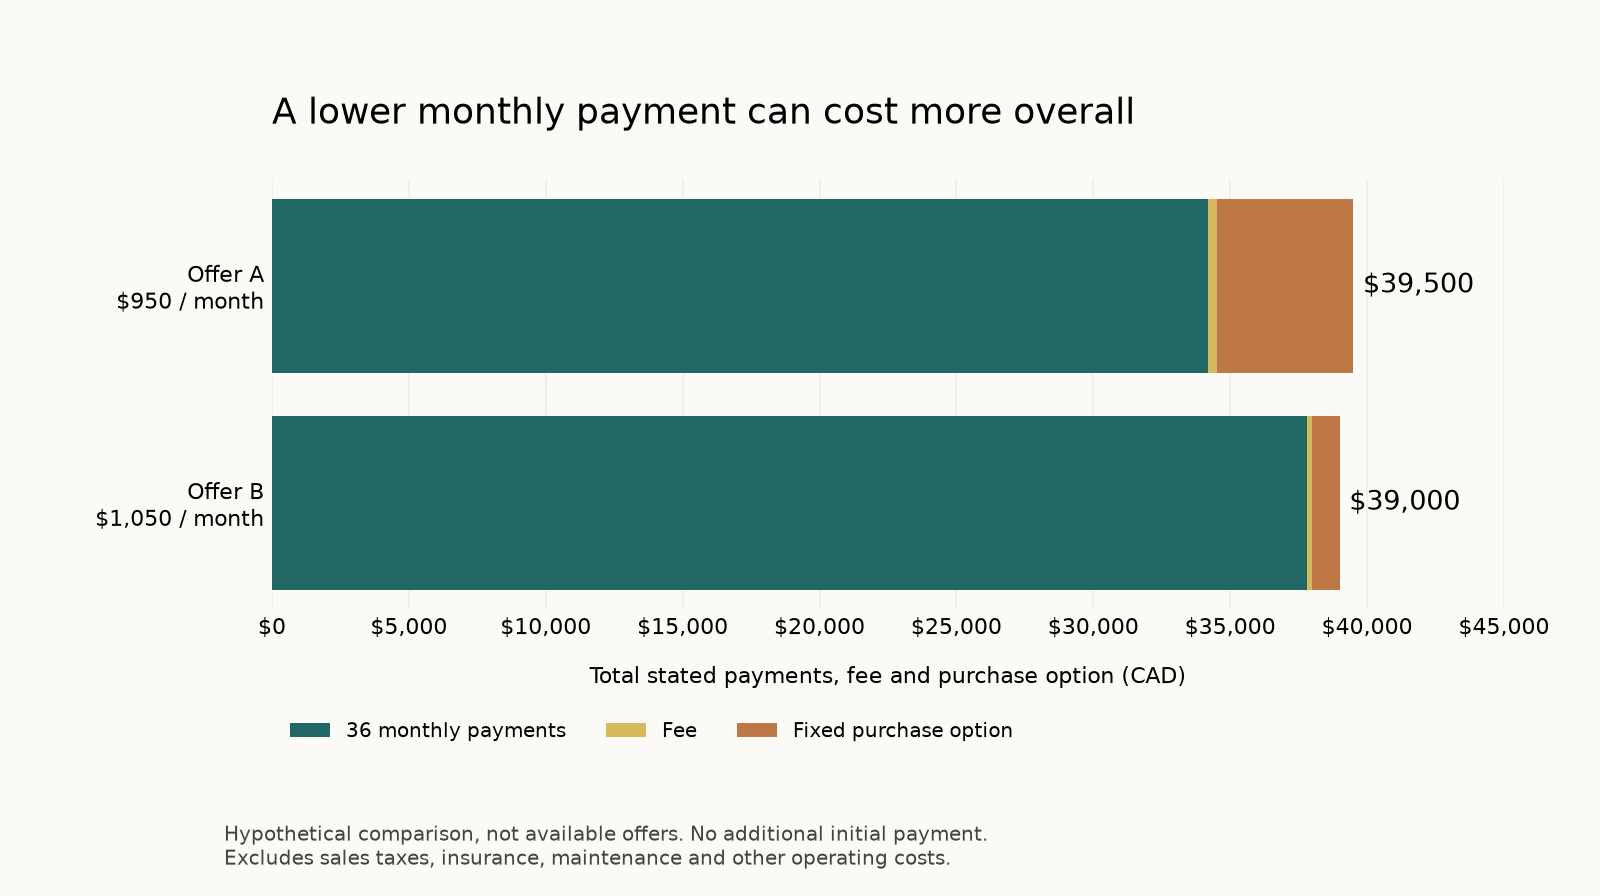
Offer A requires $100 less each month but totals $500 more under these assumptions. The worksheet does not establish which offer a business should choose. Consider when the cash is due, whether the final purchase amount is affordable and the other contractual terms.
Add the equipment's operating costs to a separate monthly forecast. Include the cash needed before the machine begins earning revenue. Manitoba Agriculture's equipment guidance recommends cash-flow projections before deciding whether to lease or buy; apply that discipline to the specific offers you receive.
4. Read the end-of-term conditions
Start with the intended outcome. If you want to own the equipment, ask how the purchase option is exercised and what documentation confirms the transfer. Record any notice deadline and the amount due.
If you expect to return the equipment, obtain the return requirements. Ask about its required condition, permitted usage, inspection process, transport responsibility and delivery location. Budget the costs your business must cover.
Ask what happens if you miss a notice deadline or keep using the equipment after the stated term. Read any renewal provision carefully. Put the relevant dates in a shared calendar when the agreement begins so they remain visible to the people managing the equipment.
A planned upgrade also needs a disposal or return plan for the existing unit. Compare the new purchase date with the old agreement's end date. Include any overlapping payments in the cash forecast.
5. Check early payout and business changes
Ask how an early payout would be calculated and request a worked example using an agreed point in the term. Clarify whether any fees or other amounts would be added. A verbal statement that you can pay out early leaves the cost unanswered.
Read the rules for selling, transferring or relocating the equipment. If a business sale or ownership change is possible, ask how the agreement addresses it. Obtain professional advice on obligations that could remain with the business or a guarantor.
Review the response to damaged equipment, interruption of operations or a missed payment. Ask your insurance adviser to check the required coverage. Keep the insurance obligations and claims contact details with the financing documents.
6. Make the funding process concrete
Ask for a list of remaining conditions and who is responsible for each one. This may include the final invoice, equipment identification, insurance or signed documents. Confirm which items the supplier must provide.
Distinguish an initial discussion from a written approval and from an agreement ready to fund. Request an update when conditions change. Avoid committing to a delivery date based only on an estimated approval timeline.
For startup applications through Mehmi, prepare six or more months of revenue in business bank statements. The complete application and equipment request still need assessment. There is no guaranteed approval based on meeting that starting requirement.
Check the supplier's deposit and cancellation terms before paying. Align the delivery, inspection and acceptance steps with the financing process. If something arrives incomplete, document it and clarify the next step before signing a statement that says otherwise.
7. Assess service after funding
Ask how to access statements, update payment details and request changes. Confirm where formal notices must be sent. An ordinary service email may not satisfy the notice method described in the agreement.
Keep a complete copy of the executed documents and supporting schedules. Record the final equipment identification and supplier invoice. Assign someone to track the payment schedule, insurance renewals and end-of-term dates.
What we see on real files
A useful comparison file shows the same purchase alongside each offer's assumptions. Put the cash contribution, payment count, final purchase amount and remaining conditions on one page. An unanswered question should remain marked as unresolved until a written response arrives.
If one proposal changes after inspection or credit review, update the comparison before deciding. Keep the earlier version for reference, but use the current written terms in the budget. The business needs to understand the agreement it is actually being asked to sign.
Frequently asked questions
Which equipment leasing company is best in Canada?
Evaluate written offers for your equipment, business and intended ownership outcome. A national ranking cannot tell you what a provider will approve or what the final contract will require.
Should I choose the lowest monthly payment?
Check the full schedule and end-of-term amounts first. A lower payment can be paired with a larger final purchase obligation. Confirm that both the monthly cash flow and the eventual outcome fit your plans.
Can I obtain a quote for used equipment?
Ask about the exact asset and seller. Prepare identification, condition and ownership information, and request the provider's document checklist. Eligibility depends on its assessment of the transaction.
Can I change equipment during the lease?
Read the replacement, transfer and payout provisions. Obtain written permission and costs where required before arranging a sale or upgrade. The supplier's willingness to trade equipment does not settle the existing agreement.
What should I keep after signing?
Retain the executed contract, schedules, invoice, equipment identification, insurance records and service contacts. Record payment and notice dates in a place the people managing the asset can access.
Tools and next steps
Use our equipment leasing comparison guide and provider selection guide to prepare questions. Review lease versus buy, purchase-option structures and early lease exit for related decisions.
Prepare records with the financing document guide. Explore equipment leases, equipment loans and the equipment financing calculator for an illustrative payment estimate.
Discuss a written equipment proposal
Call Mehmi Financial Group at 1-833-863-4644 or contact us with the supplier quote and your intended ownership plan to discuss equipment financing.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Sources
- Competition Bureau, Market study notice: competition for financing to SMEs, January 12, 2026.
- Manitoba Agriculture, Lease or Buy: The Best Equipment Option, accessed November 11, 2026.
Written by Jodhbir Mehmi. Reviewed under our editorial standards. Updated November 2026.