

Quick answer: Equipment financing can involve deductible business costs in Canada, but the whole payment is not automatically deductible. For a financed purchase, qualifying interest and capital cost allowance are considered separately; repayment of loan principal is not a business expense deduction. Eligible lease costs may be deductible under the applicable rules. Have your accountant review the agreement, business use, equipment classification and timing before estimating the tax effect.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Reviewed November 11, 2026.
Key takeaways
- Separate cash payments from tax deductions.
- Distinguish loan principal, interest and the equipment's capital cost.
- Review lease treatment using the actual agreement, not its marketing label.
- A deduction reduces taxable income; it does not reimburse the purchase price.
Start with the transaction you actually signed
Gather the purchase invoice and financing agreement before asking what is deductible. A loan used to purchase equipment, a lease for use of equipment and a later purchase of a leased asset are different transactions. The monthly payment alone does not reveal the treatment.
Identify the business that acquired or leased the asset and the way it is used. If a related person paid a deposit or the invoice names a different entity, have your accountant resolve that discrepancy. Do not assume all paperwork can be treated as interchangeable because the equipment serves the same operation.
Our equipment loan and lease comparison covers the commercial questions. The tax review should then apply the relevant rules to the documented arrangement.
For a loan, separate principal from interest
CRA's business-expense guidance distinguishes interest from repayment of the amount borrowed. The principal portion of a loan payment is not deductible as a business expense. Qualifying interest on borrowing used to earn business income may be deductible, subject to the applicable conditions and limits.
Request a payment schedule or annual statement that separates the amounts. If you record the full withdrawal from the bank account as an expense, your books can overstate operating costs. If you record none of it, you may omit an interest amount that needs review.
For an invented illustration, suppose a $1,200 payment consists of $950 principal and $250 interest. The payment removes $1,200 from the bank account, but that does not make $1,200 deductible. The $250 interest component needs its own eligibility review, while recovery of the equipment's capital cost is considered separately. These numbers describe one hypothetical payment, not a quoted financing rate.
Capital cost allowance addresses the asset cost
CCA is the tax mechanism used to deduct eligible depreciable capital property costs under the applicable rules. It is separate from the loan's repayment schedule. Paying a loan off faster does not, by itself, establish a larger CCA entitlement.
The equipment's classification matters. A truck, computer and specialized production machine should not all be assigned the same rate simply because they were financed. Give your accountant the detailed asset description, acquisition records and information about when it became available for use.
First-year deductions can depend on acquisition and availability dates, asset characteristics and current legislation. This guide does not provide a universal first-year percentage. Use the Canadian equipment CCA guide to prepare classification questions, then have the claim calculated for the relevant return.
Keep the asset record even after the financing ends. A later sale, trade-in or change in use may affect the tax calculation. The original cost and prior claims remain relevant beyond the final scheduled loan payment.
For a lease, review the agreement and conditions
CRA says leasing costs for property used in the business can be deducted, with specific limitations applying to certain property. Its guidance also describes an election for qualifying leases to be treated as combined principal and interest payments. That election has conditions and should not be assumed to apply automatically.
Ask your accountant whether the agreement is treated as a lease, a purchase arrangement or another transaction for tax purposes. A label such as capital lease, finance lease or dollar buyout is not enough information to calculate the return. Accounting presentation and income-tax treatment are separate reviews.
Provide any purchase option, prepaid amount, deposit and end-of-term charge. Explain whether an amount is refundable, applied to payments or paid to acquire the asset. Avoid combining those items into one deductible leasing total without checking their treatment.
Our dollar-buyout lease guide explains the contractual questions that often accompany this discussion.
Use a document-based deduction worksheet
| Amount in your records | Question for the accountant | Supporting document |
|---|---|---|
| Purchase price | What belongs in the capital cost and which class applies? | Detailed supplier invoice |
| Loan payment | How much is principal and how much is qualifying interest? | Financing statement or schedule |
| Lease payment | What treatment applies to this agreement? | Complete signed lease |
| Upfront fee | What is the fee for and over what period is it recognized? | Fee invoice and contract wording |
| Deposit or buyout | Is it refundable, applied to rent or part of an acquisition? | Receipt and option terms |
Include the dates as well as the amounts. A year-end bank withdrawal can relate to another period or to a deposit rather than a current expense. Good records let the accountant determine the treatment without reconstructing the arrangement from payment descriptions.
Keep business use and other adjustments visible
CRA's business guidance excludes personal expenses. If equipment has mixed use, maintain the records needed to support the business portion. Do not assume that financing in a business name establishes exclusive business use.
Tell your accountant about rebates, assistance and recoverable sales taxes. Those items can affect the relevant expense or asset-cost calculation. Avoid counting an amount twice by including it in a deduction while also treating it as recovered elsewhere.
Separate financing charges from service and insurance costs in the supplier package. A combined monthly invoice may contain items with different treatment. Ask for a breakdown rather than assigning one category to the whole amount.
Understand what a deduction is worth
A deductible amount reduces the income subject to tax under the relevant rules. It is different from a dollar-for-dollar tax credit and different from cash returned by the equipment seller. The practical benefit depends on the taxpayer's circumstances and when the deduction can be used.
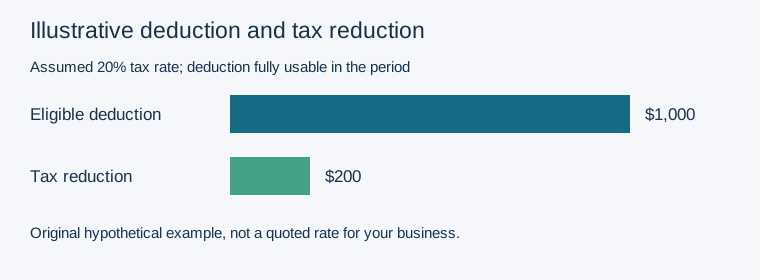
As a simplified hypothetical example, a $1,000 eligible deduction at an assumed 20% applicable tax rate would reduce tax by $200 if fully usable in that period. It would not return $1,000. The assumed rate is an illustration only, not a Canadian rate quoted for your business.
Compare financing choices before and after the accountant's tax estimate. Include the same equipment use period, initial cash, fees and end-of-term outcome. A larger deduction does not necessarily compensate for a substantially higher commercial cost.
Prepare before year-end rather than rushing a purchase
Give your accountant enough time to review the acquisition and available-for-use evidence. An order, deposit, delivery and operational readiness can occur on different dates. Ask which facts matter for the specific claim instead of assuming a December payment settles the question.
Keep the business case independent of the hoped-for deduction. Confirm that the equipment is needed, suitable and affordable. A tax estimate should inform a sound purchase decision, not justify a machine that the operation cannot use profitably.
Frequently asked questions
Can I deduct my entire equipment loan payment?
No. Principal repayment is not a business expense deduction. Qualifying interest and the equipment's CCA treatment are assessed separately.
Does every lease payment qualify in full?
Do not assume so. Business use, the agreement, applicable limitations, timing and any relevant election need review.
Does paying cash remove the CCA issue?
No. The tax treatment of a capital asset is not determined solely by whether the business borrowed to acquire it. The acquisition still needs classification and supporting records.
Can Mehmi calculate my tax savings?
Mehmi can help clarify the financing proposal. A qualified accountant or tax adviser should determine the tax treatment and estimate the effect for your business.
Tools and next steps
Collect the invoice, signed agreement, payment breakdown and business-use records. Ask your accountant to separate the capital-cost, interest, lease and fee questions before comparing the final offers.
To discuss the financing terms for a planned equipment purchase, contact Mehmi Financial Group or call 1-833-863-4644.
Disclaimer: This article is general information only and is not tax, legal or accounting advice. Tax rules change and depend on your situation. Speak with a qualified accountant or tax advisor before making any purchase or filing decision. Mehmi Financial Group does not provide tax advice.
Sources
- CRA: Business expenses.
- CRA: Leasing costs.
- CRA: Claiming capital cost allowance. Reviewed November 11, 2026.
By Jodhbir Mehmi. Read our editorial standards.