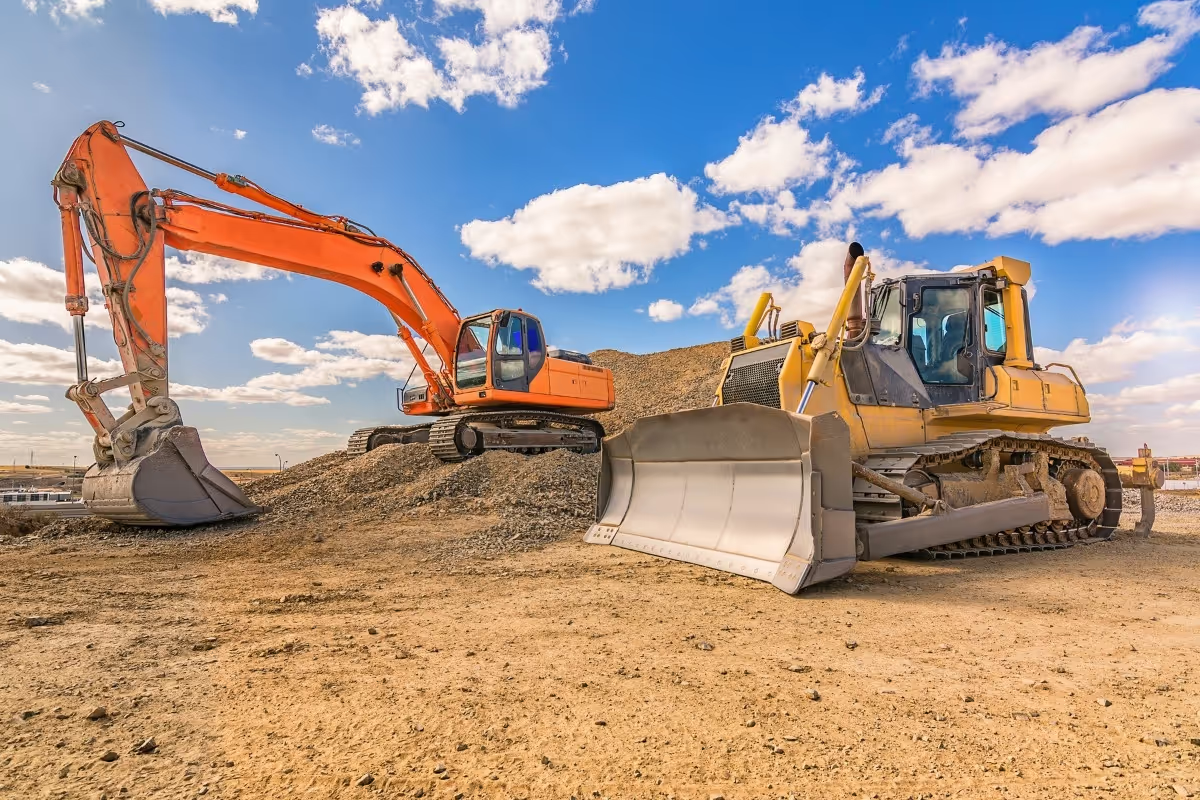
We provide equipment financing in Belleville with financing review, clear terms, and flexible structures for transportation, construction, manufacturing, agriculture, and service businesses. Used, high-mileage, and private-sale equipment is fully supported, with financing aligned to real cash-flow needs across the Bay of Quinte region.
Equipment financing in Belleville is usually strongest when it is structured lease-first: the payment should match the equipment’s earning life, the business should keep enough working capital, and the application should answer the questions an underwriter will ask before they ask them. Belleville’s Highway 401 access, rail-served industrial land, Northeast Industrial Park expansion, and local road permit rules all affect how equipment gets used, delivered, installed, and financed.
Belleville is not a generic Ontario market. The City notes that the Highway 401 corridor gives Belleville access to large markets, with three interchanges, while Highways 37 and 62 connect to northern Ontario; the City also says more than 120 million people are within a one-day drive. (belleville.ca) That matters for contractors, manufacturers, logistics firms, food processors, medical clinics, trades, agricultural operators, and service businesses buying equipment to serve both local and regional customers.
For the wider provincial context, read Mehmi’s guide to equipment financing in Ontario.
When buying or refinancing business assets in Belleville, compare the structure and total ownership cost—not just the monthly payment. Availability and terms depend on equipment, business credit, cash flow and individual lenders.
| Equipment funding need | Option to compare | What to verify |
|---|---|---|
| Purchasing eligible healthcare equipment | Equipment loan or conditional sale | Equipment value, term, interest calculation, down payment, collateral, title and early-payout terms. |
| Using equipment while managing initial cash outlay | Equipment lease | Payment schedule, deposits, insurance, end-of-term purchase options, return conditions and total cost. |
| Purchasing from a used-equipment dealer or private seller | Used-equipment financing | Asset age, hours or mileage, inspection, seller verification, lien search and any lender limits. |
| Unlocking equity in owned machinery or vehicles | Equipment refinancing or sale-leaseback | Appraised value, current liens, payout amounts, advance against value, fees and continuing use of the asset. |
| Buying multiple assets or upgrading in stages | Equipment financing facility or separate leases | Each asset's eligibility, draw timing, security, documentation, amortization and combined payment burden. |
Next step: Compare equipment loans, leases and refinancing before requesting indicative terms. Examples above are educational, not offers or approvals.
Equipment financing lets a Belleville business acquire productive assets now and pay over time while the equipment is working. The best deal is not always the lowest payment; it is the structure that protects cash flow, fits the equipment, and gets funded without surprises.
In Belleville, equipment financing can cover construction equipment, commercial vehicles, trailers, shop tools, forklifts, restaurant equipment, medical and dental equipment, manufacturing machinery, IT hardware, compressors, generators, packaging equipment, and agricultural equipment. BDC describes equipment financing as funding that helps companies buy or lease tangible long-term assets such as machinery, vehicles, hardware, and equipment that benefit the business over several years. (BDC.ca)
Most Belleville businesses should start by asking five questions:
Does the equipment create revenue, reduce costs, or replace failing capacity
Will the payment still work in a slower month
Is the asset easy to identify, insure, value, and resell
Is the seller or vendor properly documented
Does the term match the useful life of the equipment
For a full foundation on lease structures, see Mehmi’s equipment leasing in Canada guide.
Leasing is often the better starting point because it keeps cash available for payroll, inventory, fuel, HST timing, insurance, installation, and growth. A business can be technically profitable and still get squeezed if too much cash leaves on day one.
A Belleville contractor buying a used skid steer, a manufacturer adding a CNC machine, or a clinic upgrading diagnostic equipment may all benefit from spreading cost over time. The structure can be adjusted through term, down payment, end-of-term option, seasonal payment design, bundled soft costs, or a master lease for repeat purchases.
My practical opinion: paying cash is overrated when it leaves the business fragile. If an owner spends $95,000 cash on equipment and then struggles with payroll, materials, or HST, the “debt-free” decision was not actually conservative. The conservative decision is the one that keeps the business liquid and the equipment productive.
For a direct comparison, read Mehmi’s equipment lease vs bank term loan Canada guide.
Local details matter because equipment does not operate inside a spreadsheet. In Belleville, transportation access, industrial land, permits, rail proximity, and installation rules can all affect approval quality.
The first local factor is Belleville’s Highway 401 positioning. If a business serves clients in Kingston, Quinte West, Prince Edward County, Napanee, Peterborough, Oshawa, or eastern Ontario, the utilization story can be stronger than a file built only around one local customer.
The second factor is industrial growth. Belleville’s Northeast Industrial Park expansion is located south of Highway 401, east of Cannifton Road, and north of the Canadian National Railway corridor; the City says the expansion is intended to add serviced and zoned industrial land for a growing manufacturing base. (City of Belleville) That matters for manufacturers, logistics operators, warehousing businesses, fabricators, and service firms financing equipment tied to a facility expansion.
The third factor is goods movement. Belleville’s Transportation Master Plan states that commercial goods movement is vital to the local economy and that industrial businesses rely on the city’s rail and road network to obtain materials and move products to market. (Open Council) For financing, that strengthens the case for assets like forklifts, trailers, dock equipment, material handling systems, racking, and production machinery when the borrower can show customer demand.
The fourth factor is road and oversize permitting. The City says an oversize or overweight permit is required for movement of oversize or overweight vehicles, indivisible loads, objects, or structures on City of Belleville roadways that exceed Highway Traffic Act limits. (belleville.ca) If you are financing heavy equipment, floats, dump trailers, cranes, delivery trucks, or large machinery, the lender may care about whether the equipment can legally move to job sites or be delivered to your facility.
Are you looking for a truck Look at our used inventory (https://www.mehmigroup.com/inventory).
For larger assets, compare your plan with Mehmi’s heavy equipment financing Canada guide.
Most business-use equipment can be financed when the asset is identifiable, insurable, useful, and properly documented. Lenders become more comfortable when the equipment clearly fits the borrower’s industry and has a believable repayment story.
Used equipment can be a smart choice, but only when the price, condition, ownership, and remaining useful life support the lease term. For used assets, read Mehmi’s used equipment financing in Canada before committing to a seller.
Underwriters approve files that make sense under pressure. They use credit, cash flow, collateral, industry conditions, and deal structure to decide whether the equipment is likely to be paid for.
A plain-language underwriting framework is the 5Cs of credit:
Character: Does the owner repay obligations and communicate honestly
Capacity: Can the business afford the new payment after existing obligations
Capital: Is the borrower contributing equity or keeping enough working capital
Collateral: Is the asset identifiable, insurable, recoverable, and resaleable
Conditions: Does the industry, local market, and business purpose support the request
Behind the scenes, lenders also think about probability of default, exposure at default, and loss given default. In normal language, they ask: how likely is this borrower to miss payments, how much will be owing if that happens, and how much could be recovered from the equipment
That is why a clean Belleville deal might still need a down payment if the asset is older, specialized, private-sale, or tied to a startup. It is also why a strong borrower can sometimes get a better structure even if the equipment is not perfect.
For preparation before applying, use Mehmi’s equipment financing checklist before applying.
Your payment depends on more than the interest rate. Asset age, down payment, term, buyout, fees, HST timing, vendor risk, business credit, owner credit, and bank-statement strength all influence the final offer.
As of May 2026, Canadian financing costs remain connected to the Bank of Canada rate environment. On April 29, 2026, the Bank of Canada held its target overnight rate at 2.25%, with the Bank Rate at 2.5% and deposit rate at 2.20%. (Bank of Canada) Your lease rate is not the Bank of Canada rate; it is a risk-adjusted commercial price based on the borrower and asset.
A better structure usually comes from:
strong bank deposits,
clean payment history,
equipment with broad resale demand,
reasonable term length,
organized vendor documents,
clear insurance,
enough cash left after closing, and
a business reason tied to revenue or cost savings.
A weaker structure often comes from old equipment, unverifiable sellers, thin cash flow, recent NSFs, unpaid tax balances, weak documentation, or an asset that does not match the borrower’s business.
To compare scenarios, use Mehmi’s equipment financing cost calculator for Canada and review Mehmi’s breakdown of average equipment financing rates in Canada.
Ontario’s HST can affect cash flow even when the lease payment looks affordable. The Canada-specific gotcha is that tax timing, invoice quality, and commercial-use documentation matter.
CRA’s place-of-supply guidance lists Ontario as a 13% HST participating province. (Canada) CRA also says GST/HST registrants can generally claim input tax credits for eligible expenses used only in commercial activities, subject to restrictions and documentation. (Canada)
For Belleville businesses, the practical questions are:
Is HST charged upfront or on each lease payment
Will the business claim ITCs monthly, quarterly, or annually
Does the invoice show the supplier name, tax amount, description, and registration details
Is the equipment used fully for commercial activity
Are soft costs like delivery, install, software, warranties, and training handled properly
Does the structure affect who claims CCA or lease expense treatment
Do not rely on a generic U.S. article for this. Canadian GST/HST, Ontario HST, CRA documentation, PPSA security registrations, and lease tax treatment are different.
For more detail, read Mehmi’s GST/HST input tax credits on financed equipment Canada article.
A complete file gets taken more seriously. Many delays are not caused by bad credit; they are caused by missing invoices, unclear sellers, stale bank statements, or equipment details that do not match the application.
Prepare:
business legal name and registration,
owner ID and contact details,
completed credit application,
equipment quote or invoice,
make, model, year, serial number, hours or kilometres,
vendor or seller contact information,
last 3–6 months of business bank statements,
recent financial statements for larger requests,
proof of contracts, purchase orders, or pipeline if the deal is expansion-driven,
insurance contact,
void cheque,
details of existing debts and leases, and
CRA balance or payment arrangement details if relevant.
If the equipment is being installed, Belleville’s building permit rules may also matter. The City says a building permit is formal permission to begin construction or demolition and confirms the City has reviewed plans for compliance with the Ontario Building Code, zoning by-laws, and applicable laws. (belleville.ca) If a financed machine requires renovations, electrical work, ventilation, structural changes, or a new foundation, build that timing into the funding plan.
For qualification details, read Mehmi’s equipment financing requirements in Canada.
Private sales and bruised credit can still work, but the deal must remove uncertainty. Lenders do not need perfect files; they need files that can be verified and structured responsibly.
For private-sale equipment, expect more documentation than a dealer transaction. The lender may ask for seller ID, proof of ownership, lien status, serial numbers, photos, inspection details, payout instructions, and proof the price is reasonable.
For bruised-credit files, the current story matters. A borrower with an old credit problem but strong deposits, clean recent conduct, useful equipment, and a realistic down payment may be more financeable than a borrower with average credit and weak cash flow.
The practical move is to explain issues early. A surprise NSF, undisclosed tax balance, or hidden lien near funding can damage the file more than the issue itself.
For seller-direct purchases, read Mehmi’s private sale equipment financing Canada guide. If credit is not perfect, use Mehmi’s bad-credit equipment financing in Canada guide.
Approval is not funding. A lender may approve the Belleville equipment lease but still require conditions before releasing money.
These pre-funding requirements are called conditions precedent. Common examples include signed documents, final invoice, proof of insurance, down payment confirmation, vendor verification, serial number confirmation, PPSA registration, updated bank statements, and confirmation that tax or lien issues are resolved or arranged.
After funding, covenants and monitoring depend on risk. A small lease may only require on-time payments, active insurance, and no sale of equipment without consent. A larger or riskier file may require annual financial statements, updated insurance, no unauthorized ownership changes, and confirmation the equipment remains in business use.
What triggers lender concern before a missed payment Usually patterns: repeated NSFs, falling deposits, cancelled insurance, unpaid HST or payroll remittances, surprise new debt, supplier pressure, or moving financed equipment without notice.
For companies planning multiple purchases, Mehmi’s master lease agreements for equipment Canada guide explains how repeat acquisitions can be simplified.
Illustrative example only; not a statement of a specific funded client transaction.
A Belleville-area manufacturer needed a $172,000 equipment package: a used CNC machine, tooling, delivery, installation, and air-compressor upgrades. The first request was for 100% financing over the longest possible term.
The initial file had concerns. The asset was used, the package included soft costs, installation required coordination, and the company’s bank deposits were uneven because two major customers paid on 45-day terms.
The deal improved after restructuring. The owner provided six months of bank statements, year-to-date financials, two customer purchase orders, equipment photos, serial numbers, vendor invoice, installation quote, and proof of insurance. Instead of draining cash or asking for no money down, the owner offered 10% down and kept a working-capital buffer outside the lease.
The 5Cs became clearer:
Character improved through clean recent repayment history.
Capacity improved because deposits supported the payment after existing obligations.
Capital improved because the owner contributed equity without exhausting cash.
Collateral improved because the machine had serial numbers, brand recognition, and resale demand.
Conditions improved because the equipment supported existing customer work, not speculative growth.
The deal was approved because the file made repayment and recovery understandable. The lesson: underwriters do not only approve assets. They approve a structured story.
Talk to Mehmi before committing to a Belleville equipment purchase if the asset is used, the seller is private, the deal includes soft costs, your revenue is seasonal, you are comparing multiple offers, or your credit file needs explanation.
Mehmi can help structure the lease, organize the file, compare total cost, review buyout language, flag likely funding conditions, and match the request with lenders that understand the asset. The next step is simple: gather the quote, vendor details, business name, recent bank statements, and a short explanation of how the equipment will earn or save money.
If the equipment purchase could strain operating cash, compare it with Mehmi’s working capital vs equipment financing Canada guide. If a personal guarantee is part of the approval, read Mehmi’s personal guarantee for equipment financing in Canada before signing.
Related resource: Browse our equipment financing by city directory for more local financing guides.
Related financing options include equipment loans, equipment leasing, and the eligible equipment directory.
Use these guides to compare the equipment, repayment structure and documents suited to your purchase. Links to nearby cities are intended for regional context, not as a claim that Mehmi maintains branches in each location.
When you compare lender offers, assess the financed amount, total payments, applicable taxes, fees, down payment, loan or lease end-of-term obligations and conditions in writing.
These assets may qualify for commercial financing if used for an eligible business purpose. The lender reviews the specific make, model, condition, equipment purchase price, seller and applicant's capacity to repay. Being located in Belleville does not by itself ensure approval.
Recent complete business bank statements, financial reports if requested, existing debt payments and clear explanations of large or seasonal deposits help. For this market, consider rail- or truck-delivery timing and installation requirements. Provide signed contracts or invoices where they actually exist, not assumed future sales.
Potentially. Lenders may ask for year, serial number or VIN, photos, hours or kilometres, seller ID, proof of ownership, lien confirmation and an inspection or valuation. A private sale can require more verification than a dealer purchase.
Some newer firms can be considered, but owner credit, management experience, personal guarantees, additional equity or contracts may be important. Each lender has its own eligibility requirements; acceptance is never automatic.
There is no standard deposit or guaranteed zero-down program. Borrower credit, repayment capacity, asset resale market, lender policy and requested term influence the result. Request a written quote showing upfront funds, fees and cash required at funding.
An equipment loan may better match a straightforward ownership objective. An equipment lease can have a different ownership or end-of-term structure. Compare all instalments, tax treatment, purchase options and early payout clauses.
Ontario HST treatment and input tax credit eligibility depend on the transaction and your business's tax status; confirm details with your accountant. Read the official tax guidance and budget any nonrecoverable taxes instead of comparing payments before tax.
Compare effective total cost, term, down payment, payment frequency, fees, insurance, asset ownership, residual or buyout and repayment restrictions. Estimate cash flow with a hypothetical payment calculator, then request financing options with complete equipment details.