Equipment Financing Toronto
Quick answer: Toronto businesses can request commercial equipment financing for new or used CNC machinery, construction equipment and work trucks. Mehmi Financial Group helps compare equipment loans, leasing and, where suitable, refinancing with lenders serving eligible Ontario businesses. Underwriting typically considers equipment quote, seller details, bank statements, financials and the intended operating use. Terms and availability depend on the borrower, asset, lender and transaction; service can be arranged remotely.
Compare equipment loans, equipment leasing and equipment refinancing before submitting a quotation.
Equipment Financing in Toronto: Financing Guide for Canada's Largest Business Market
Toronto is where Canadian business moves fastest and competes hardest. The construction cranes along the waterfront and Eglinton Crosstown corridor never stop. The carriers running freight out of the Port Lands and along the 400-series highways are logging kilometres before most businesses open. The fabricators and manufacturers in Etobicoke, Scarborough, and the East Harbour industrial corridor are running shifts to meet supply contracts. And across the city, in Liberty Village, the Financial District, Yonge-Eglinton, and Midtown, medical clinics, technology companies, and professional service businesses need equipment decisions that match their pace.
Approval and funding timelines vary by lender, application completeness, and required conditions. For established businesses with clean bureau histories, decisions subject to lender review on application-only files under $250,000 are common. Mehmi Financial Group is headquartered in Mississauga, minutes from Toronto's business districts, which means local familiarity with how GTA operators actually work, not a remote approval process detached from the market.
Equipment can be sourced from Toronto-area dealerships, GTA private sellers, auctions, or out-of-province. High-hour and older units qualify regularly when they continue generating stable revenue.
Use the equipment payment calculator to model monthly payments before you apply.
How to compare equipment financing in Toronto
When buying or refinancing business assets in Toronto, compare the structure and total ownership cost, not just the monthly payment. Availability and terms depend on equipment, business credit, cash flow and individual lenders.
| Equipment funding need | Option to compare | What to verify |
|---|---|---|
| Purchasing eligible manufacturing machinery | Equipment loan or conditional sale | Equipment value, term, interest calculation, down payment, collateral, title and early-payout terms. |
| Using equipment while managing initial cash outlay | Equipment lease | Payment schedule, deposits, insurance, end-of-term purchase options, return conditions and total cost. |
| Purchasing from a used-equipment dealer or private seller | Used-equipment financing | Asset age, hours or mileage, inspection, seller verification, lien search and any lender limits. |
| Unlocking equity in owned machinery or vehicles | Equipment refinancing or sale-leaseback | Appraised value, current liens, payout amounts, advance against value, fees and continuing use of the asset. |
| Buying multiple assets or upgrading in stages | Equipment financing facility or separate leases | Each asset's eligibility, draw timing, security, documentation, amortization and combined payment burden. |
Next step: Compare equipment loans, leases and refinancing before requesting indicative terms. Examples above are educational, not offers or approvals.
Why Toronto Businesses Finance Equipment Rather Than Buy Outright
Toronto's cost structure is the most demanding in Canada. Commercial real estate rates, labour costs, and operational overhead all run at a premium that leaves little room for large cash outlays on equipment. A $200,000 piece of machinery purchased outright in a Toronto industrial unit at $20–$30 per square foot, with the labour costs that come with operating in this market, can create cash flow fragility that a financing structure avoids entirely.
Beyond cash preservation, there are patterns specific to Toronto's business environment that shape how equipment financing works here:
Construction contractors across the GTA are operating at a pace driven by one of the most sustained development pipelines in North America, transit-oriented development along the Ontario Line and Eglinton Crosstown, high-density residential along the waterfront and in Midtown, and commercial and mixed-use intensification across Scarborough, North York, and Etobicoke. Project award timelines are compressed, mobilization windows are tight, and contractors who can confirm equipment in days rather than weeks have a concrete competitive advantage.
Carriers and logistics operators running freight through the GTA, from the Port of Toronto and the rail yards in Mimico and Scarborough, along the 400, 401, 427, and DVP corridors, need truck and trailer financing that works on freight contract timelines, not bank committee timelines.
Medical, dental, and wellness operators across Toronto's dense residential and commercial neighbourhoods are expanding rapidly. Equipment financing preserves working capital, makes monthly costs predictable, and allows clinics to invest in diagnostic or treatment technology that pays for itself through patient volume, without depleting operating reserves.
Technology and professional services businesses in Toronto's innovation districts, MaRS, the Financial District, King West, Midtown, often require production hardware, lab equipment, and specialized tooling on shorter cycles than traditional capital equipment. Equipment leasing options give these businesses flexibility to upgrade rather than carry depreciating assets.
Manufacturers and fabricators in Toronto's industrial corridors, Etobicoke's industrial belt, Scarborough's Golden Mile, the East Harbour redevelopment zone, and the Port Lands industrial area, supply automotive, food processing, pharmaceutical, and commercial construction sectors. Equipment tied to supply contracts has installation deadlines that a slow bank process can't accommodate.
For operators who want full ownership from day one, equipment loans provide a straightforward path, fixed payments, equity build, and refinancing options when working capital is needed.
What Lenders Look at When You Apply in Toronto
Lenders assess five core factors, character, capacity, capital, collateral, and conditions, and the strength of your file across all five determines what gets approved, on what terms, and at what rate. Toronto's competitive market means files need to be well-prepared, underwriters see a high volume of applications and a clean, complete file moves fastest.
Character is your business track record. Years in operation, commercial bureau history, and whether bank statements reflect a business that manages cash responsibly. Documentation requirements vary by lender, transaction size, business history, and credit profile. Toronto's diverse business community includes many newer businesses and owner-operators, a personal guarantee from the principal, a strong personal net worth statement, and verified revenue can support files below standard thresholds.
Capacity is whether your revenue comfortably supports the new payment. Lenders look at monthly bank deposits relative to existing obligations. A Toronto contractor with signed project agreements, a carrier with freight contracts, or a medical practice with demonstrable patient revenue presents a clear picture. Irregular deposits without explanation remain the most common reason files slow down.
Capital is your equity position. Down payments vary by risk profile, stronger files often require little to nothing upfront, while higher-risk profiles may require 10–20%. In Toronto's fast-moving equipment market, having a deposit ready can also be the difference between securing a unit and losing it to another buyer.
Collateral is the asset itself. Lenders assess age, condition, and secondary market value. Construction equipment commonly qualifies up to 15 model years on stronger profiles. Transport assets, particularly Class 8 trucks, have tighter age and kilometre thresholds. Medical and technology equipment presents residual value challenges for lenders given faster depreciation cycles; expect deposit requirements to reflect that.
Conditions cover the deal structure, term length, payment structure, advance amount, and documentation requirements. Larger transactions may require additional financial statements, interim reporting, projections, or other underwriting documents depending on the lender and file.
Thresholds above reflect typical patterns across Mehmi's financing programs. Requirements vary by program and file.
Types of Equipment Financing Available in Toronto
Equipment loansFull ownership from day one. Fixed payments build equity and the asset sits on your balance sheet. Best for long-lived assets Toronto businesses plan to keep, industrial machinery, medical equipment, commercial kitchen builds, heavy construction iron.
Equipment leasingLower upfront cost with end-of-term flexibility, return, renew, or purchase. Well suited for technology, medical, and production assets where equipment cycles faster than useful life. Confirm CCA classification with your accountant, the treatment differs between a capital lease and an operating lease and affects how quickly you recover costs on your tax return.
Conditional sales contractsFixed payments with a nominal buyout at the end. A clean, common ownership path for yellow iron, commercial vehicles, and industrial assets throughout the GTA.
Truck and trailer financingPurpose-structured for Toronto-area carriers running Highway 400, 401, 427, and DVP freight lanes, port-adjacent drayage, and regional GTA distribution.
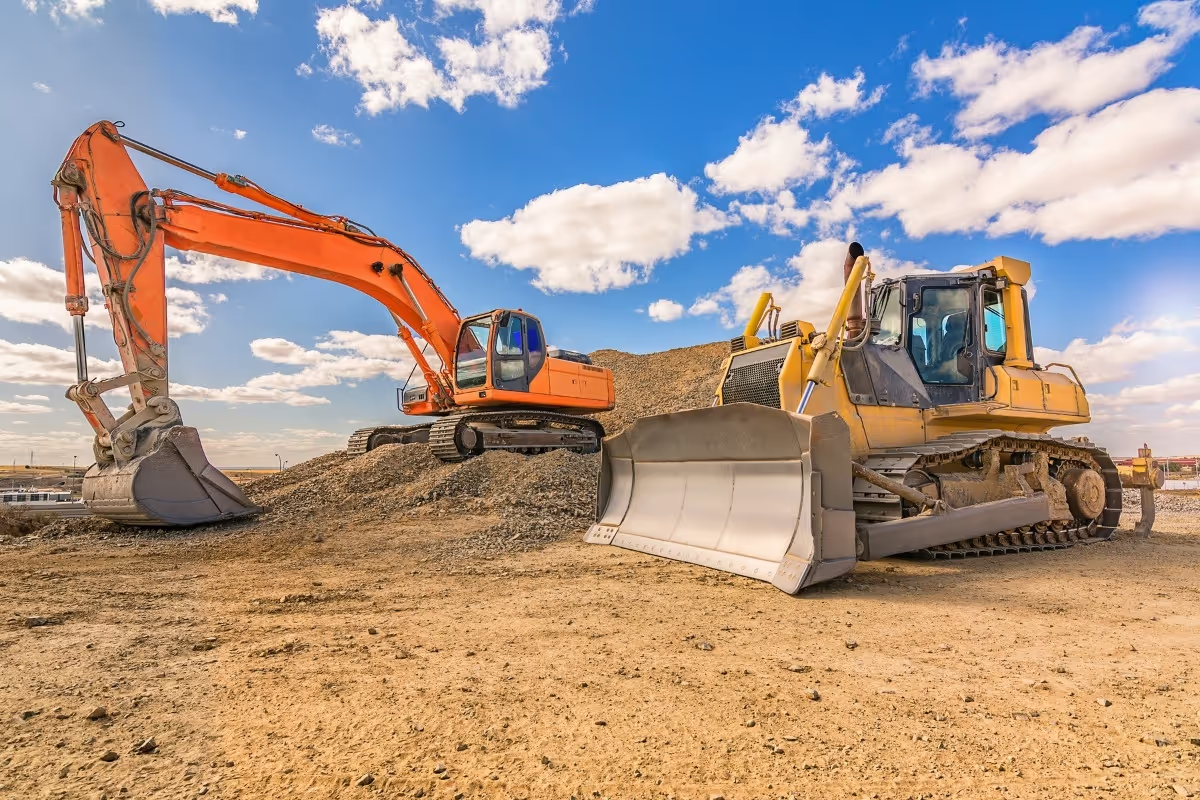
Heavy equipment financingExcavators, cranes, compactors, pavers, aerial lifts, and large industrial machinery for Toronto's active construction and infrastructure sector.
Refinancing and sale-leasebackIf you own equipment outright or have equity in it, a sale-leaseback converts that equity into working capital without selling the asset. Supported on qualifying hard assets up to a reasonable percentage of current market value. Particularly relevant for Toronto businesses where the cost of operating capital is high and equity in owned assets can be deployed more productively.
Asset-based lendingFor larger capital requirements backed by a portfolio of equipment or receivables. Common for mid-size and larger Toronto operators with significant asset bases.
Equipment line of creditA revolving draw facility for businesses financing equipment on a recurring basis, useful for contractors cycling assets across multiple projects and fleet operators managing ongoing capital needs.
Invoice and freight factoringConverts outstanding invoices into immediate working capital. Factoring approval is based primarily on your customers' creditworthiness, not yours, so Credit-review practices vary by factoring provider. Particularly useful for Toronto contractors and carriers managing 30–60 day receivables from large commercial, institutional, or government clients.
Working capital loansShort-term capital to cover operational gaps, bridge periods between equipment payments, or manage cash flow in a market where overhead runs consistently high.
Review the eligible equipment guide to confirm what asset types qualify before applying.
Toronto-Specific Consideration: The Congestion and Urban Logistics Premium
Toronto's traffic environment is among the worst in North America, and it has a direct effect on equipment financing in a way that doesn't get discussed in generic guides. Trucks and commercial vehicles operating in the core of Toronto, on the Gardiner Expressway, or through the 401 and DVP interchange accumulate idling time, wear, and maintenance costs at a much higher rate than comparable assets in smaller markets.
For financing purposes this matters because:
Urban-operated commercial vehicles may show higher maintenance costs relative to kilometre accumulation. A truck running GTA distribution that looks high-cost on a per-kilometre basis may actually be in excellent condition, it's just covering short, congested routes with high frequency. When applying for truck financing in Toronto, context on route type (urban distribution vs. highway haul) helps underwriters assess the asset correctly rather than flagging it as abnormal.
Equipment operating on congested urban construction sitesaerial work platforms, concrete pumpers, cranes working in tight downtown corridors, faces wear patterns that differ from open-site construction. Maintenance records and condition documentation carry more weight than they would on a rural project.
The practical takeaway: Toronto operators with urban-cycle assets benefit from providing brief operational context alongside their applications, not to explain away wear, but to frame it correctly for underwriters who may default to highway-haul assumptions when reviewing transport assets.
HST on Equipment Financing: What Toronto Businesses Need to Know
Ontario charges HST on lease payments, meaning the effective monthly cost of a leased asset in Toronto includes HST on each payment, not just on the purchase price at acquisition. For most Toronto businesses registered for HST, these payments generate input tax credits that can be claimed, but the timing of ITC recovery differs between a lease and a loan or purchase.
On a loan or conditional sales contract, HST is paid upfront on the full purchase price and the ITC is recoverable in that filing period. On a lease, HST is applied to each monthly payment and ITCs are recovered gradually over the term. For Toronto businesses with significant HST accounts, active cash flow management, and high transaction volumes, the timing difference can be material, particularly on transactions over $150,000.
Neither structure is universally better. It depends on your cash position, HST filing frequency, and tax planning. Confirm the most efficient structure with your accountant before committing, especially on larger transactions where the HST component is a meaningful dollar amount.
Mehmi's Take: Toronto's Bank Relationships Are Not an Equipment Financing Strategy
We see this pattern consistently with Toronto businesses: a solid, creditworthy operator, five years in business, good revenue, clean bureau, delays an equipment decision because they're "waiting to hear back from the bank." Three weeks later the unit is gone, the contract window has passed, or the project has been awarded to a competitor who could mobilize.
Toronto's major banks are built for relationship banking, mortgage underwriting, and corporate credit. Equipment financing, particularly on used assets, private sales, or files that don't fit neatly into a standard template, is a secondary product for most bank branches. Their timelines reflect that priority structure.
Mehmi is built exclusively around equipment and commercial financing. That's a different decision process, a different underwriting focus, and a different timeline. For Toronto operators who need equipment funded in days rather than weeks, the right move is to separate the equipment financing decision from the banking relationship entirely.
The 4 reasons to use an equipment finance broker covers this in more detail if you want to understand the structural difference before deciding how to proceed.
Illustrative Scenario: Toronto Mechanical Contractor Funds Three Pieces of Equipment for a Hospital Retrofit
Illustrative example only; not a statement of a specific funded client transaction.
A Scarborough-based mechanical contractor was awarded a subcontract on an HVAC and mechanical retrofit at a mid-size Toronto hospital. The scope required a boom lift, a pipe threading machine, and a service van to be added to their fleet within three weeks of contract signing. Two of the three pieces were available through a Toronto dealer; the third, the pipe threading machine, was a private-sale purchase from another contractor winding down operations.
The challenge: The business had six years of operating history, strong revenue, and a clean bureau, but had recently maxed their bank line of credit on a materials advance for a previous project. Their bank couldn't extend additional equipment credit on the timeline the hospital contract required.
Approval and funding timelines vary by lender, application completeness, and required conditions. The private-sale pipe threading machine required lien verification, seller documentation, serial number confirmation, and condition photos, completed within the same business day the application was submitted. Approval and funding timelines vary by lender, application completeness, and required conditions.
What would have killed it: A business under two years old would have required additional documentation. A private-sale asset without clear title documentation or condition photos would have added days. Submitting the three files sequentially rather than simultaneously would have stretched the timeline past the contract mobilization date.
The outcome: All three assets funded and on-site within the hospital's mobilization window. The contractor met their project start date, preserved the hospital client relationship, and avoided a delay penalty. The invoice and freight factoring facility was activated as a complementary tool for managing the 60-day municipal payment cycle typical of institutional construction clients in Toronto.
Industries We Finance in Toronto
Construction and contractorsToronto's construction pipeline is among the most sustained in North America. High-density residential, transit-oriented development, commercial intensification, and infrastructure retrofits across every corner of the city and inner suburbs drive continuous equipment demand. See the comprehensive guide to construction equipment financing.
Transportation and truckingGTA freight carriers, port-adjacent drayage operators, last-mile delivery businesses, and long-haul operators running out of Toronto's highway interchange network. Read more on trends in commercial truck financing in Ontario.
Medical, dental and wellnessClinics, dental practices, imaging centres, surgical suites, and wellness operators across Toronto's dense residential and commercial neighbourhoods finance diagnostic, imaging, and treatment equipment.
Manufacturing and wholesaleFabricators, food processors, pharmaceutical manufacturers, and industrial operations across Etobicoke, Scarborough, and the East Harbour corridor supply GTA and national markets.
Technology and business servicesProduction hardware, lab equipment, server infrastructure, and specialized tooling for Toronto's MaRS cluster, Yonge-Eglinton tech corridor, and Financial District professional services firms. See our overview of equipment finance rates in Canada.
Hospitality and food serviceRestaurants, hotels, catering businesses, and food service operators across Toronto access kitchen, refrigeration, and service equipment financing. Toronto's hospitality sector is one of the most active in Canada.
Natural resources and energyEnvironmental services, utility operators, and energy businesses headquartered in Toronto access specialized equipment financing.
Farming and agricultureAgricultural operations in the Greenbelt communities surrounding Toronto, Pickering, Ajax, Uxbridge, King Township, and Caledon, access agricultural equipment financing including seasonal payment structures.
Aviation and aerospaceToronto Pearson International Airport, Canada's busiest, anchors a significant ground handling, MRO, and aviation services sector that accesses specialized equipment financing.
How Approval Works in Toronto
Most equipment financing applications require:
- Recent bank statements (typically 3–6 months)
- Government-issued identification
- Business registration details
- Equipment quote, invoice, or bill of sale
Dealer purchases process fastest, application-only files under $250,000 for businesses with two to three or more years in business and a clean bureau are reviewed according to lender requirements.
Private-sale purchases require a verification step, lien search, seller ID, serial number confirmation, and condition photos, but are fully supported. For urban-cycle equipment, brief operational context on route type or utilization pattern helps frame the asset correctly at the underwriting stage.
Larger files over $250,000 may require financial statements depending on your profile and the program. Files over $500,000 typically need three years of accountant-prepared statements plus interim financials. Over $1 million, expect a full structured credit submission including receivables, payables, and financial projections.
Factoring files are assessed on your customers' credit, Credit-review practices vary by factoring provider.
Questions before applying Review the FAQ or explore all financing services to understand every option available.
Ready to get your equipment funded in Toronto? Call us directly at 1-833-863-4644 or apply online to request financing options, subject to lender review.
Related resource: Browse our equipment financing by city directory for more local financing guides.
Toronto equipment financing: a practical purchase decision
For businesses in construction, manufacturing and commercial fleets, the correct structure depends on expected use, ownership preference and the full cost of putting the asset to work. Budget site delivery, commissioning and downtime before comparing a loan with a lease. Ask for comparable proposals showing upfront cash, fees, collateral or guarantee requirements, payment schedule and any end-of-term obligations. No rate, advance amount or approval is assured before lender review.
Equipment dealers serving Toronto customers can also explore a B2B vendor financing program that adds a third-party financing route to the sales process.
3 Steps. No Surprises.
Find the Equipment you need
Get In Touch
Review Your Financing Options
Equipment Financing FAQs for Toronto Businesses
What types of business equipment may qualify in Toronto?
Businesses can request a lender review for eligible CNC mills, commercial vehicles and construction machinery. The equipment's commercial use, seller, age, condition and borrowing entity help determine available financing structures.
Can a Toronto shop finance a used CNC mill?
A used CNC mill can be submitted for review with its seller quote, model, year, condition, hours and available maintenance or inspection records. The lender decides whether the asset, seller and borrower are eligible.
What documents are commonly requested for a Toronto equipment-financing application?
Prepare a written seller quote, equipment details, business registration, bank statements, available financials, existing debt information and a description of how the asset will be used. The lender may request additional information.
Is leasing better than an equipment loan?
Not always. Compare who owns the asset, cash required upfront, all scheduled payments, security, maintenance obligations and end-of-term options. An equipment loan and an equipment lease have different contractual effects.
What down payment or interest rate can a Toronto business expect?
There is no single published down payment or rate that applies to every applicant. Lenders assess the asset, term, financial performance, credit, security and transaction structure. Request a written breakdown of all costs before accepting an offer.
Does Mehmi have to meet the client at a Toronto branch?
No physical local branch is required for an initial inquiry. Eligible applications can be discussed remotely; lender verification or inspection requirements depend on the transaction. We do not represent that an office exists in every city served.
Can a Toronto equipment supplier refer customer financing?
Equipment dealers and distributors can explore third-party vendor financing or a co-branded application path. A referred business remains subject to lender eligibility and underwriting; no approval or funding timeline is guaranteed.