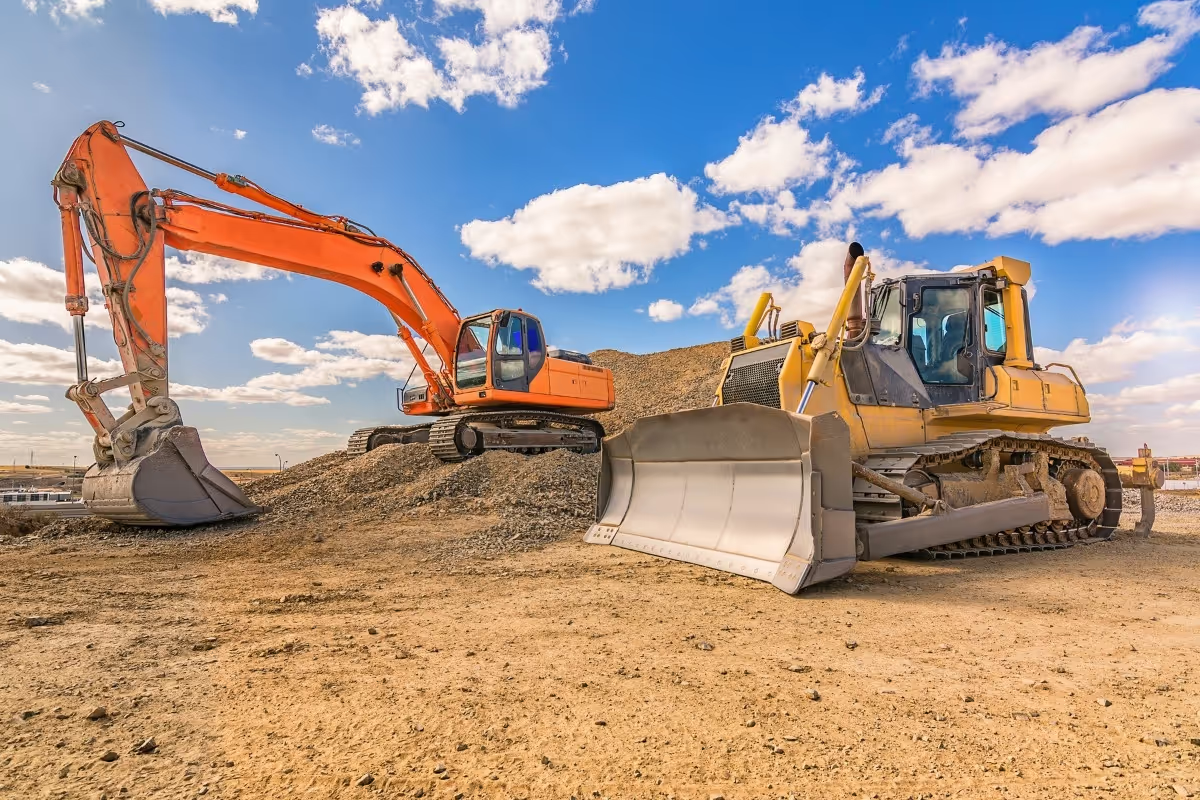
We provide equipment financing in Clarington with financing review, clear terms, and practical repayment structures for construction, trucking, agriculture, energy-adjacent services, and local manufacturers. Used and private-sale equipment may be considered, subject to lender and asset requirements, with terms built for real Durham Region operating cycles.
Equipment financing Clarington business owners can actually use starts with one question: will the equipment create enough reliable cash flow to justify the payment In Clarington, the best structure is usually lease-first, because it lets contractors, manufacturers, farms, service companies and logistics operators preserve working capital while putting revenue-producing equipment to work.
This guide explains what can be financed, how approvals work, how local Clarington conditions affect equipment decisions, what documents lenders want, and how to avoid common mistakes before you sign a quote.
When buying or refinancing business assets in Clarington, compare the structure and total ownership cost—not just the monthly payment. Availability and terms depend on equipment, business credit, cash flow and individual lenders.
| Equipment funding need | Option to compare | What to verify |
|---|---|---|
| Purchasing eligible construction machinery | Equipment loan or conditional sale | Equipment value, term, interest calculation, down payment, collateral, title and early-payout terms. |
| Using equipment while managing initial cash outlay | Equipment lease | Payment schedule, deposits, insurance, end-of-term purchase options, return conditions and total cost. |
| Purchasing from a used-equipment dealer or private seller | Used-equipment financing | Asset age, hours or mileage, inspection, seller verification, lien search and any lender limits. |
| Unlocking equity in owned machinery or vehicles | Equipment refinancing or sale-leaseback | Appraised value, current liens, payout amounts, advance against value, fees and continuing use of the asset. |
| Buying multiple assets or upgrading in stages | Equipment financing facility or separate leases | Each asset's eligibility, draw timing, security, documentation, amortization and combined payment burden. |
Next step: Compare equipment loans, leases and refinancing before requesting indicative terms. Examples above are educational, not offers or approvals.
Equipment financing in Clarington means spreading the cost of essential business equipment over time instead of paying the full purchase price upfront. The goal is not simply to “get approved”; the goal is to match the payment, term, down payment and end-of-term option to how the equipment will earn.
For most small and mid-sized businesses, a lease-first structure is the cleanest starting point. A lease can be built around the equipment’s useful life, expected utilization, seasonality, resale value and cash-flow cycle. That matters if you are buying a skid steer, CNC machine, lift, compressor, trailer, excavator, commercial kitchen package, dental chair, farm implement, shop equipment or technology bundle.
A strong local financing plan answers five practical questions:
Will the equipment replace something unreliable
Will it create new revenue
Will it reduce labour, downtime or subcontracting
Can the business carry the payment during slow months
Does the equipment hold enough value to make the lender comfortable
For a deeper national primer, read Mehmi’s guide to equipment leasing in Canada alongside this Clarington page.
Clarington is not just another GTA market. Local roads, industrial growth, rural land use, ports, transit construction and sector mix can all change what equipment makes sense and how a lender reads the file.
Clarington has direct access to Highways 401, 407, 418 and 35/115, plus rail networks and nearby commercial ports, which supports manufacturing, distribution and cross-border movement. Invest Clarington describes the community as a manufacturing hub with logistics access across Canada and the U.S. (Invest Clarington) Durham Region also identifies Clarington’s strengths in agriculture, energy/nuclear, manufacturing, tourism and retail, and notes major transportation routes including Highways 401, 418, 407 and 35/115. (durham.ca)
That creates four local financing implications.
Clarington’s zoning guide explains that local zoning by-laws define how property can be used, including permitted uses, parking, accessory structures and enforcement. That matters if your equipment needs outdoor storage, yard space, a shop modification or commercial vehicle parking. (Municipality of Clarington)
The Bowmanville GO extension is another local detail. Clarington says the project will add 18.7 kilometres of track to extend Lakeshore East service to Bowmanville, and Durham Region says the project is expected to support 17,000 daily trips and 4.9 million annual boardings by 2041. For equipment buyers, that can mean opportunity for construction, trades and service firms, but also timing risk around road work, utility relocation and delivery windows. (Municipality of Clarington) (durham.ca)
The Port of Oshawa also affects the local equipment economy. HOPA Ports describes the Port of Oshawa as Durham Region’s gateway to the world, handling cargo such as salt, steel products, asphalt and grain, with deep-sea port, rail, airport and 400-series highway access nearby. That supports demand for material handling, fabrication, maintenance, construction and logistics equipment. (HOPA Ports)
Most revenue-producing business equipment can be considered if it is identifiable, insurable, fairly priced and useful to the business. The stronger the connection between the equipment and revenue, the easier it is for an underwriter to understand the file.
Common Clarington examples include:
Construction and landscaping equipment: excavators, compact loaders, skid steers, lifts, compressors, attachments, snow equipment and service tools.
Manufacturing and fabrication equipment: CNC machines, welders, presses, forklifts, pallet racking, shop air systems, dust collection, software and installation.
Agricultural equipment: tractors, implements, harvest-support equipment, irrigation, storage and processing equipment.
Medical, dental and professional equipment: imaging, chairs, sterilization, diagnostic equipment, office technology and fit-out assets.
Restaurant, retail and service equipment: commercial refrigeration, ovens, POS hardware, laundry machines, cleaning equipment and signage packages.
Technology and office equipment: servers, IT hardware, security systems, phones, scanners and bundled installation.
Used equipment can also be financed, but the lender will care more about age, condition, serial numbers, seller credibility, lien status and resale value. If you are comparing new and used equipment, read Mehmi’s guide to used equipment financing in Canada before committing.
The right lease structure depends on how long you need the equipment, how quickly it becomes outdated, whether you want ownership at the end, and how seasonal your revenue is. Do not choose the lowest monthly payment until you understand the whole structure.
Common structures include:
Lease-to-own: Best when you expect to keep the equipment long term and the asset will remain useful after the lease term.
Fair market value option: Useful when lower payments and end-of-term flexibility matter more than guaranteed ownership.
Seasonal payment structure: Helpful for landscaping, snow, agriculture, tourism, construction and other businesses with uneven revenue.
Step payment structure: Can help when equipment needs installation, ramp-up time or a contract start date before revenue normalizes.
Sale-leaseback: A business sells owned equipment to unlock cash, then leases it back and keeps using it. This can help with working capital, but tax and structure need careful review.
Private-sale financing: Useful when buying from another business or individual, but documentation is more important than with a dealer invoice.
A practical opinion: the cheapest payment is often not the best deal. The better structure is the one that lets you pay suppliers, payroll, HST, insurance and fuel after the equipment arrives. A low payment with a bad buyout, weak flexibility or no working-capital buffer can still be expensive.
To pressure-test payment scenarios, use Mehmi’s equipment financing cost calculator for Canada. To understand pricing variables, review average equipment financing rates in Canada.
Lenders think like risk managers. They are not only asking whether the equipment is useful; they are asking whether the business can pay if a customer is late, a job is delayed, the machine needs repairs or the economy tightens.
Most credit teams use a version of the 5Cs.
Character: Does the owner pay obligations on time Are there missed payments, collections, unpaid taxes, NSF activity or unexplained credit issues
Capacity: Can the business afford the new payment after rent, payroll, existing leases, supplier accounts, fuel, insurance and taxes
Capital: Is the owner contributing money or preserving enough cash to operate safely Down payment is not always required, but it can help when the deal is larger, newer, specialized or used.
Collateral: Can the lender identify, insure, register, repossess and resell the equipment if the deal fails
Conditions: What is happening around the business, industry, asset type, location, contract pipeline and interest-rate environment
As of May 2026, rate conditions still matter. On April 29, 2026, the Bank of Canada held its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and deposit rate at 2.20%. That does not set your lease rate directly, but it influences lender funding costs and how carefully underwriters test affordability. (Bank of Canada)
Behind the scenes, lenders also think in three risk components: probability of default, exposure at default and loss given default. Plain English: how likely is the borrower to miss payments, how much would still be owing, and how much could the lender lose after recovering the asset
That is why a $65,000 brand-name compact loader for an established contractor may be easier than a $180,000 highly customized machine for a new business with thin deposits. Both may be good equipment choices, but they create different risk for the lender.
A good equipment payment should fit the business after real operating costs, not just on a best-case month. Before applying, test whether the equipment pays for itself under a conservative scenario.
Use this simple underwriting-style check:
A lender does not need a perfect story. It needs a believable one. If the equipment increases production, reduces downtime or replaces rented equipment, show the math. If it supports expansion, show the pipeline.
A clean application package can shorten approval time and reduce conditions. Missing information makes the lender guess, and guesses usually create stricter terms.
Prepare:
Business legal name and registration details.
Owner information and signing authority.
Equipment quote, invoice or purchase agreement.
Serial number, year, make, model and photos for used equipment.
Vendor or seller contact information.
Three to six months of business bank statements.
Recent financial statements or tax returns, depending on deal size.
Proof of contracts, purchase orders or job pipeline for expansion equipment.
Details of existing leases, financing obligations and CRA balances.
Insurance contact information.
Proof of down payment, if required.
For a preparation checklist, use Mehmi’s equipment financing checklist before applying. For documentation detail, see equipment financing approval documents in Canada.
Approval is not funding. A lender may approve the lease but still require conditions to be satisfied before money is released.
Common conditions precedent include proof of insurance, final invoice, serial number confirmation, proof of down payment, corporate signing documents, lien search results, vendor verification and updated bank statements.
After funding, monitoring is usually simple on smaller equipment leases: make payments, keep insurance active, do not sell the equipment, do not move it outside agreed use, and keep the account in good standing. Larger transactions may include covenants such as annual financial reporting, minimum insurance requirements, restrictions on unauthorized asset sales or notice if ownership changes.
What raises concern before a missed payment Repeated NSF activity, cancelled insurance, sudden deposit drops, late supplier payments, unresolved CRA issues, attempts to sell financed equipment, or a borrower who stops communicating.
This is where many good operators can separate themselves. If something changes, communicate early. A surprise is more damaging than a problem with a plan.
Canadian equipment financing has tax and cash-flow details that generic U.S. articles often miss. GST/HST timing, input tax credits, lease expense treatment, CCA treatment and PPSA registration can all affect the real cost.
CRA explains that GST/HST registrants may recover GST/HST paid or payable on purchases and expenses related to commercial activities by claiming input tax credits, subject to eligibility and documentation rules. CRA also notes that expenses must be reasonable in quality, nature and cost relative to the business. (Canada)
The practical gotcha: a quote may look affordable before tax, while the funded amount, down payment or monthly payment may include tax depending on the structure. A GST/HST registrant may recover eligible amounts later, but cash flow still matters today.
For Canadian tax context, review Mehmi’s guides on GST/HST on equipment leases in Canada and GST/HST input tax credits on financed equipment. Speak with your CPA before choosing a structure mainly for tax reasons.
Ontario borrowers should also expect PPSA registration on many secured equipment transactions. This is not a bad sign. It is how a lender records its security interest in the financed asset.
Most financing problems are avoidable. They come from mismatched structure, weak documentation or a story that does not connect the equipment to repayment.
Avoid these mistakes:
Applying with only a screenshot instead of a complete quote.
Buying used equipment without serial numbers, photos or lien comfort.
Ignoring HST when calculating payment affordability.
Choosing a term longer than the equipment’s practical earning life.
Assuming zero down is realistic on every used or specialized asset.
Using personal bank statements when business revenue runs elsewhere.
Not explaining recent NSFs, tax arrears or credit issues.
Financing equipment before confirming zoning, storage or installation requirements.
Comparing offers only by payment instead of term, fees, buyout, down payment and conditions.
Bad credit does not automatically mean no approval, but it changes structure. If credit issues exist, read Mehmi’s guide to bad-credit equipment financing before applying.
Illustrative example only; not a statement of a specific funded client transaction.
The practical payoff is that a stronger structure can turn a borderline file into a fundable one. The equipment, borrower and cash-flow story need to line up.
A Clarington-area contractor needed a $142,000 equipment package: a used compact loader, attachments, delivery, inspection and a small tool package. The first request was 100% financing over the longest available term with no down payment. The business had good revenue, but deposits were seasonal, and the equipment was being purchased through a private seller.
The first concern was not the equipment. It was the risk stack: used asset, private sale, soft costs, seasonal deposits and no borrower equity.
The file improved after restructuring.
The owner provided six months of business bank statements, photos, serial numbers, seller ID, proof of ownership, an inspection note, signed snow and property-maintenance contracts, and a clear explanation of how the loader would replace rentals. The borrower also agreed to a modest down payment and a term that matched the equipment’s earning life instead of stretching only for the lowest payment.
Under the 5Cs, the deal became stronger:
Character: clean recent payment history and no hidden tax issue.
Capacity: bank statements supported the payment even outside peak months.
Capital: down payment reduced lender exposure.
Collateral: identifiable equipment with resale demand.
Conditions: the equipment supported confirmed work, not speculative growth.
The approval worked because the owner changed the question from “Can I finance all of it?” to “How do we make repayment and recovery obvious to the lender?”
If you are buying from a non-dealer seller, review Mehmi’s article on private-sale equipment financing in Canada. If you already own equipment and need working capital, compare that with sale-leaseback tax implications in Canada.
A good broker does not just chase an approval. A good broker helps structure the file so the lender understands the asset, the cash flow, the risk and the reason for the purchase.
Mehmi can help Clarington business owners compare lease structures, organize documents, review used or private-sale equipment details, and identify whether a standard lease, seasonal structure, sale-leaseback or heavier-documentation approval path makes sense.
A calm next step: send the equipment quote, business name, purchase reason and recent bank statements to Mehmi before you commit to the seller. A quick structure review can prevent the most expensive mistake: buying equipment first and trying to fix the financing later.
For broader provincial context, read Mehmi’s guide to equipment financing in Ontario.
Related resource: Browse our equipment financing by city directory for more local financing guides.
Related financing options include equipment loans, equipment leasing, and the eligible equipment directory.
Use these guides to compare the equipment, repayment structure and documents suited to your purchase. Links to nearby cities are intended for regional context, not as a claim that Mehmi maintains branches in each location.
When you compare lender offers, assess the financed amount, total payments, applicable taxes, fees, down payment, loan or lease end-of-term obligations and conditions in writing.
These assets may qualify for commercial financing if used for an eligible business purpose. The lender reviews the specific make, model, condition, equipment purchase price, seller and applicant's capacity to repay. Being located in Clarington does not by itself ensure approval.
Recent complete business bank statements, financial reports if requested, existing debt payments and clear explanations of large or seasonal deposits help. For this market, consider the equipment's expected utilization and seasonal deposits. Provide signed contracts or invoices where they actually exist, not assumed future sales.
Potentially. Lenders may ask for year, serial number or VIN, photos, hours or kilometres, seller ID, proof of ownership, lien confirmation and an inspection or valuation. A private sale can require more verification than a dealer purchase.
Some newer firms can be considered, but owner credit, management experience, personal guarantees, additional equity or contracts may be important. Each lender has its own eligibility requirements; acceptance is never automatic.
There is no standard deposit or guaranteed zero-down program. Borrower credit, repayment capacity, asset resale market, lender policy and requested term influence the result. Request a written quote showing upfront funds, fees and cash required at funding.
An equipment loan may better match a straightforward ownership objective. An equipment lease can have a different ownership or end-of-term structure. Compare all instalments, tax treatment, purchase options and early payout clauses.
Ontario HST treatment and input tax credit eligibility depend on the transaction and your business's tax status; confirm details with your accountant. Read the official tax guidance and budget any nonrecoverable taxes instead of comparing payments before tax.
Compare effective total cost, term, down payment, payment frequency, fees, insurance, asset ownership, residual or buyout and repayment restrictions. Estimate cash flow with a hypothetical payment calculator, then request financing options with complete equipment details.